Latest from BCA Research
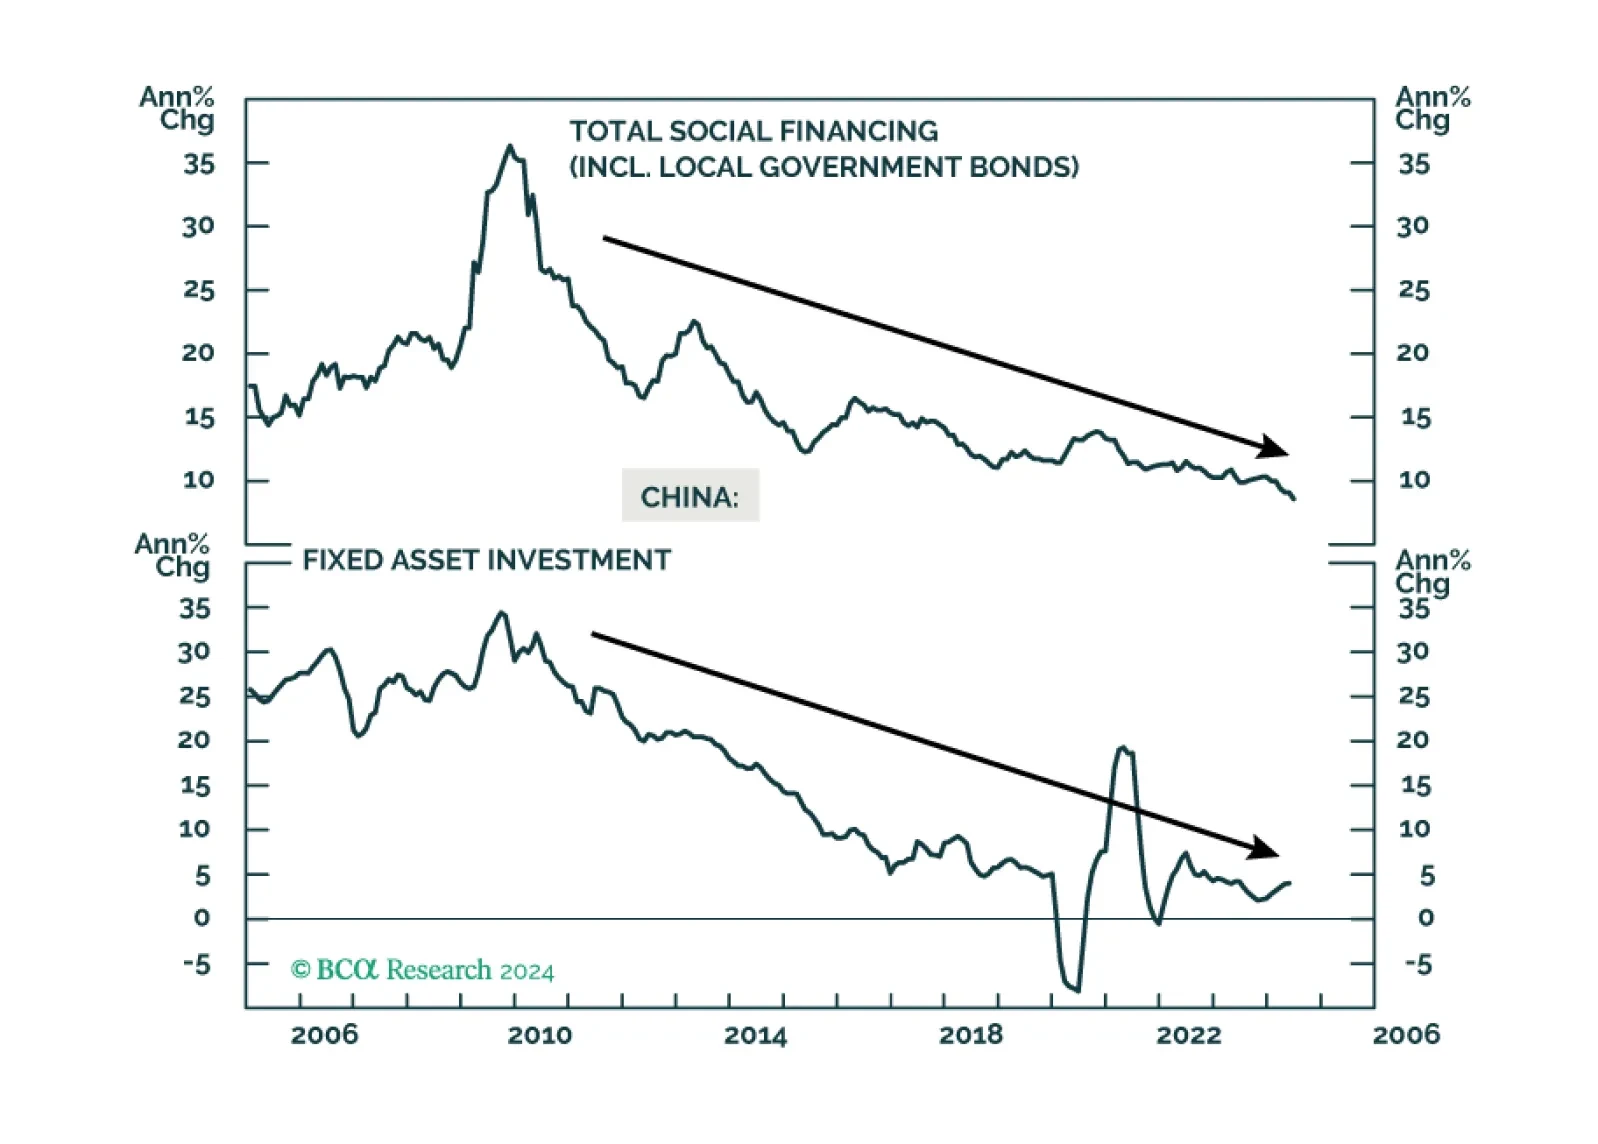
This report provides our framework for interpreting the messages from last week’s Third Plenum, and the potential implications for the economy and investors.
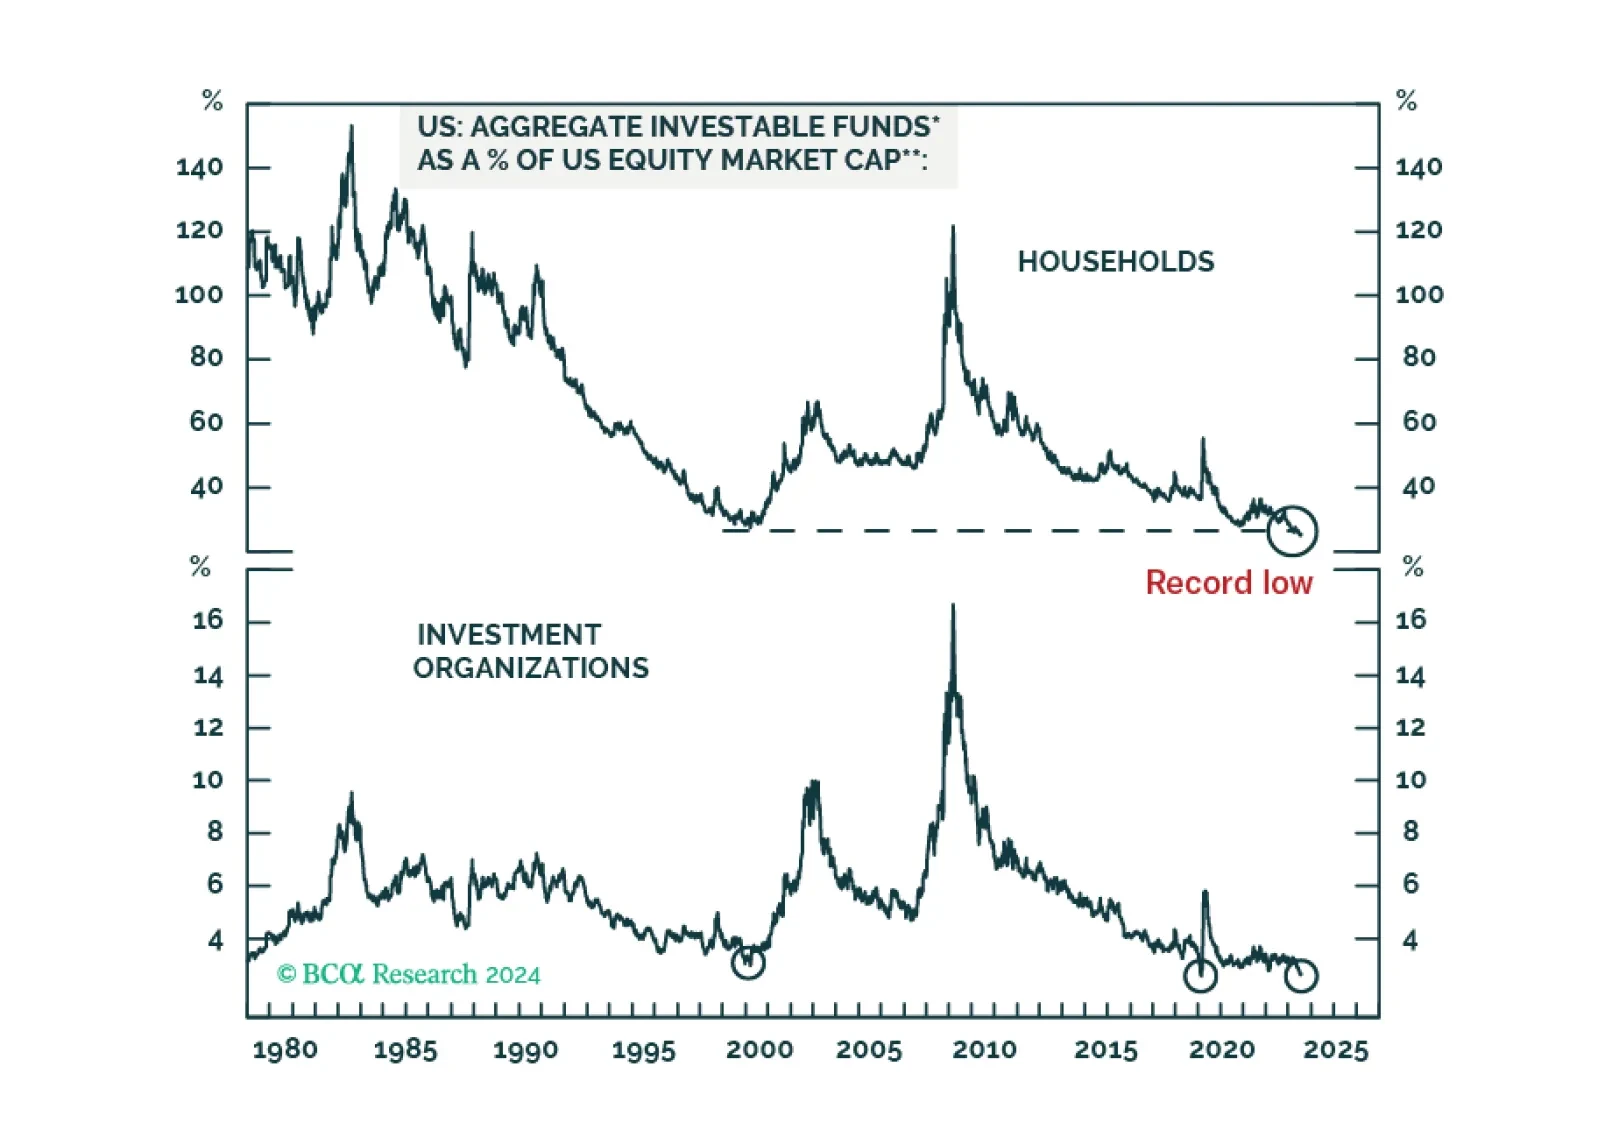
“Cash on the sidelines” as a share of the US equity market cap has declined to a record low. This is true for investable funds of both households and investment firms. Hence, there is little firepower left to sustain the equity rally.

We calculate expected returns for several different US fixed income sectors with a focus on how municipal bonds stack up against the investment alternatives.
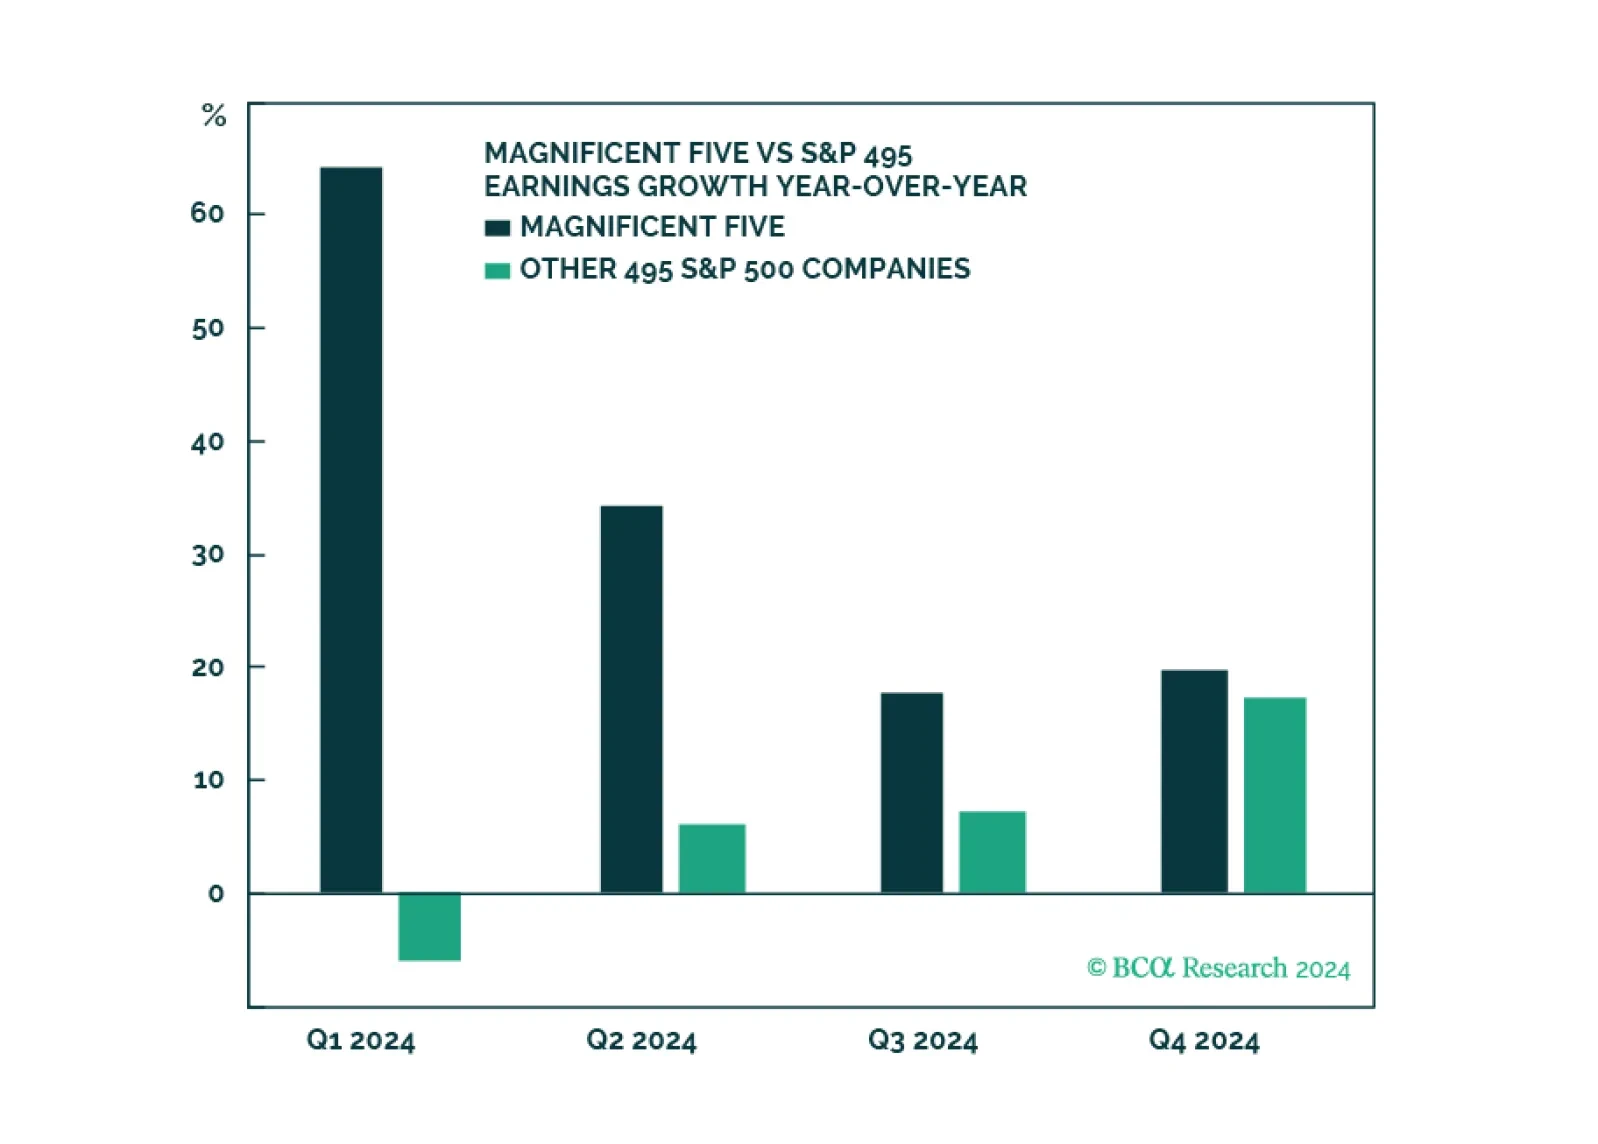
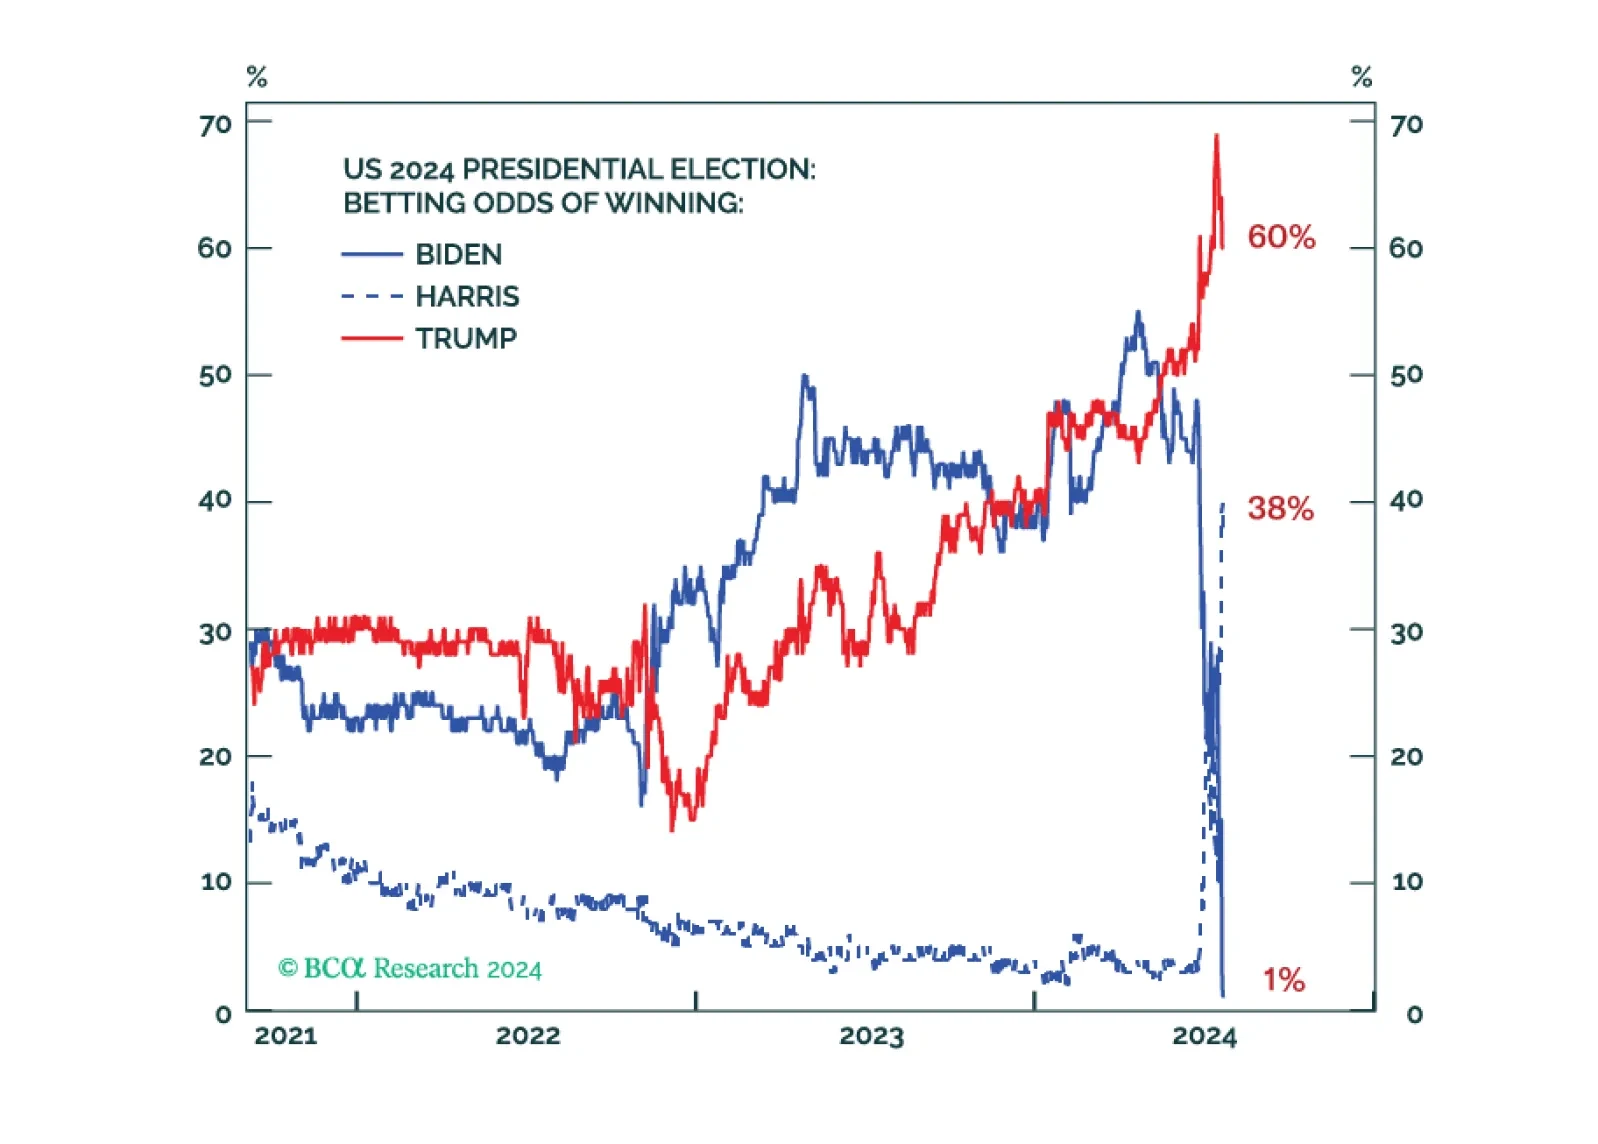
Investors should focus on growth concerns rather than the “Trump trade.” Bond yields will fall in the short run due to cyclically disinflationary economic slowdown, rather than rise in anticipation of a Republican full sweep and inflationary policies, which are likely but not yet a done deal.
President Biden has announced his withdrawal from the presidential race. The news will no doubt come to dominate the news cycle in the upcoming week of July 22, which is unfortunate as it will drown out some important developments from the preceding week.
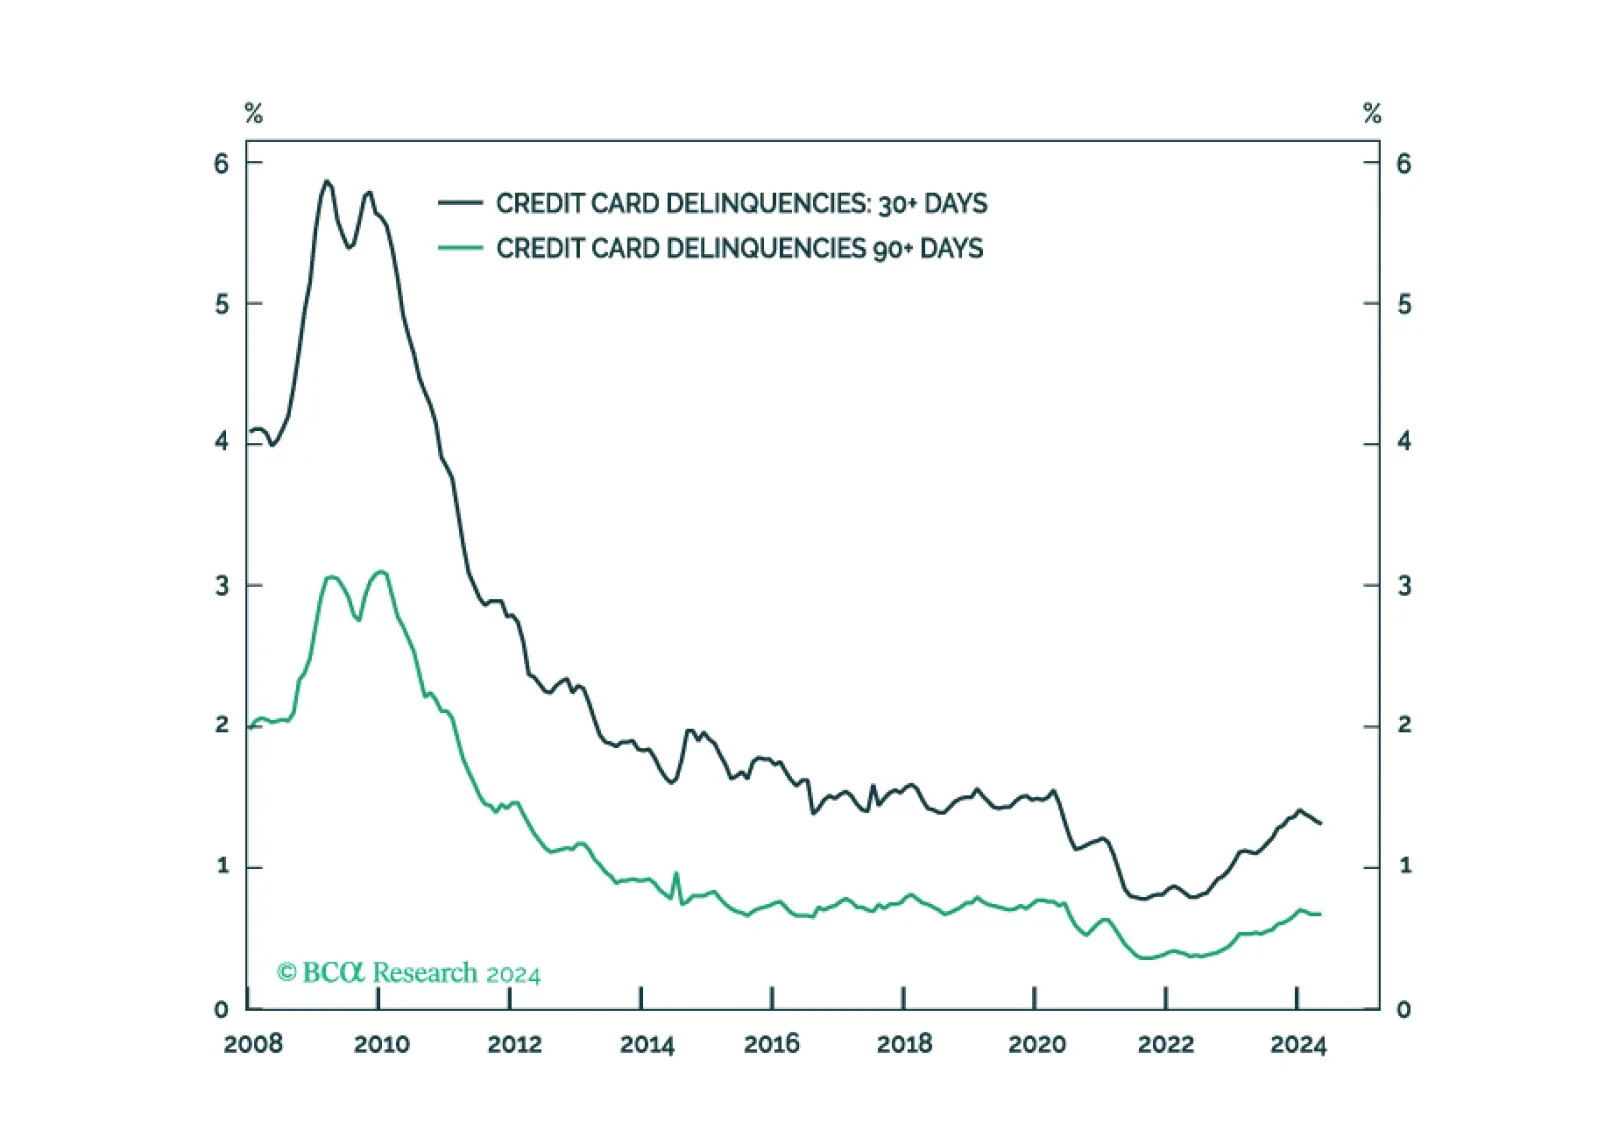
It’s status quo for the SIFI banks, as they don’t see consumer credit performance materially worsening from now-normalized levels and they are not meaningfully exposed to commercial real estate losses.

As Trump’s victory odds rise, the underperformance of European equities deepens. How negative would a global trade war be for European assets?
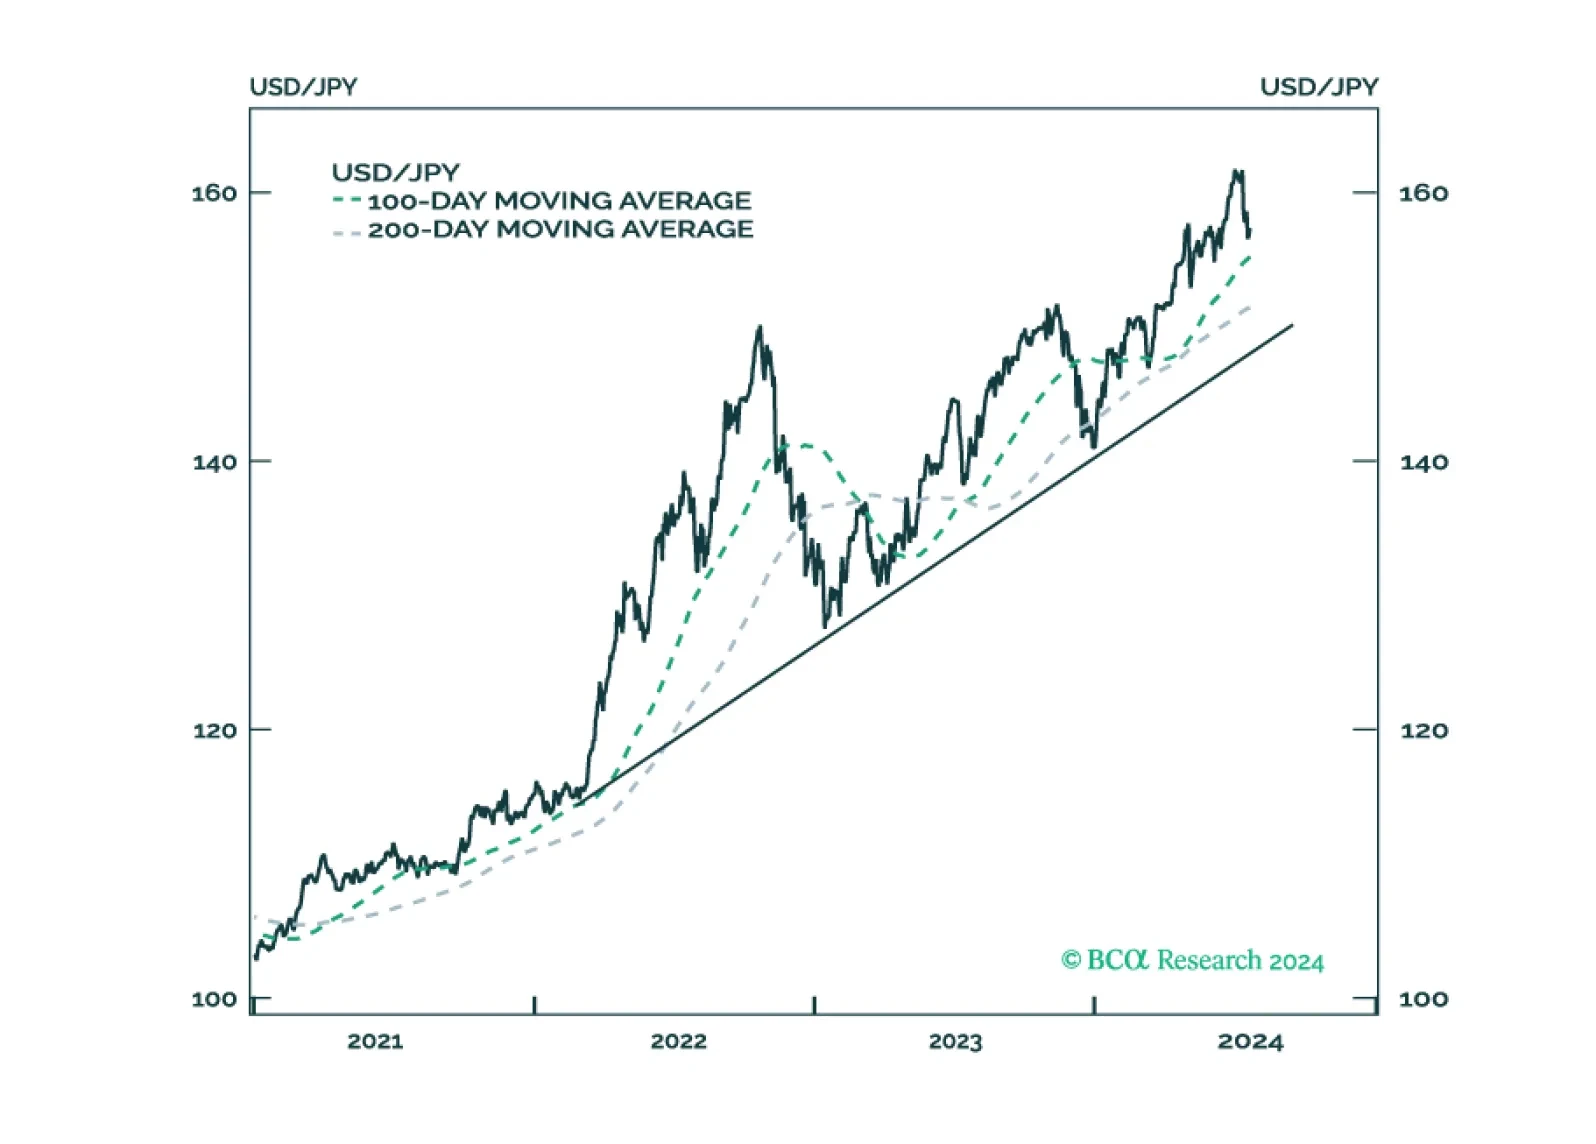
We review some of the key data releases this week that we find have an impact on our currency strategy. Long yen positions make sense today. Long sterling and the euro bets are more of a judgment call, and we will fade any strength in these currencies. This report delves into these nuances, and suggests a few trade ideas.
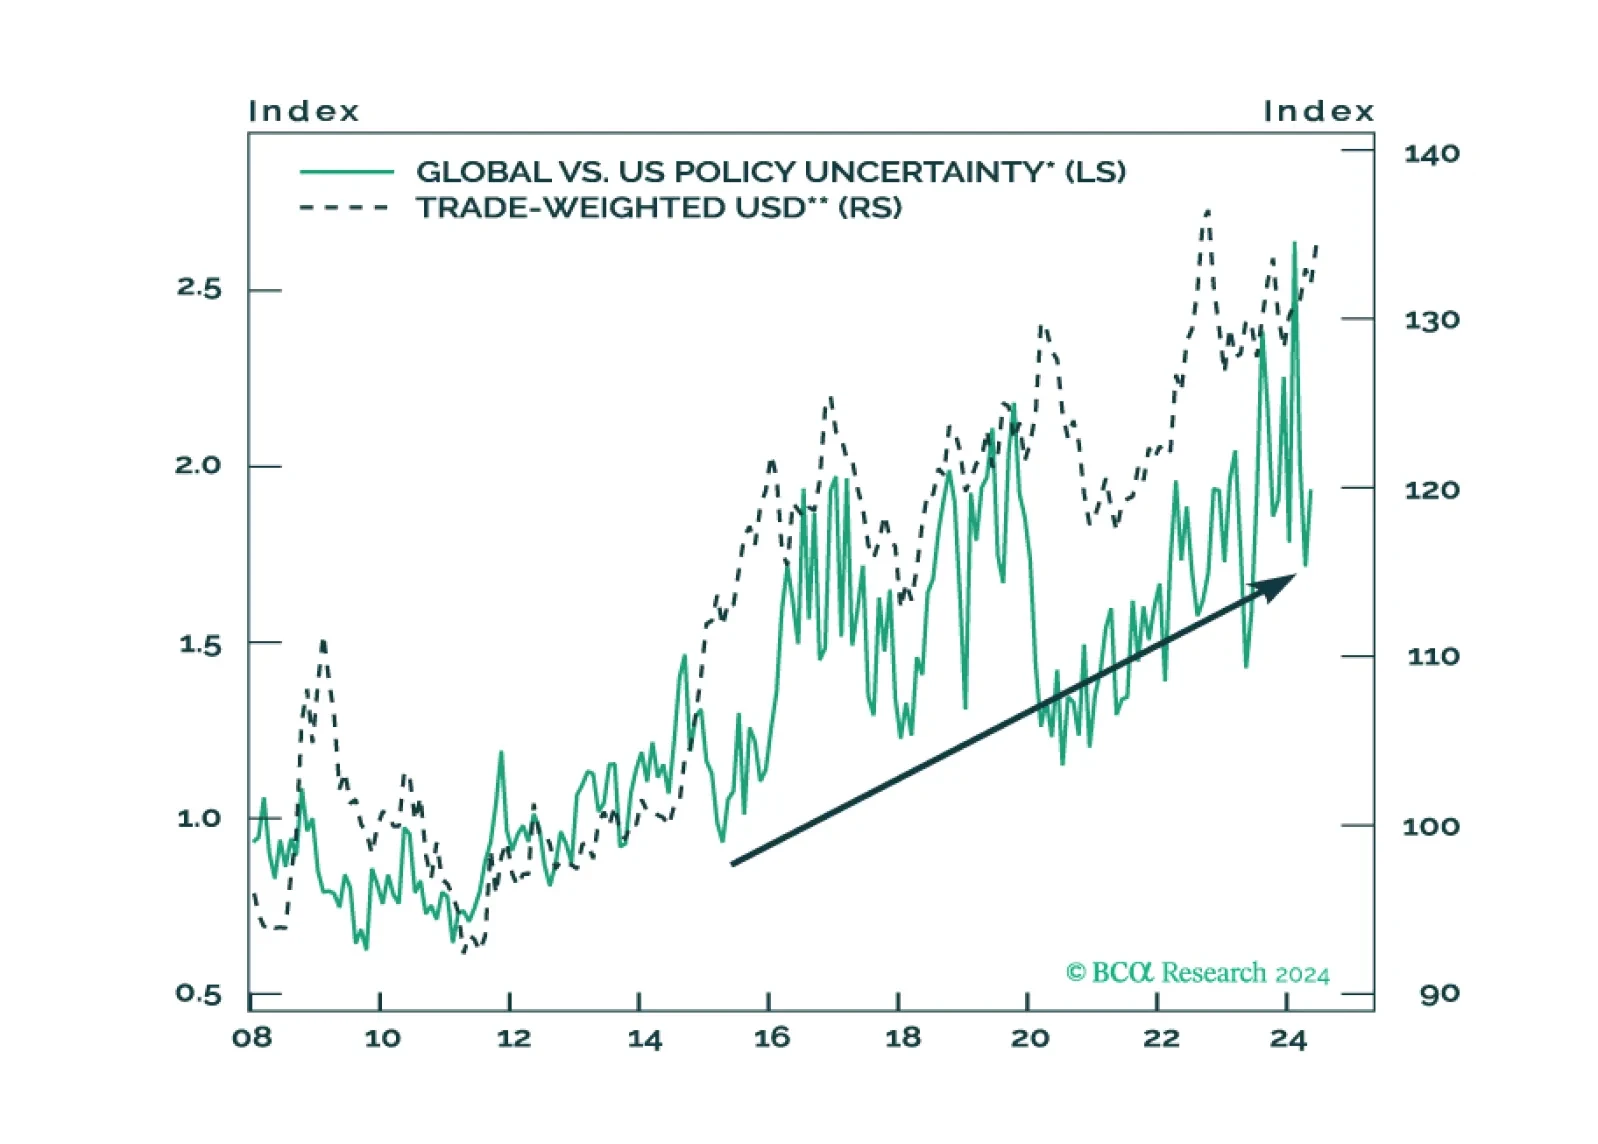
Investors should overweight US assets and de-risk their portfolios in anticipation of a major increase in policy uncertainty and geopolitical risk surrounding the US election and its global ramifications.