Latest from BCA Research
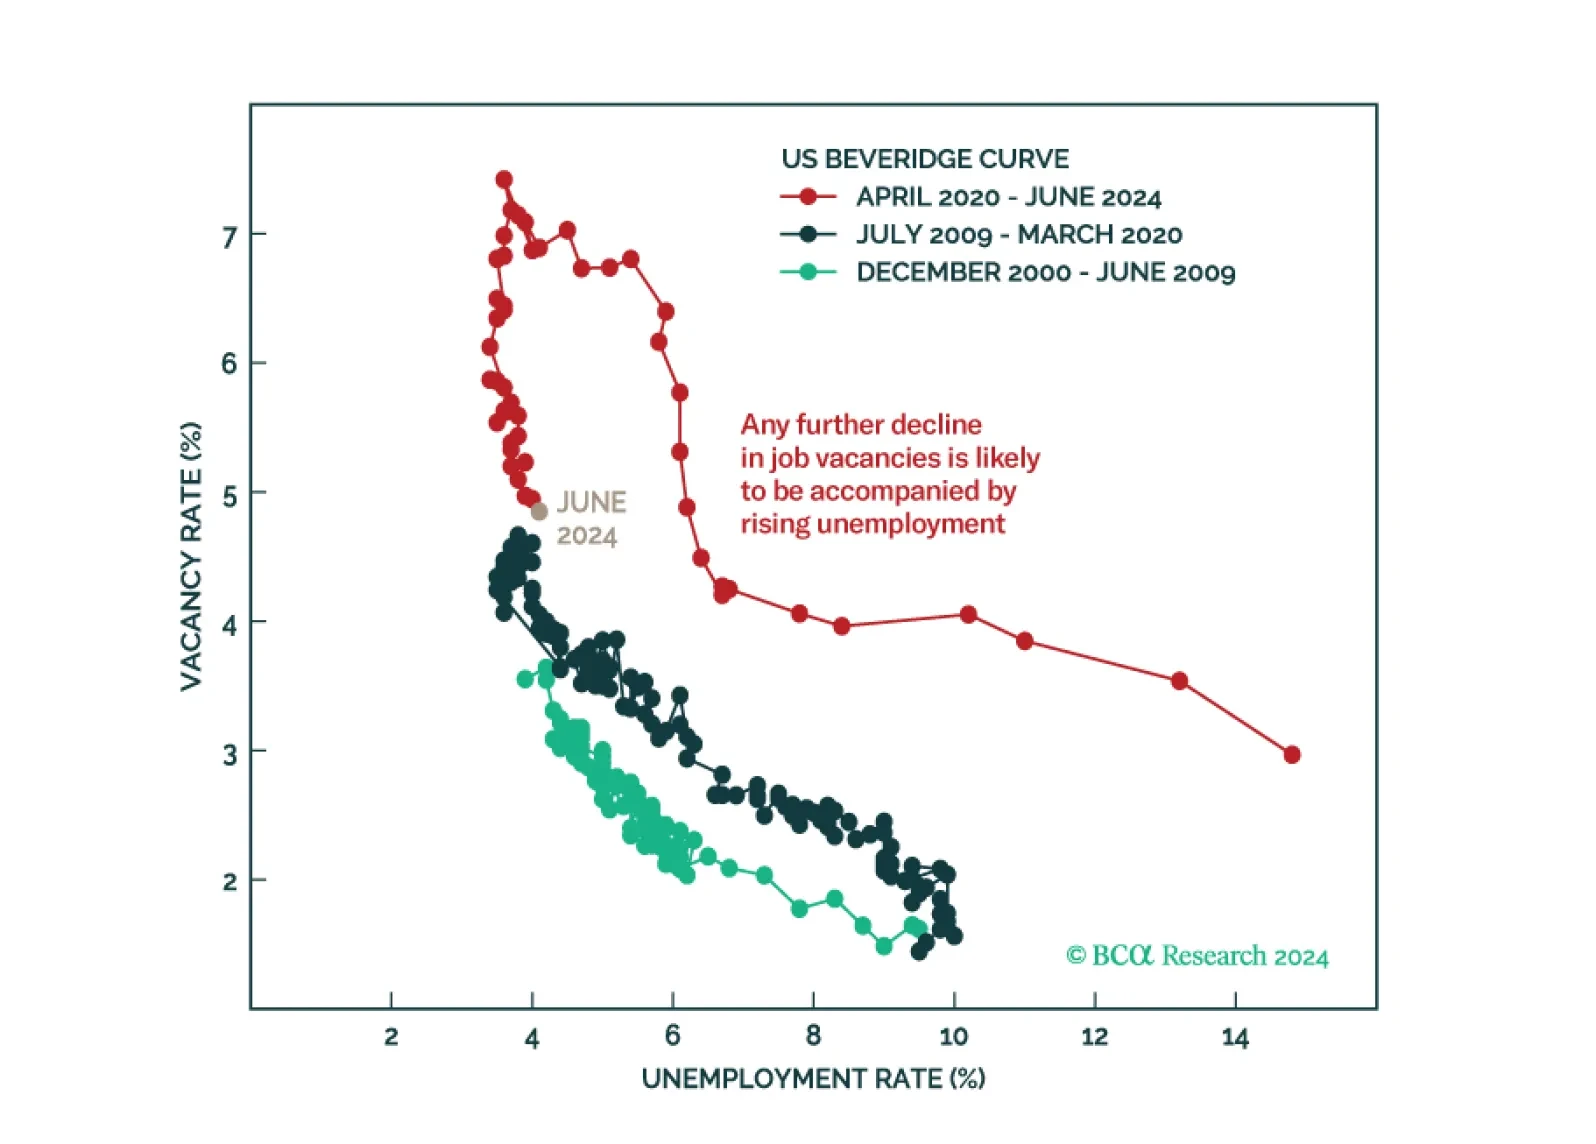
Don't buy the dip. The equity bull market is over. The US will enter a recession in late 2024 or in early 2025.
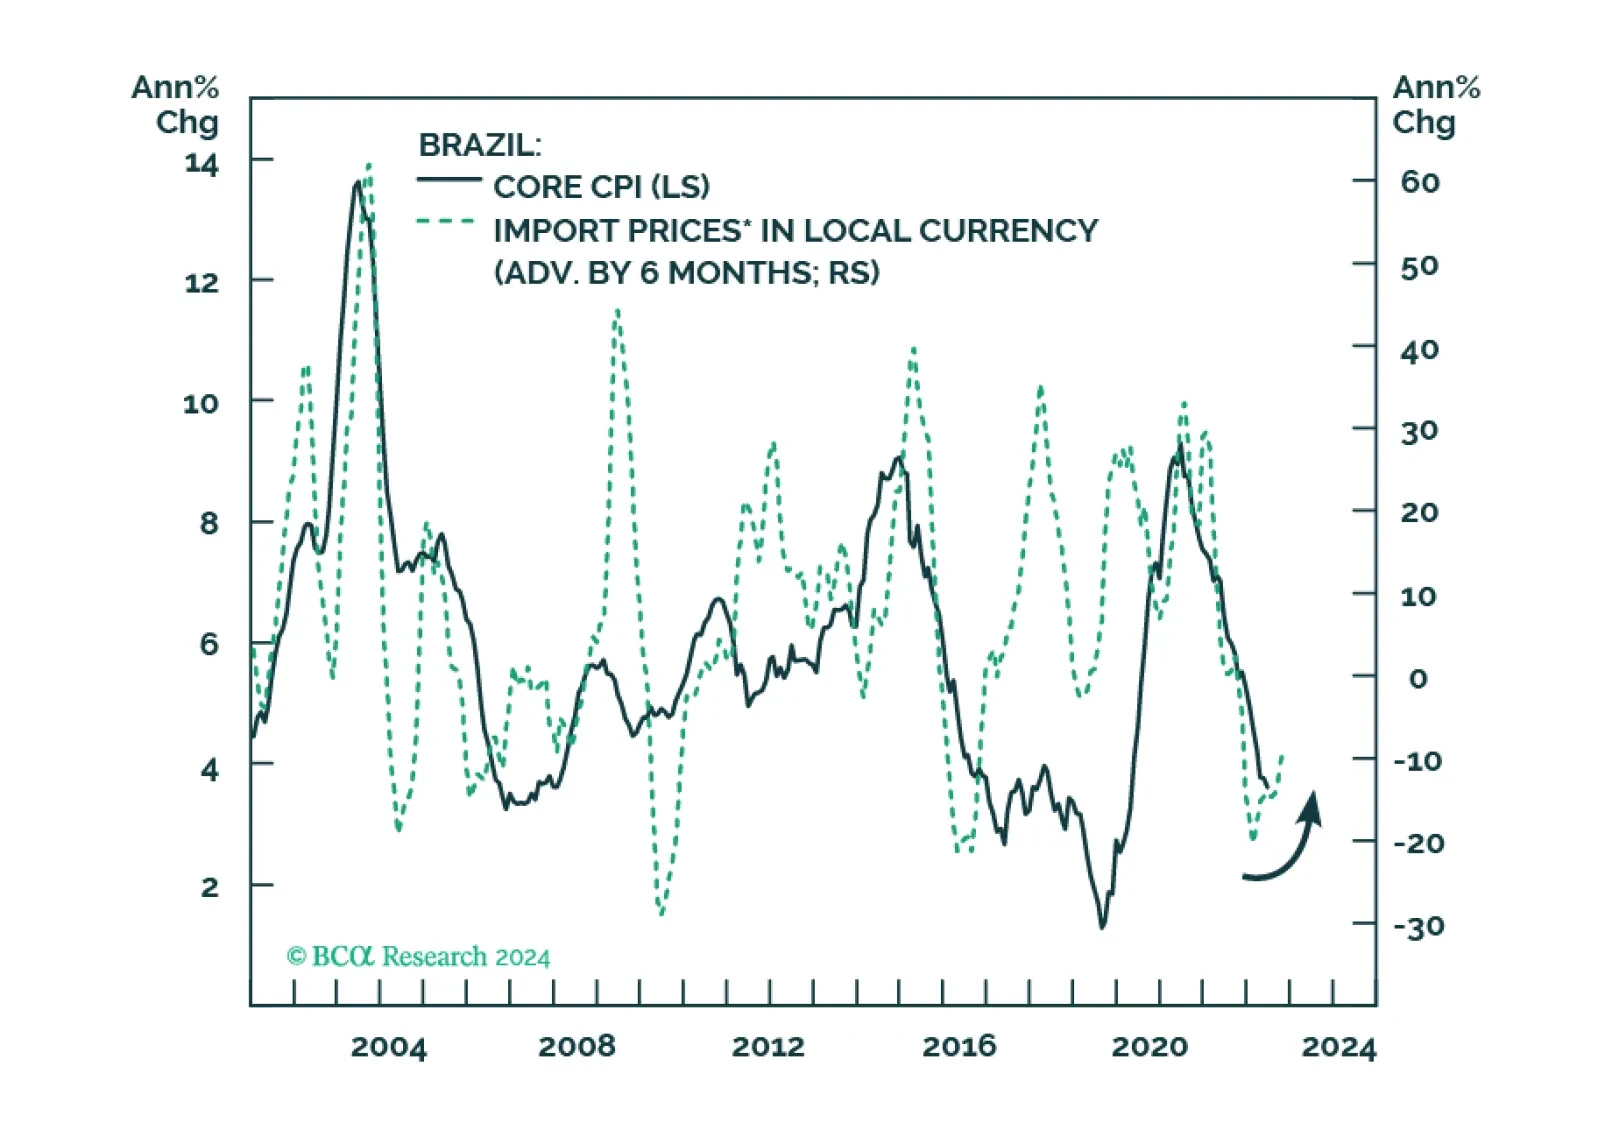
Brazil’s two macro demons – a rising public debt-to-GDP ratio and inflation – have resurfaced and will worsen over the coming months. Yet, President Lula will pay lip service to fiscal concerns without enacting meaningful cutbacks. In addition, a politicized COPOM will cut rates aggressively next year and fall behind the inflation curve. All in all, the selloff in Brazilian markets still has legs.
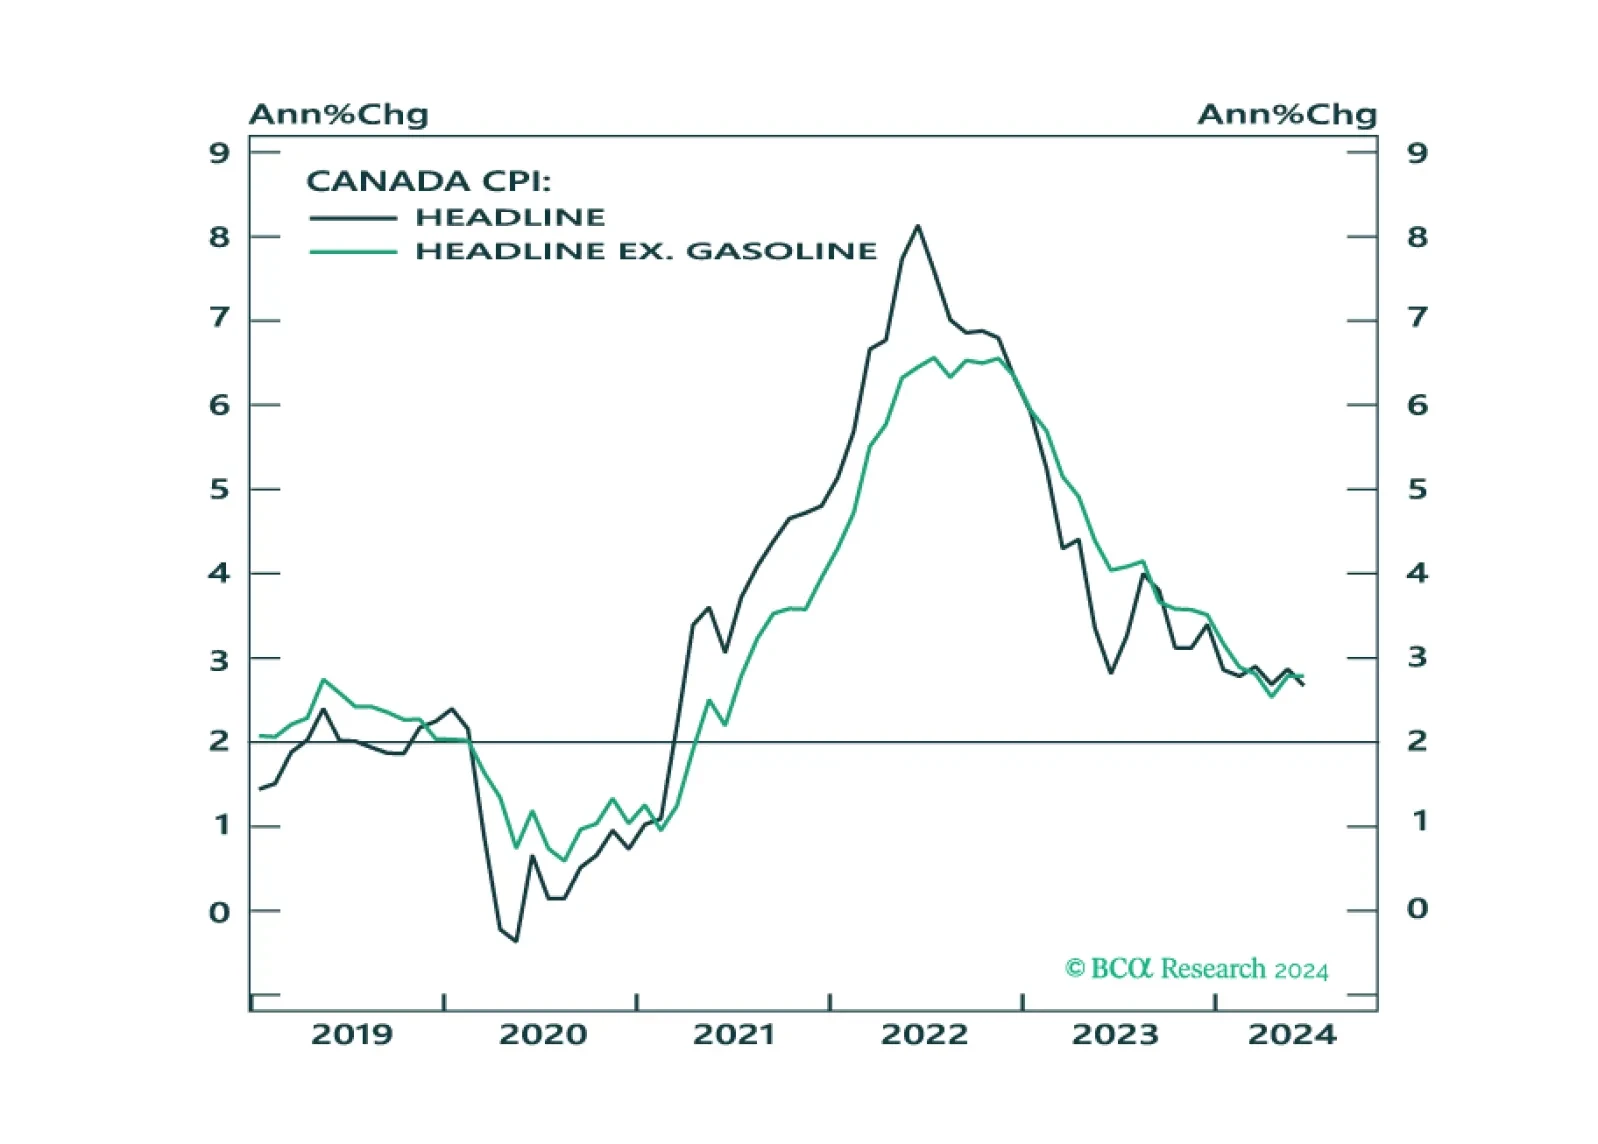
In this Insight, we look into the recent CPI release in Canada, and the possible implications for fixed-income market trades.
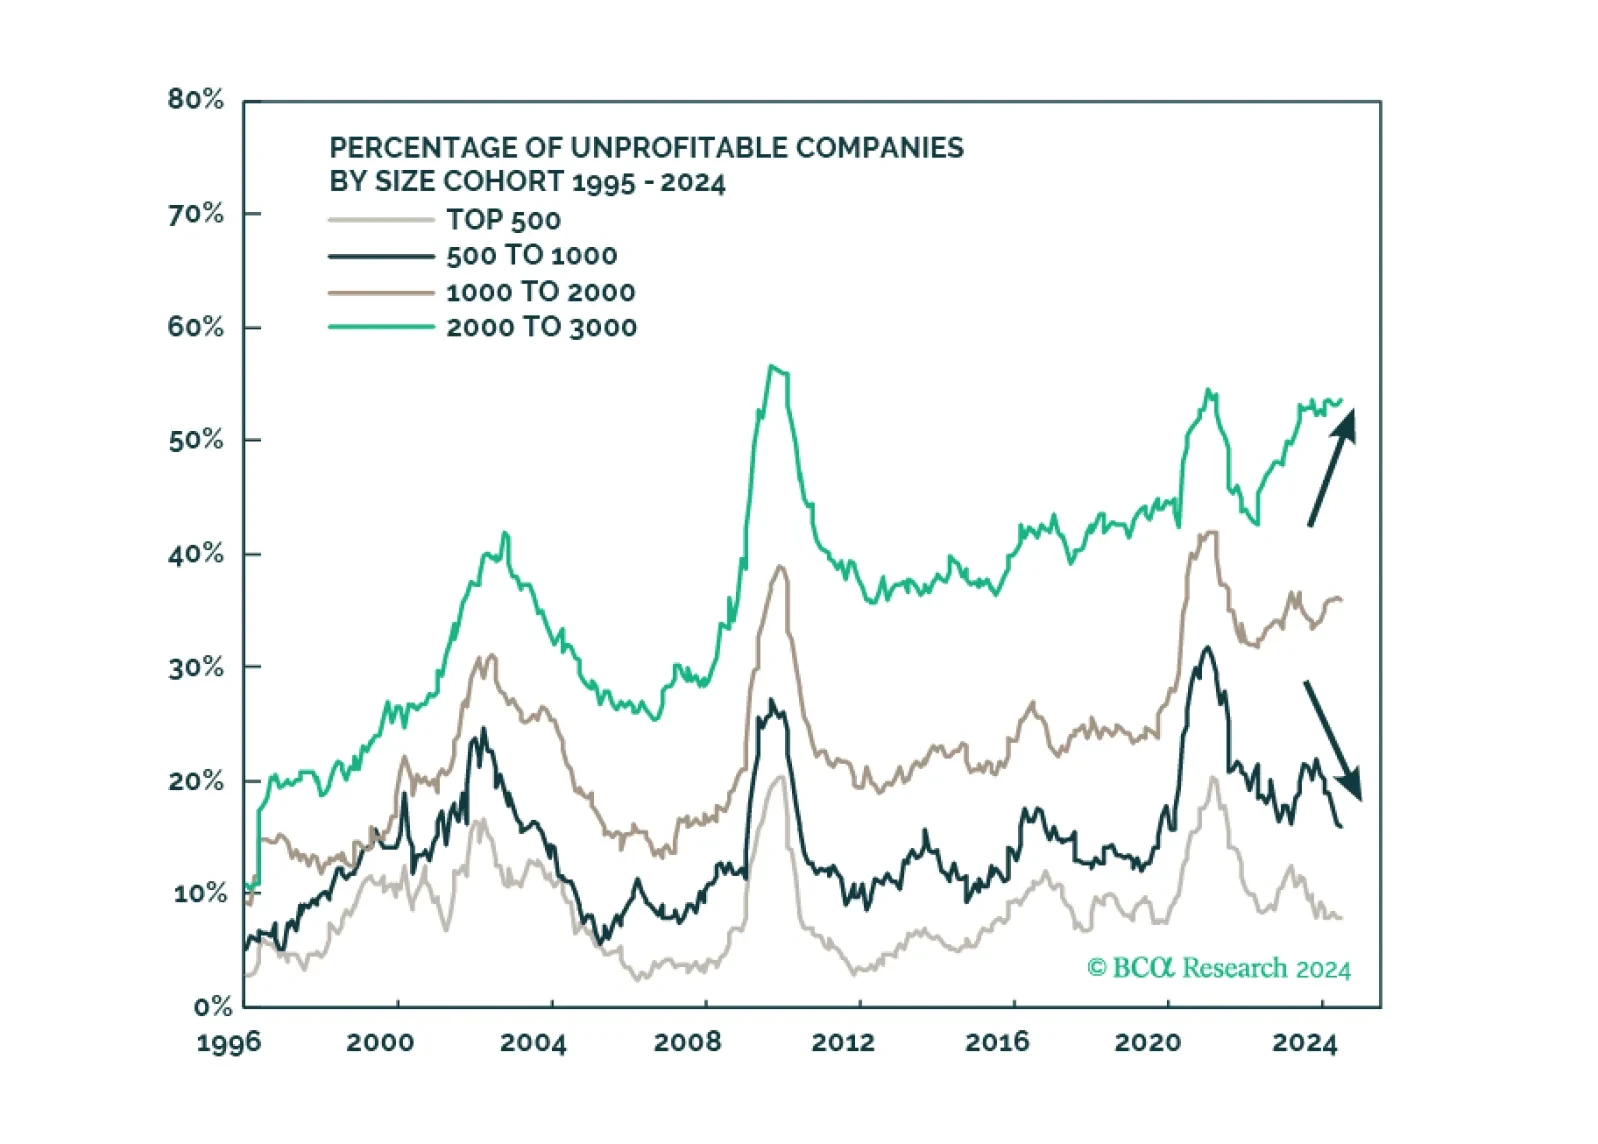
There is a broad-based deterioration of the economic data and a slowdown in consumer spending. On the bright side, inflation prints are better behaved. Rate cuts appear increasingly likely, but they won't stave off a recession. It is time to take profits from the GAI-related industries and bolster the defensive properties of the portfolios. Position for rate cuts.
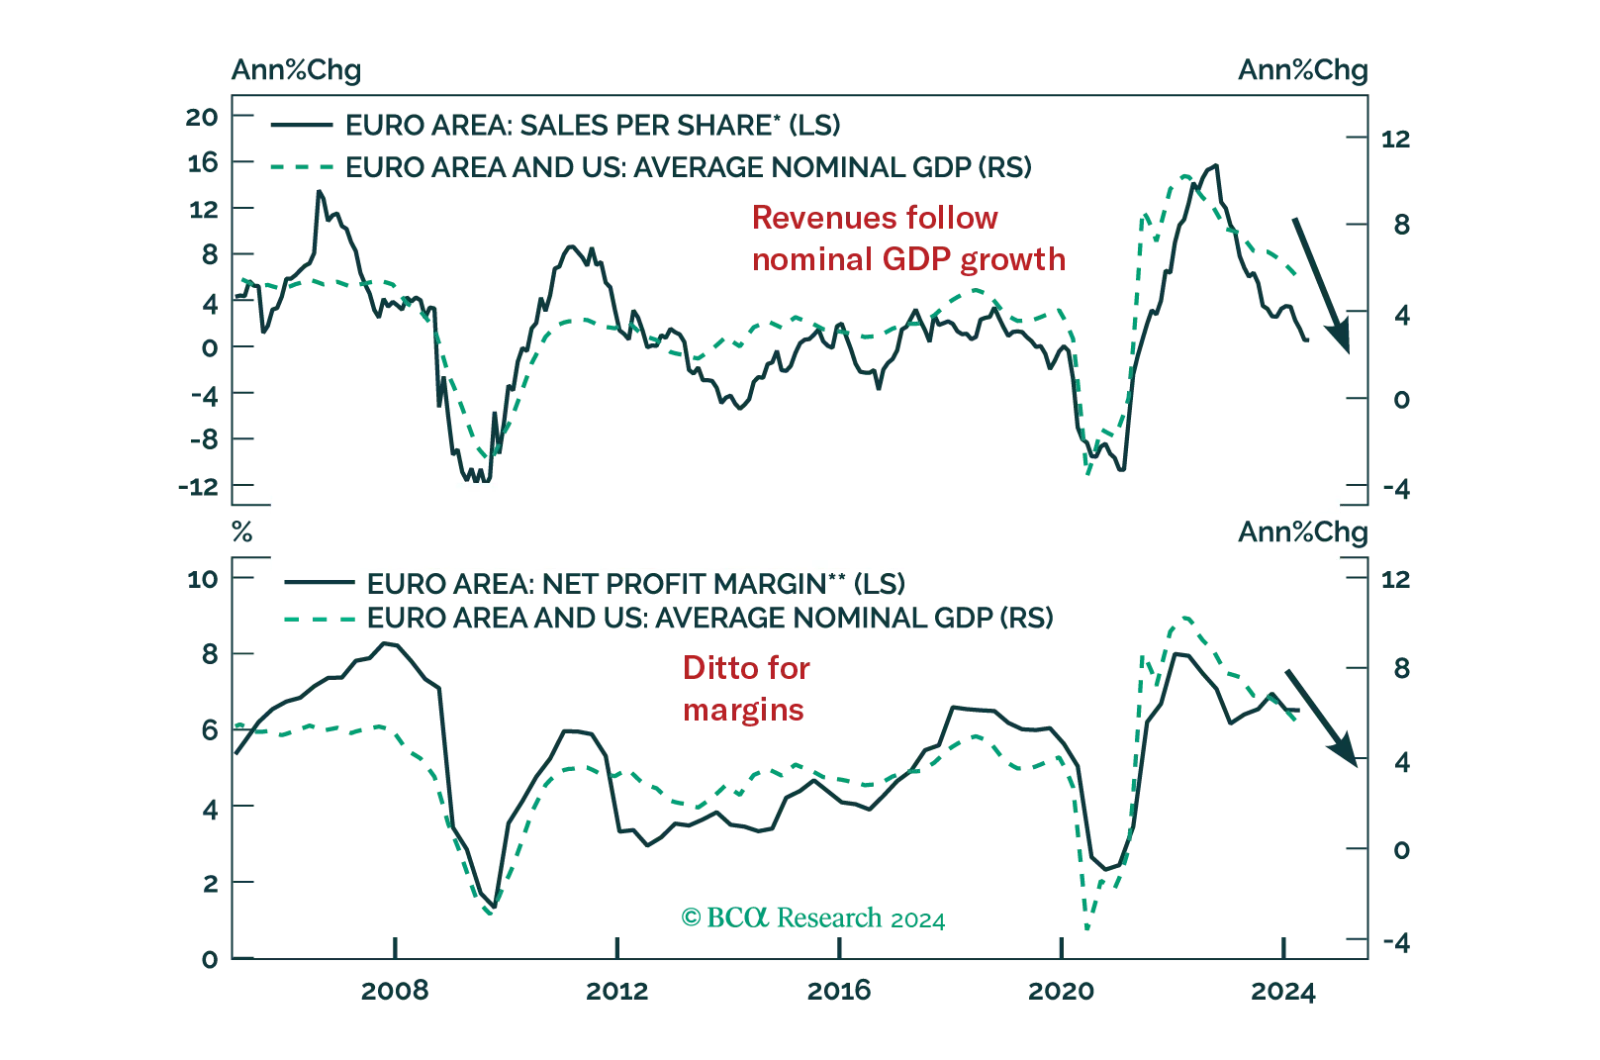
The real threat to European equities is growth, not political risk. How low will Eurozone earnings fall during the coming recession and how much will equities decline in response?

The cyclical economy is slowing today. Republicans are now more likely to win a full sweep, crack down on immigration and trade, and at least modestly stimulate the economy. Uncertainty and volatility will rise.
Today’s attempted assassination against President Trump challenges the consensus view. It will ensure that President Trump’s supporters are highly motivated for the upcoming general election. And it may return many supporters who had drifted away from the former president back into the fold.

In this report, we present the quarterly review of our Model Bond Portfolio. Rebounding growth and political instability led to slightly negative portfolio performance in Q2/2024. As global growth starts to moderate, we continue to favor government bonds over credit. Maintain a defensive portfolio stance.
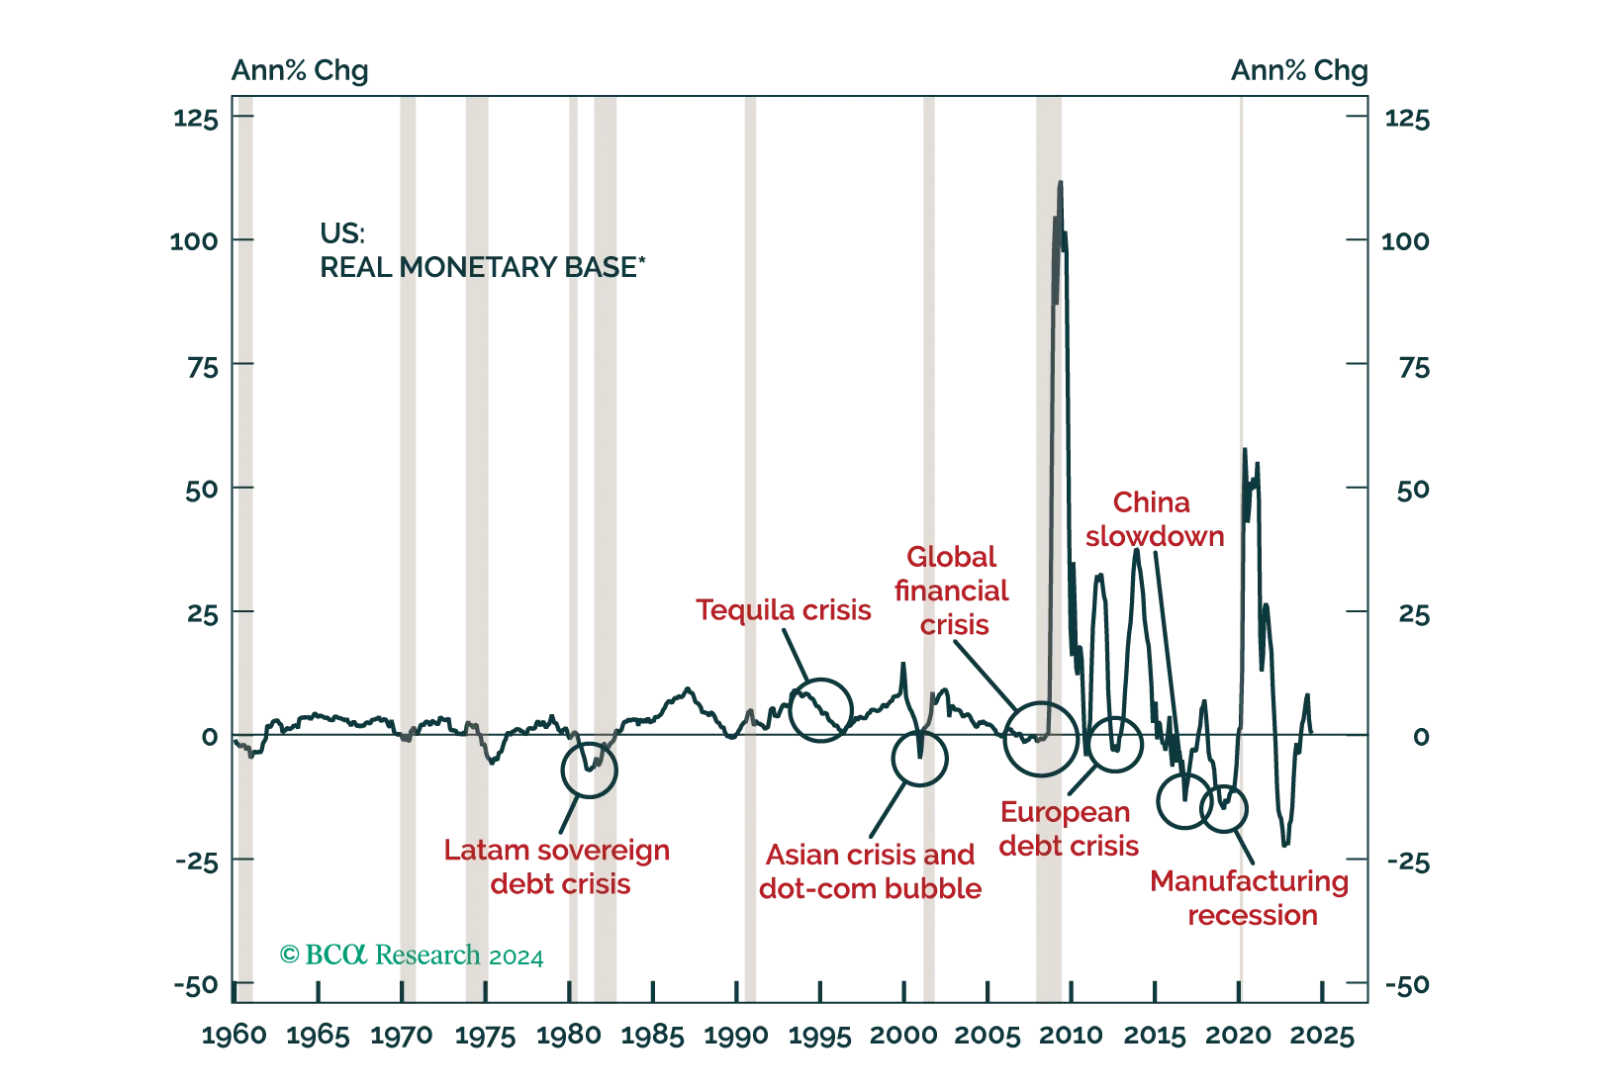
US dollar liquidity has been shrinking, which has important ramifications for global asset prices, including currencies. In this report, we delve into the process of dollar liquidity creation and the outlook for currencies over the next six-to-twelve months.
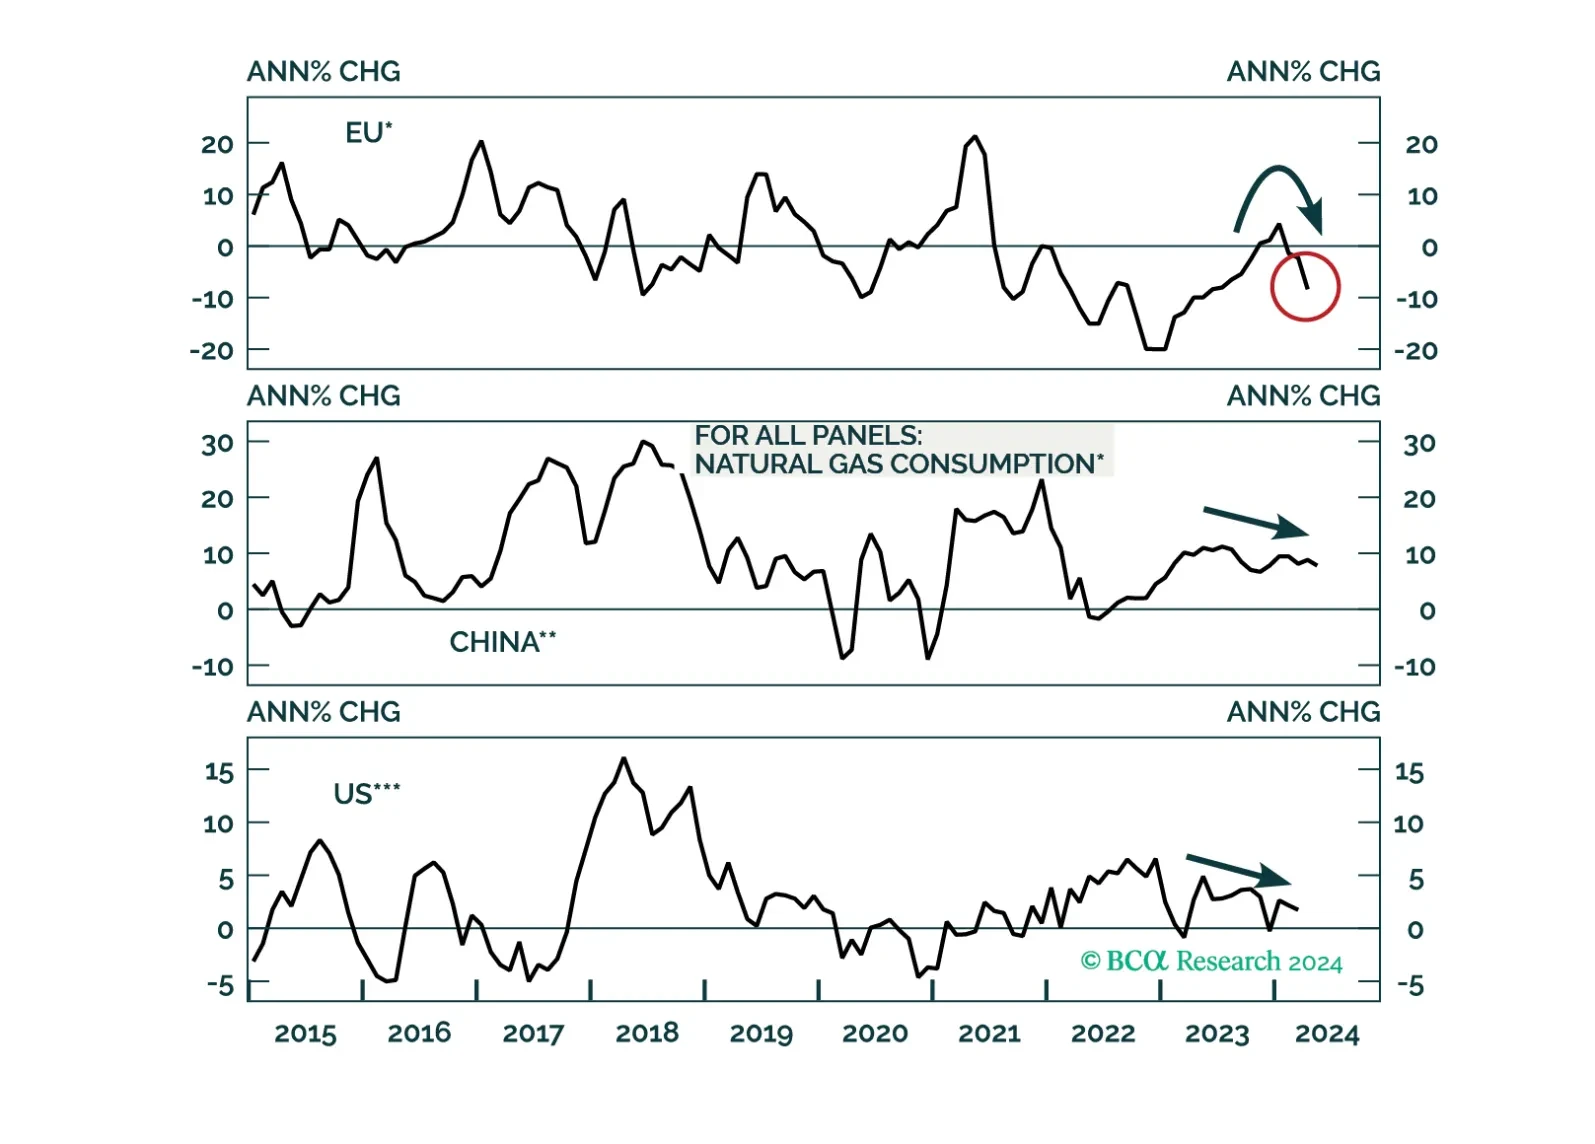
A global economic downturn will be a headwind for natgas prices over the cyclical horizon. Thereafter, LNG capacity additions will help keep the market in balance into the end of the decade. That said, Europe’s increased dependence on global LNG flows raises its exposure to market dynamics in the rest of the world. This will keep volatility elevated versus pre-Ukraine war.