Latest from BCA Research
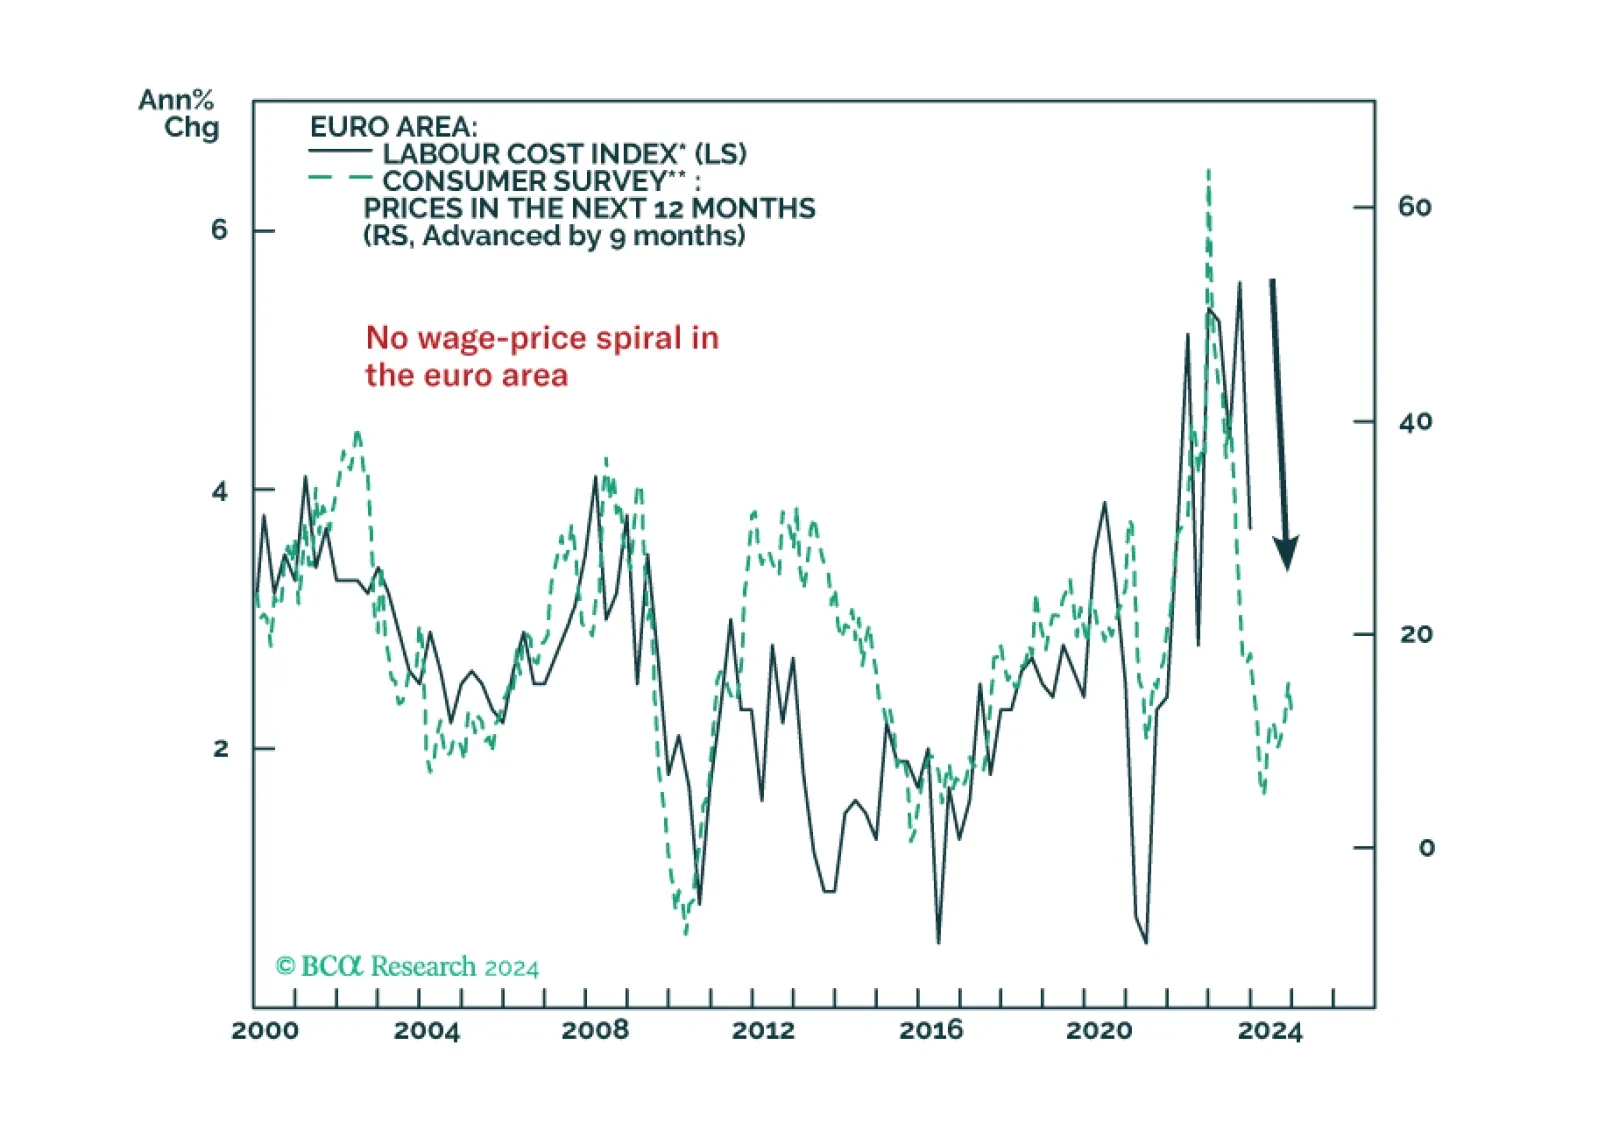
At today’s monetary policy meeting, the ECB gave strong hints that rate cuts will begin as soon as the next meeting in June. In this Insight, we share our thoughts on today’s meeting and discuss the implications for European bond yields and the euro.
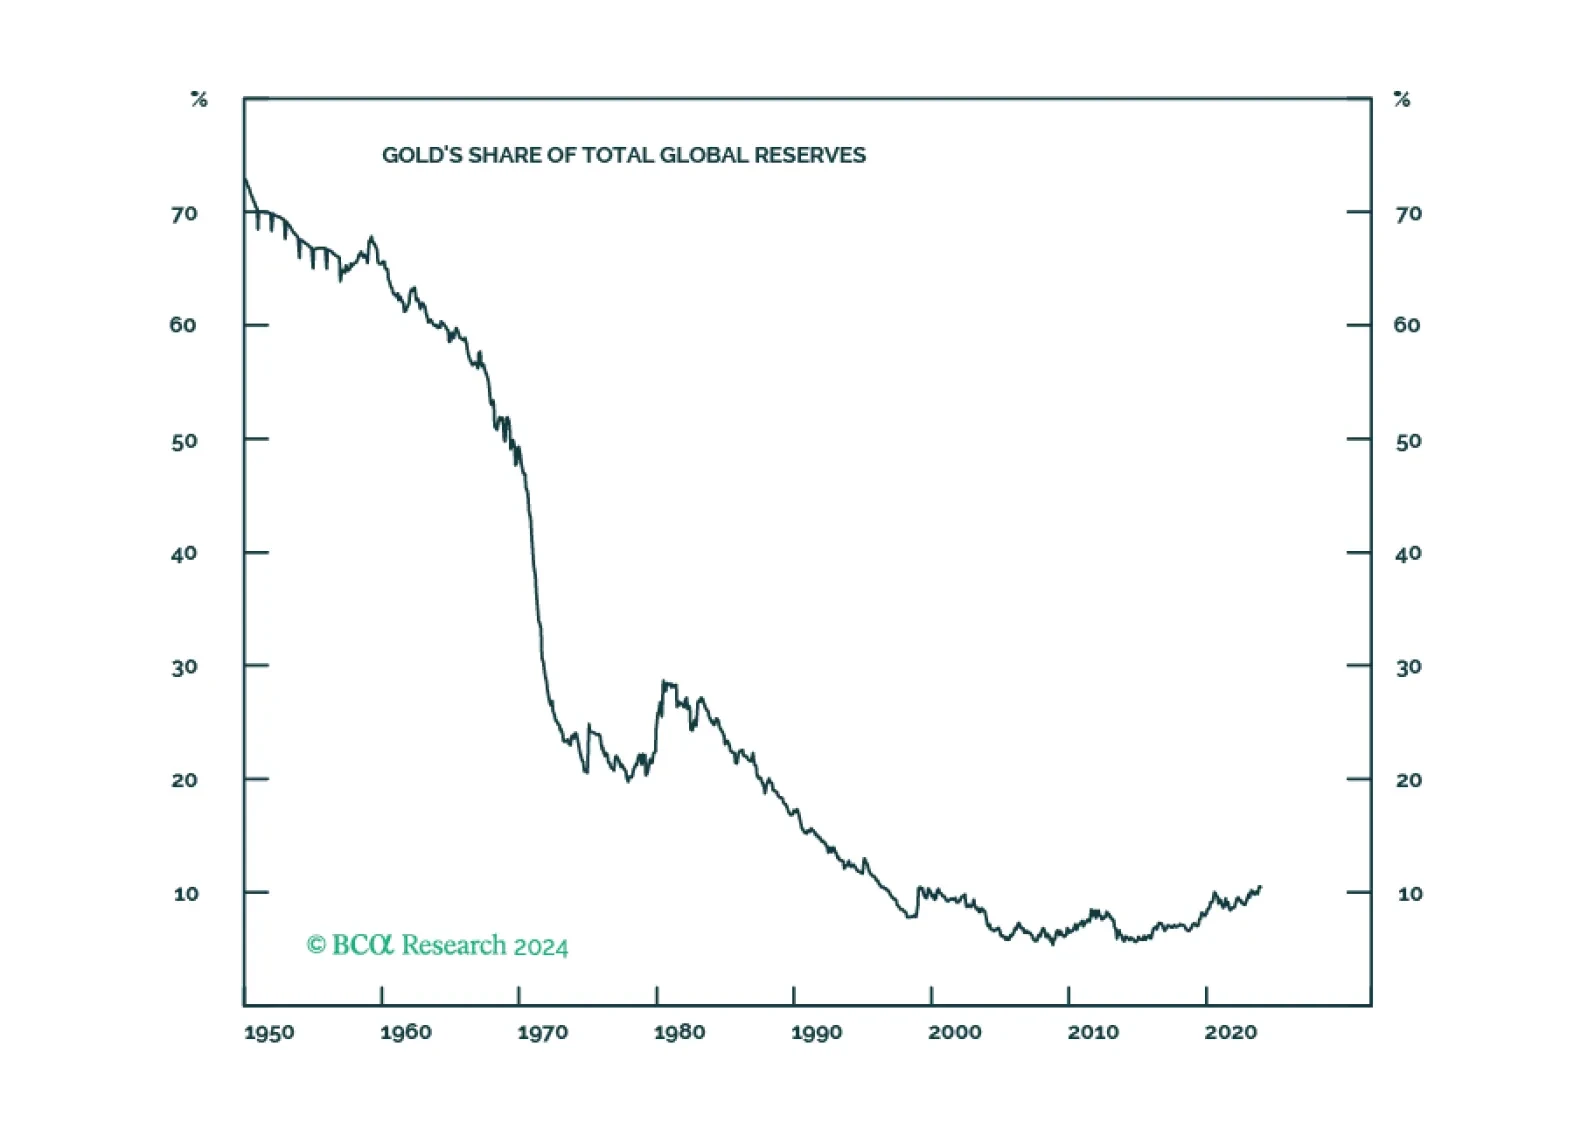
Our bullish gold, copper and oil calls have played out as expected, with gains of 14%, 11% and 16% since the beginning of the year. In this risk assessment of our views, we conclude the bull trends driving these markets higher remain intact. However, the risks of central-bank policy errors, resource nationalism and protectionism are rising. We are raising our gold and copper price targets to $2,500/oz (from $2,300/oz) and $5.00/lb (from $4.50/lb).
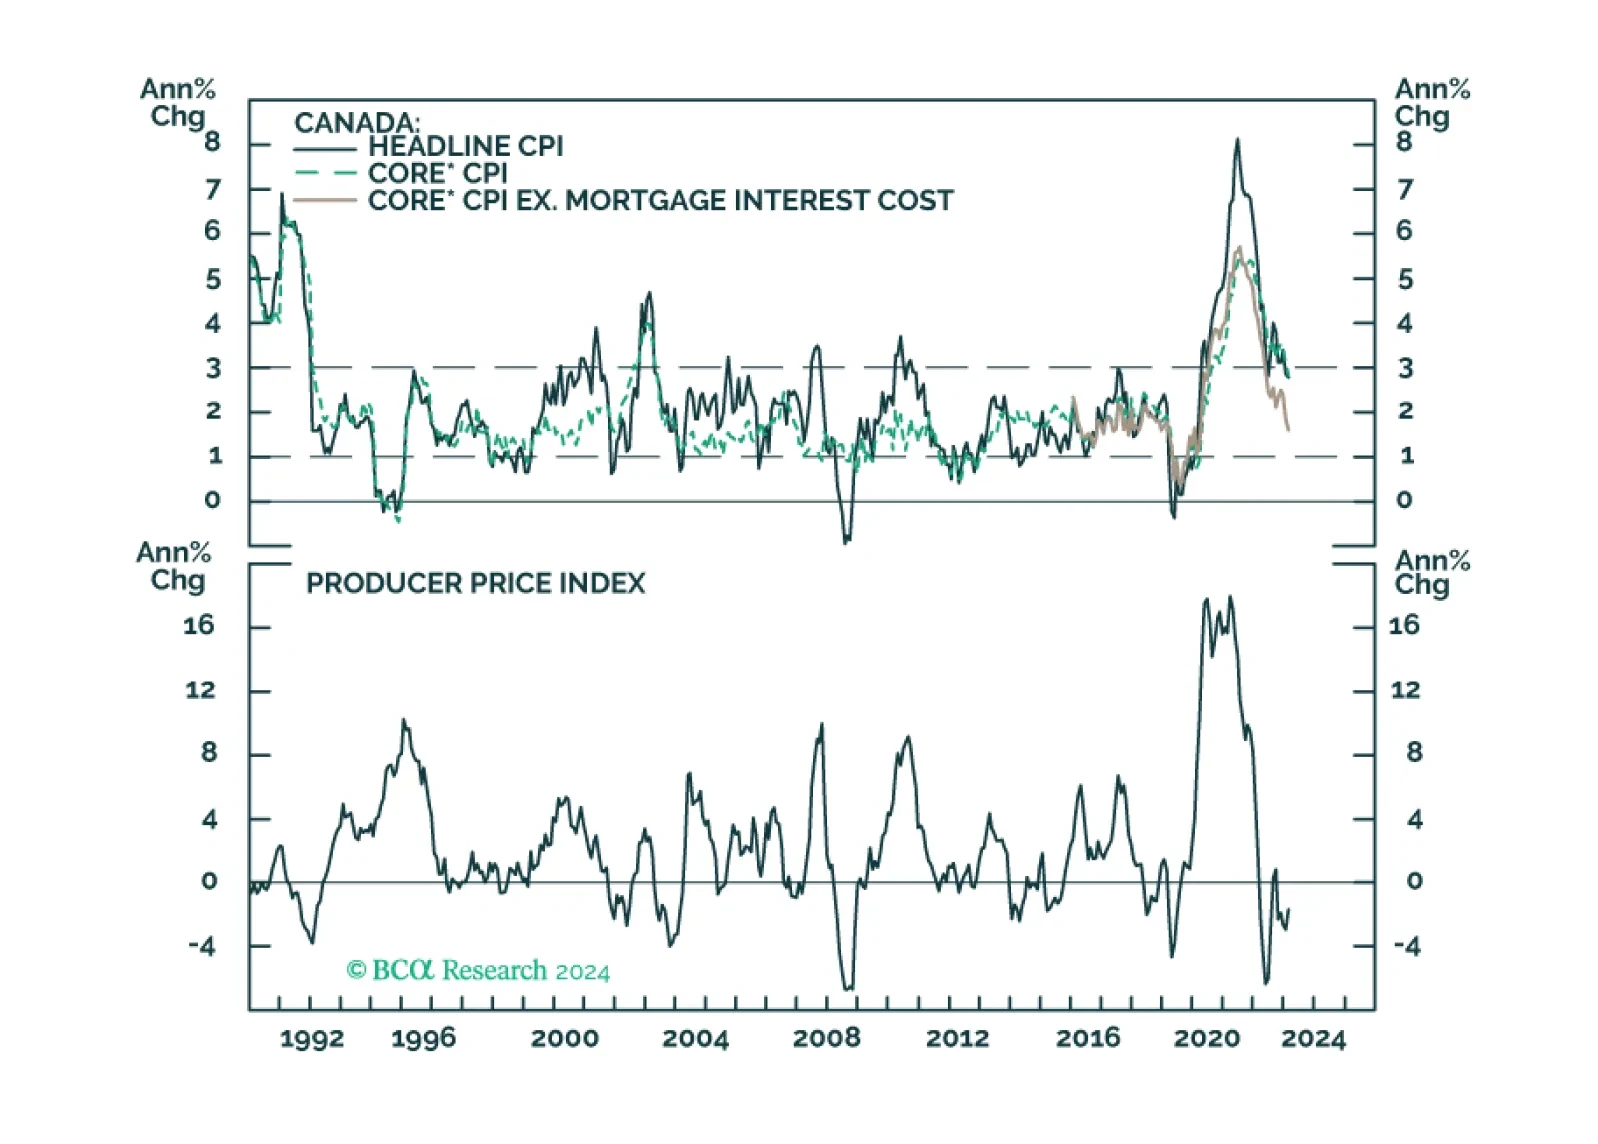
In this insight, we calibrate our investment views based on the latest Bank of Canada decision.
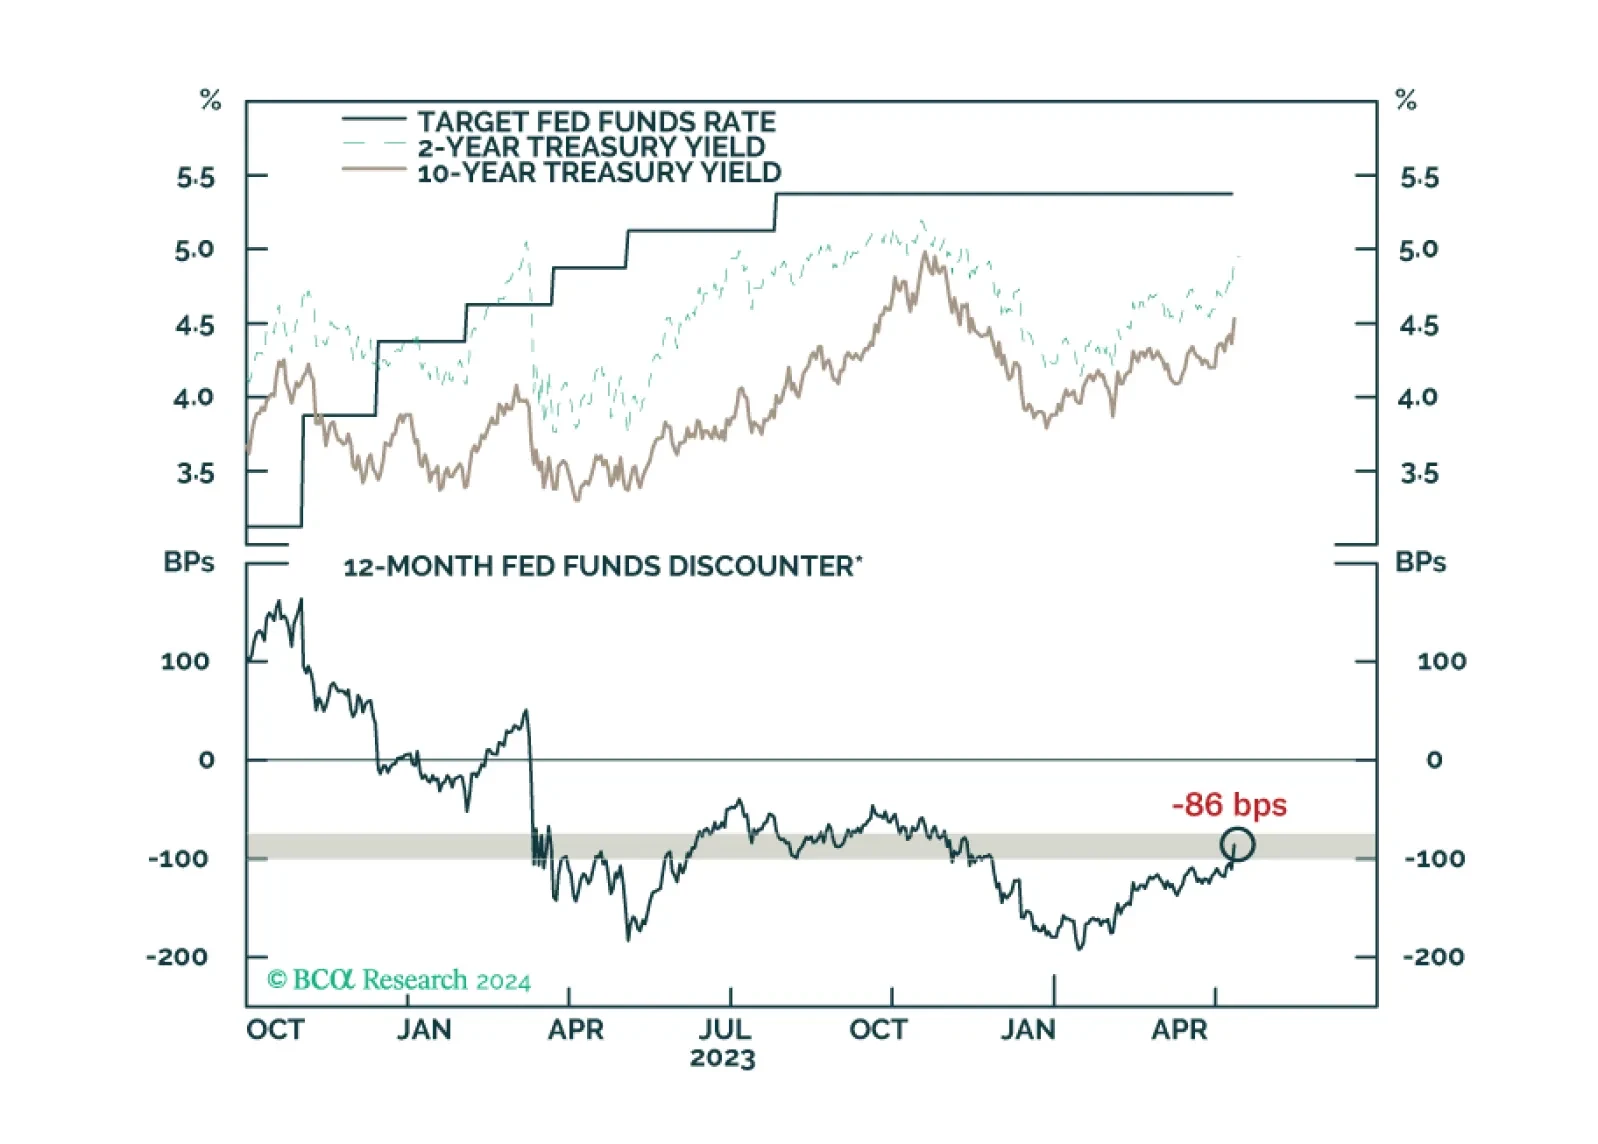
Our reaction to this morning’s CPI report and bond market moves.
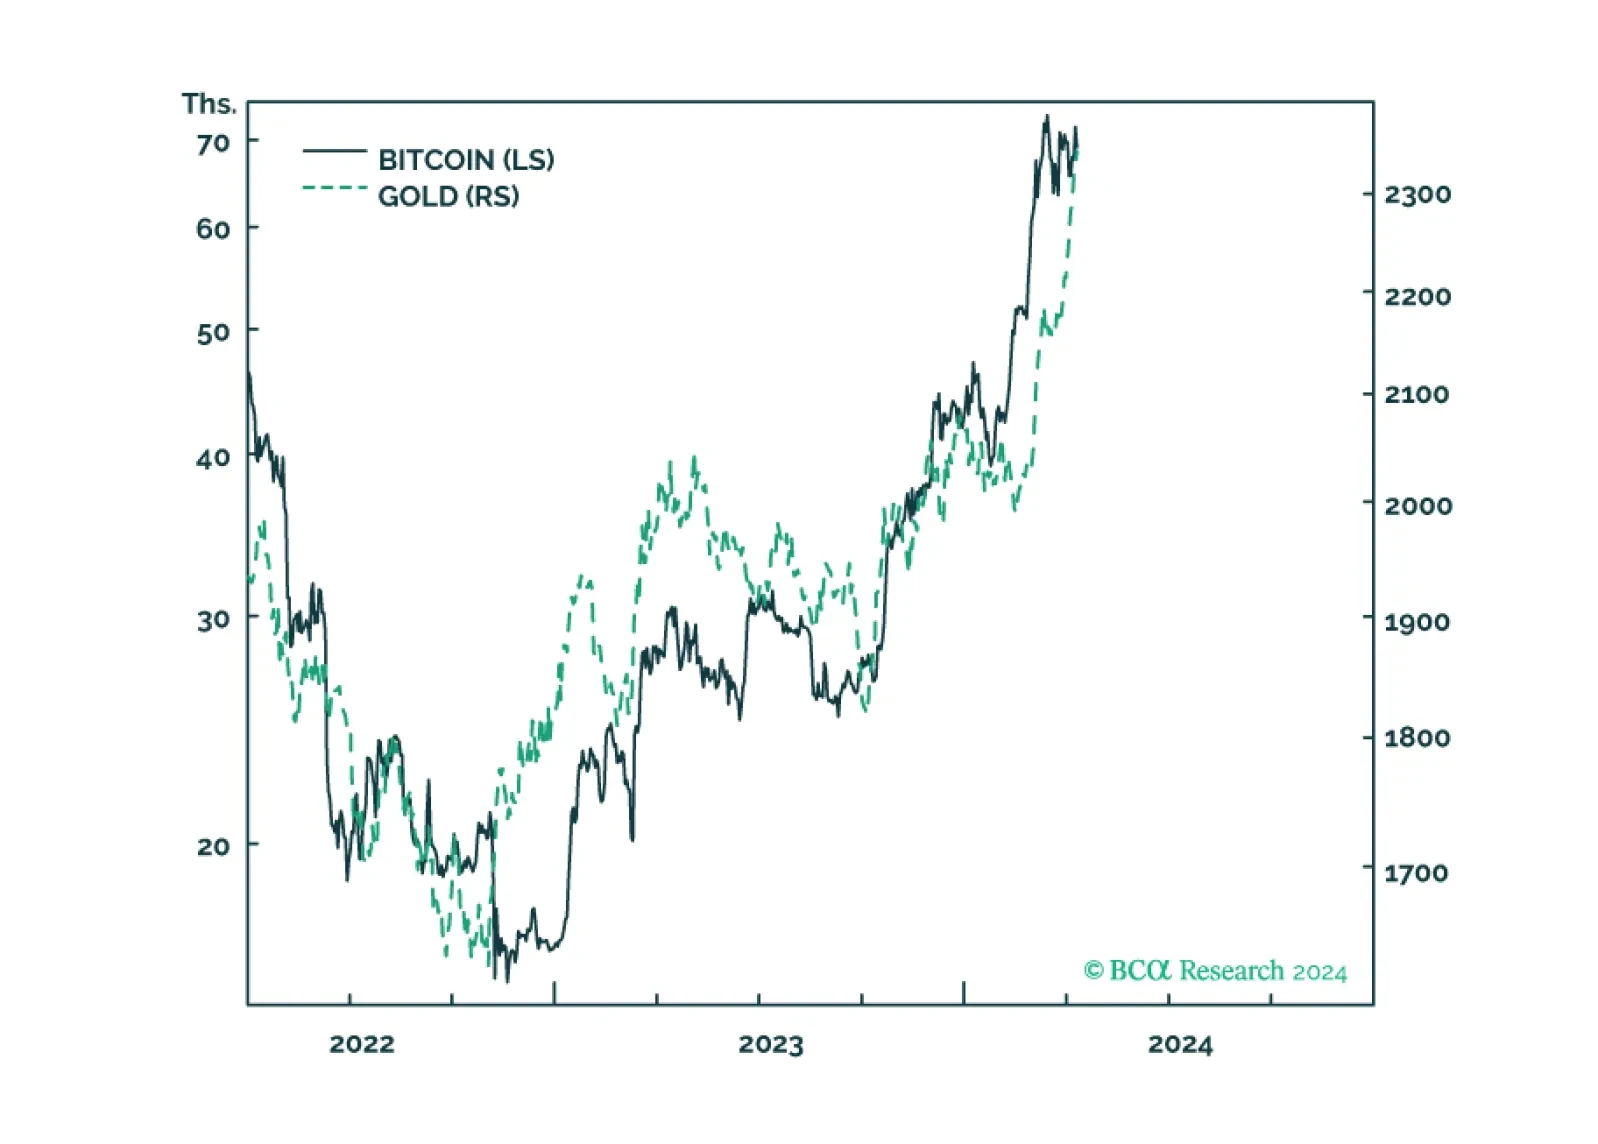
Gold and bitcoin are conceptually joined at the hip because the value of both comes from their ‘non-confiscatability’ by inflation, by bank failure, and in the case of bitcoin, by state expropriation. The sharp recent rallies in both gold and bitcoin reflect that the market has suddenly upped the value of non-confiscatability, and a plausible explanation is that recent US inflation data show that the journey to sustained 2 percent inflation has stalled, raising the risk that the Fed might balk at finishing the journey. Plus: JPM, CL, and USD/CHF are tactical reversal candidates.

Fears of a hard landing are abating as growth has been surprising to the upside. New worries are emerging, such as the trajectory of disinflation, and the pace and timing of rate cuts. In this environment, it is important to build a resilient all-weather portfolio, which protects against a correction, rising rates, or stubborn inflation but also has exposure to the AI theme.
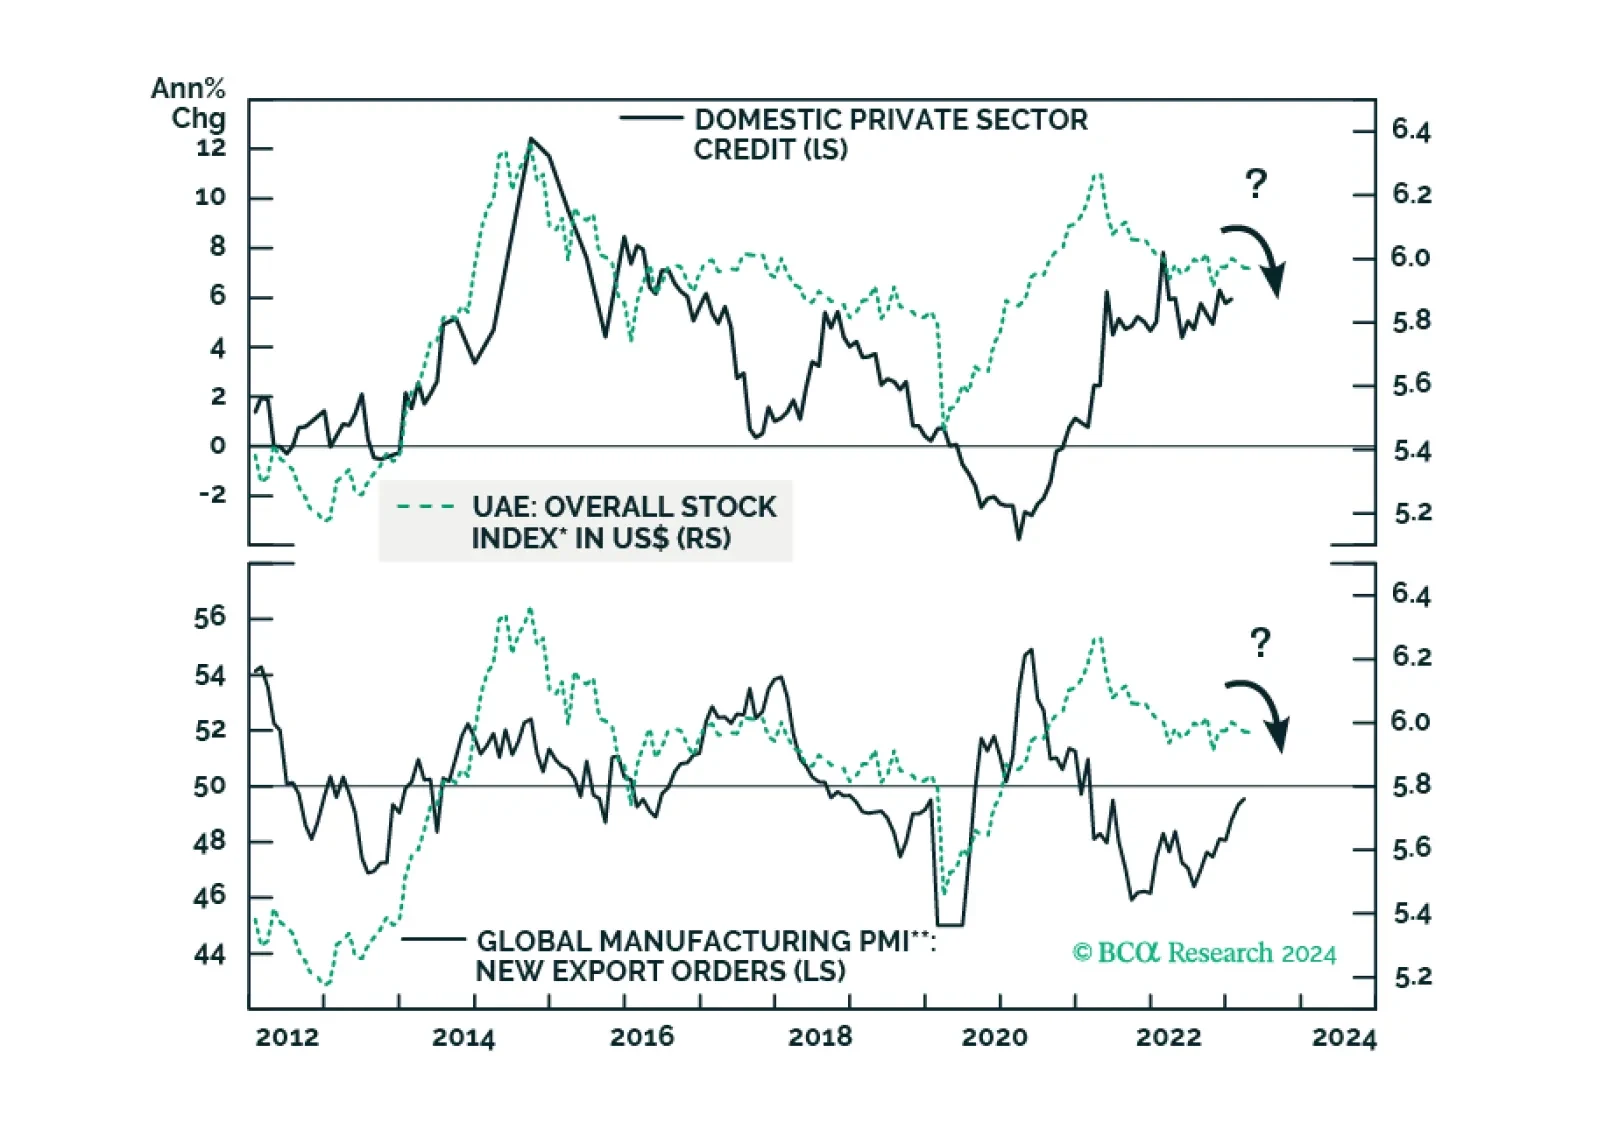
Subdued credit growth and weak global trade will remain headwinds for Emirati stocks. Surging property prices, which have led to a boom in real estate stocks, will also peak soon. Stay neutral on this bourse. Sovereign credit investors, however, should stay overweight UAE in EM credit portfolios.

Valuation metrics in Private Equity and Venture Capital vary widely by source, stage, location, and other factors. They are prone to imprecision, which is why investors should monitor a diverse set. This report offers a series of charts comparing valuation ratios. Focusing solely on valuations reveals that North America Middle Market Buyouts appear less attractive and geographical selection will be more important going forward.
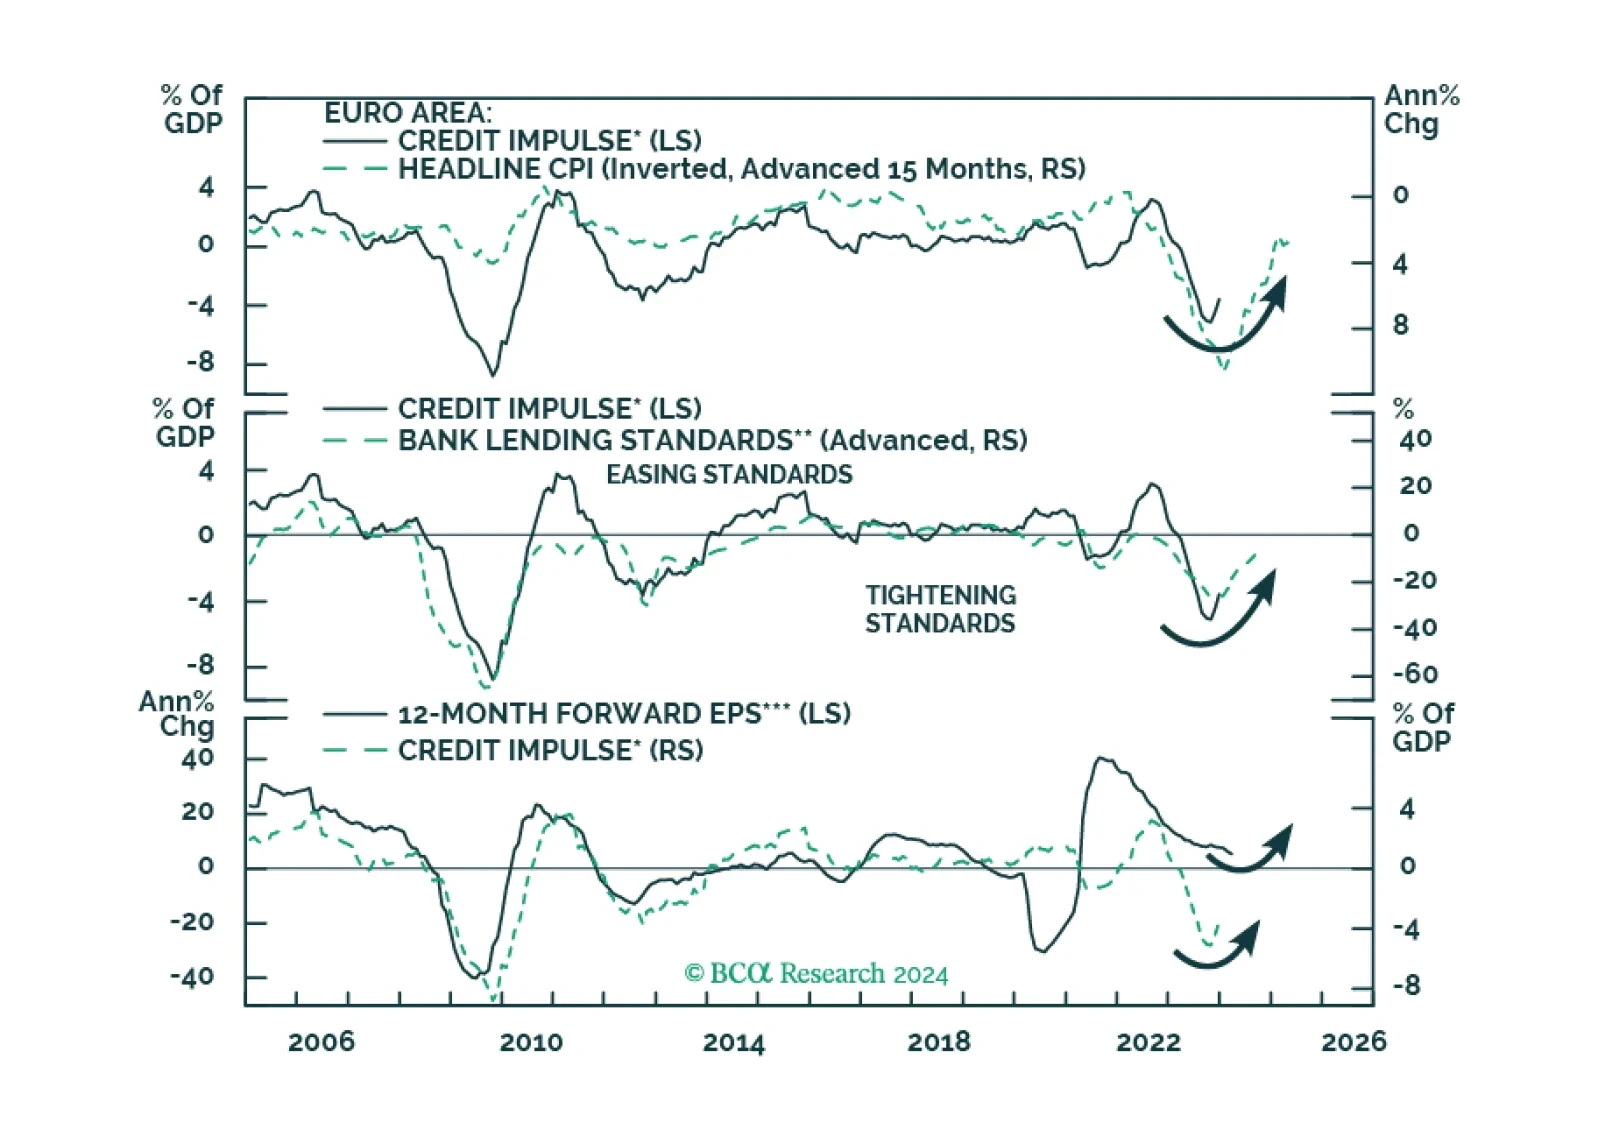
Europe credit flows are stabilizing, hence a major drag on the region’s growth will dissipate. What does this development imply for European equities?
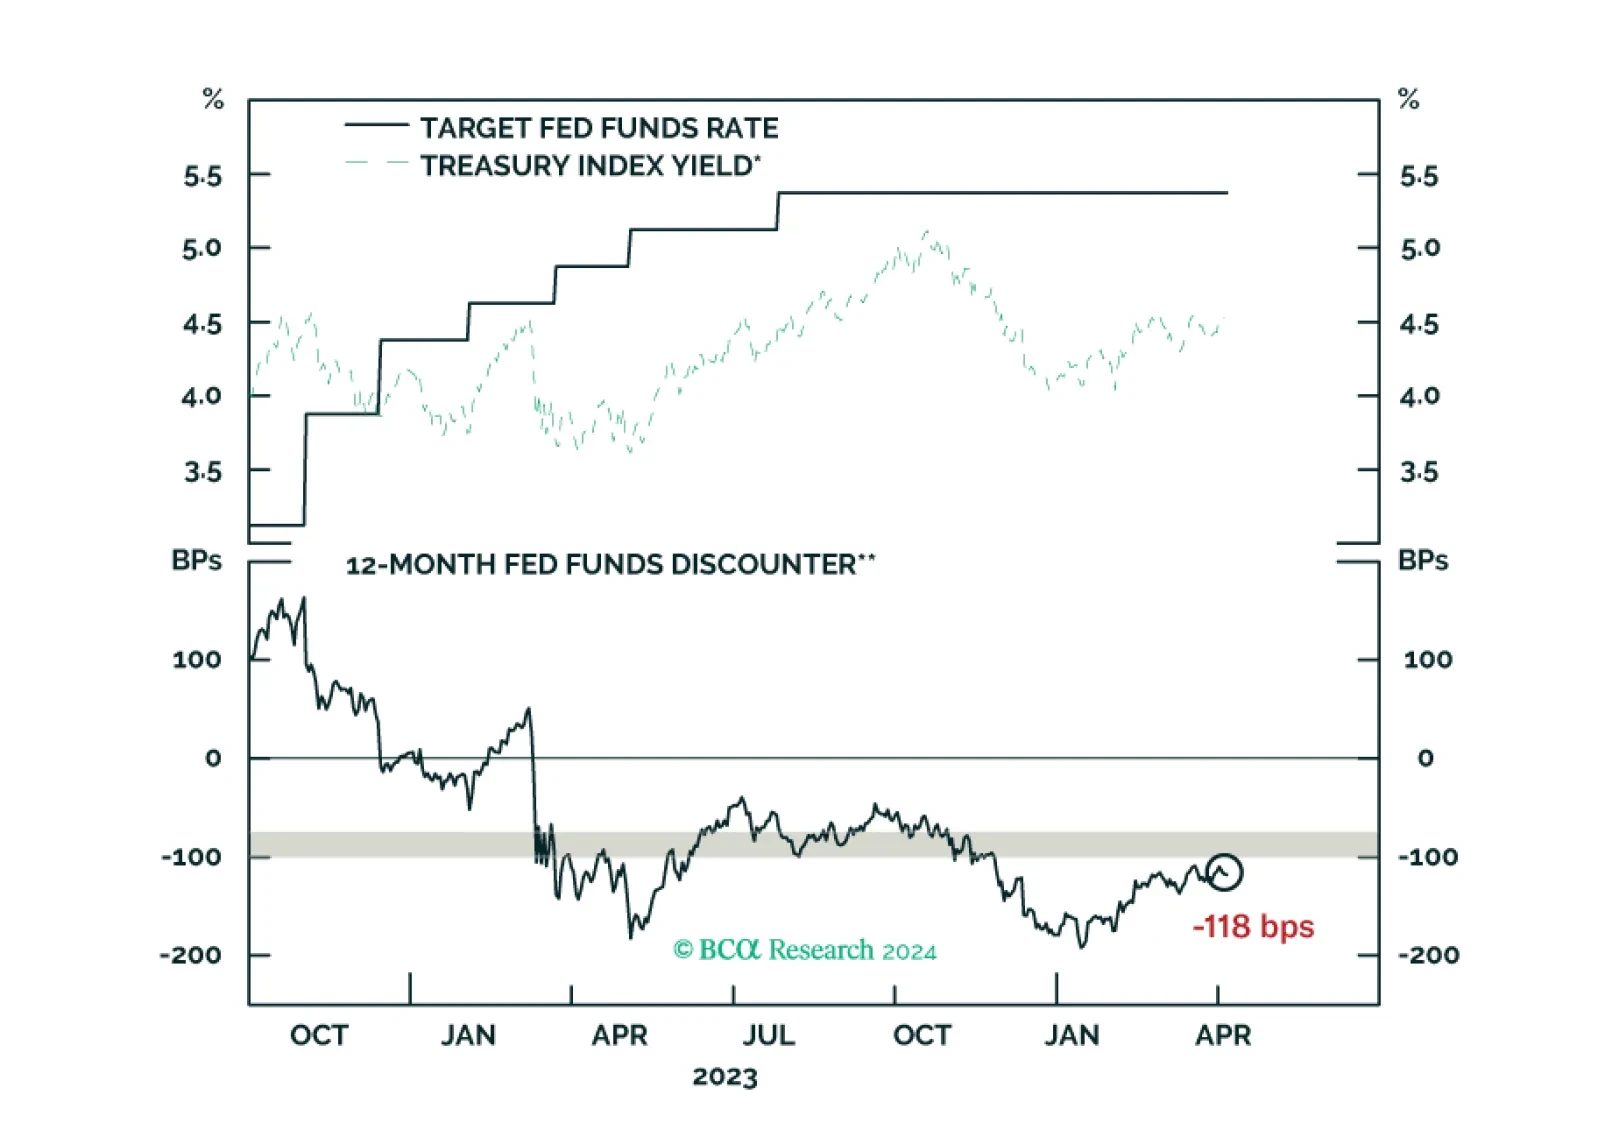
Our reaction to this morning’s employment report and bond market moves.