Skip to main content

Latest from BCA Research
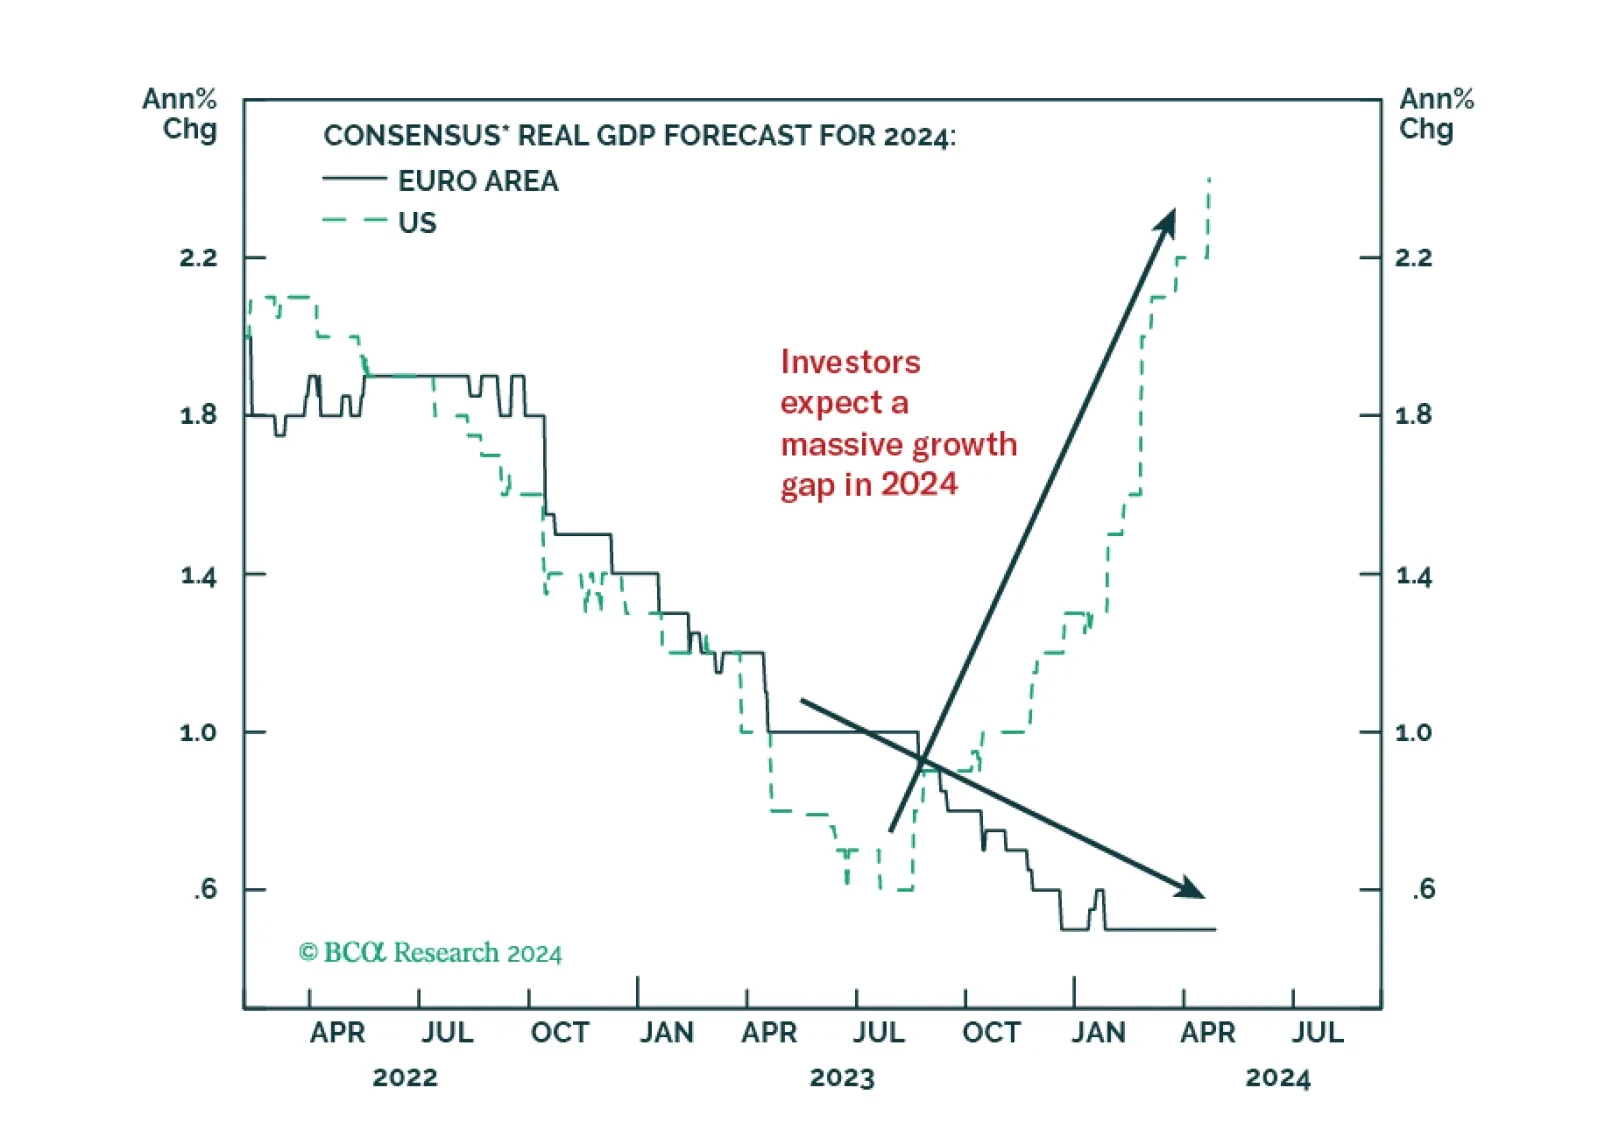
Investors anticipate a record growth gap between the US and the Eurozone in 2024. Does this skewed expectation create market opportunities?
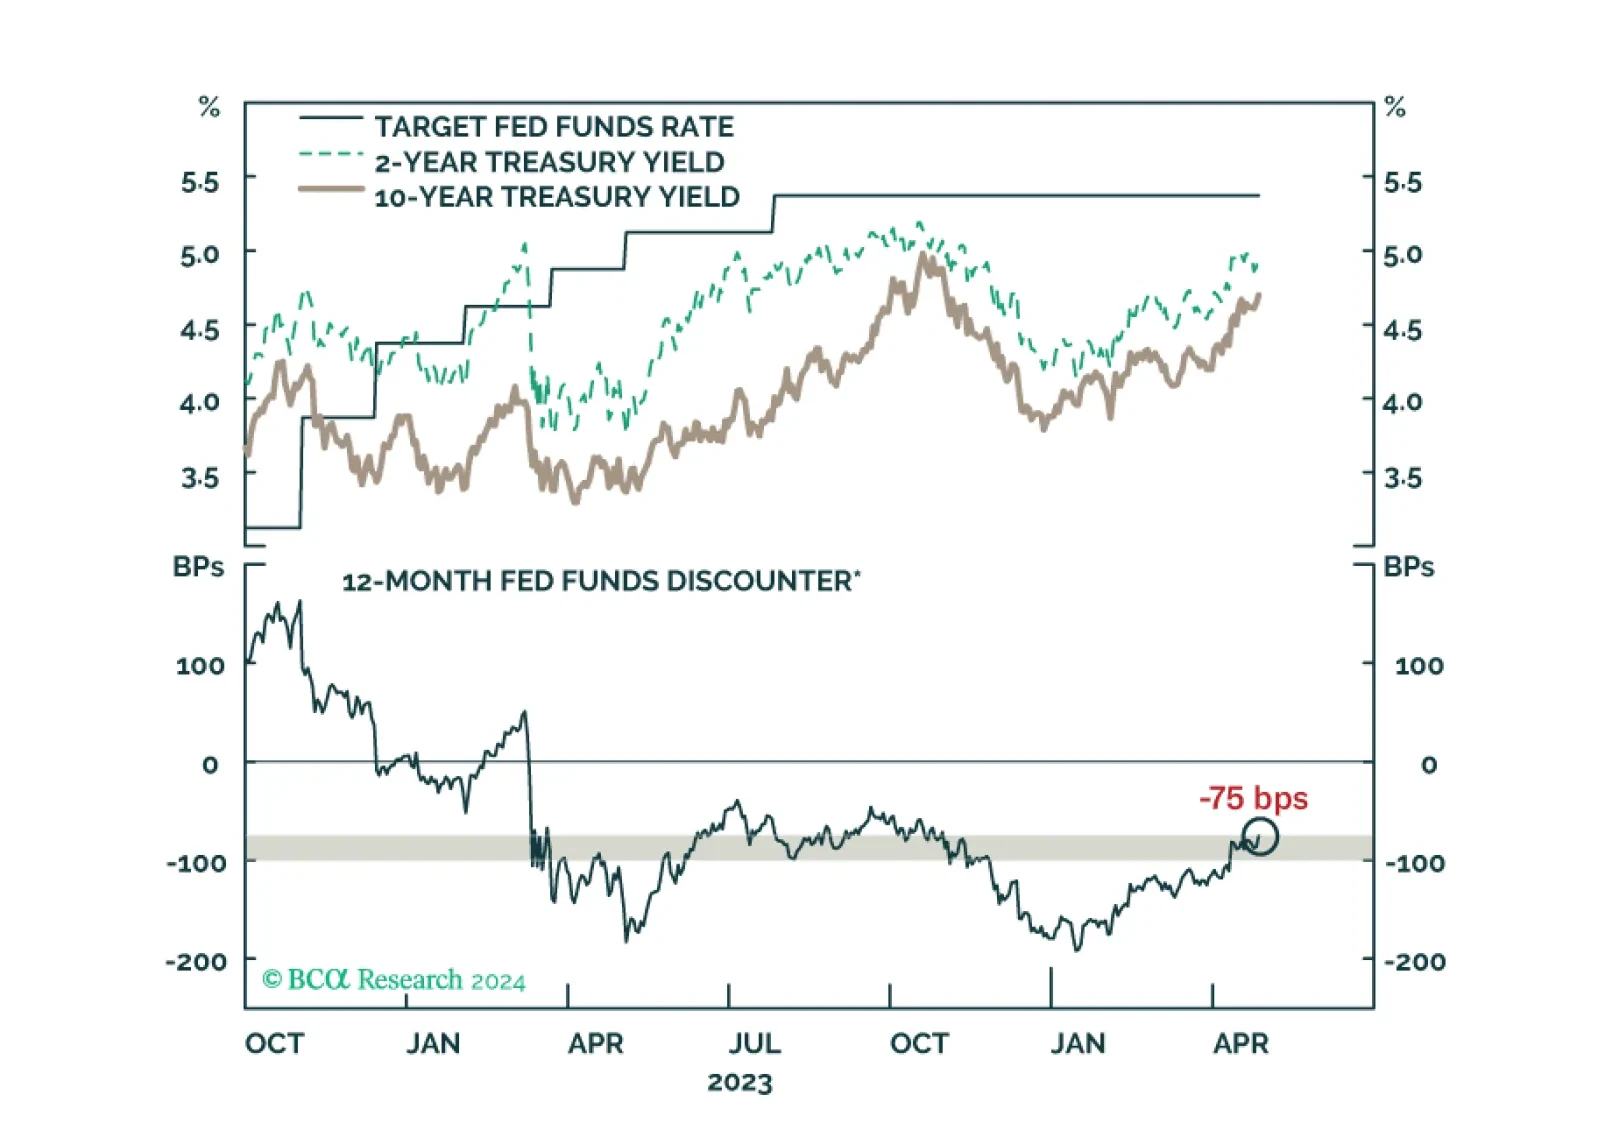
Our latest views on the recent increase in Treasury yields and some key things to watch at next week’s FOMC meeting.
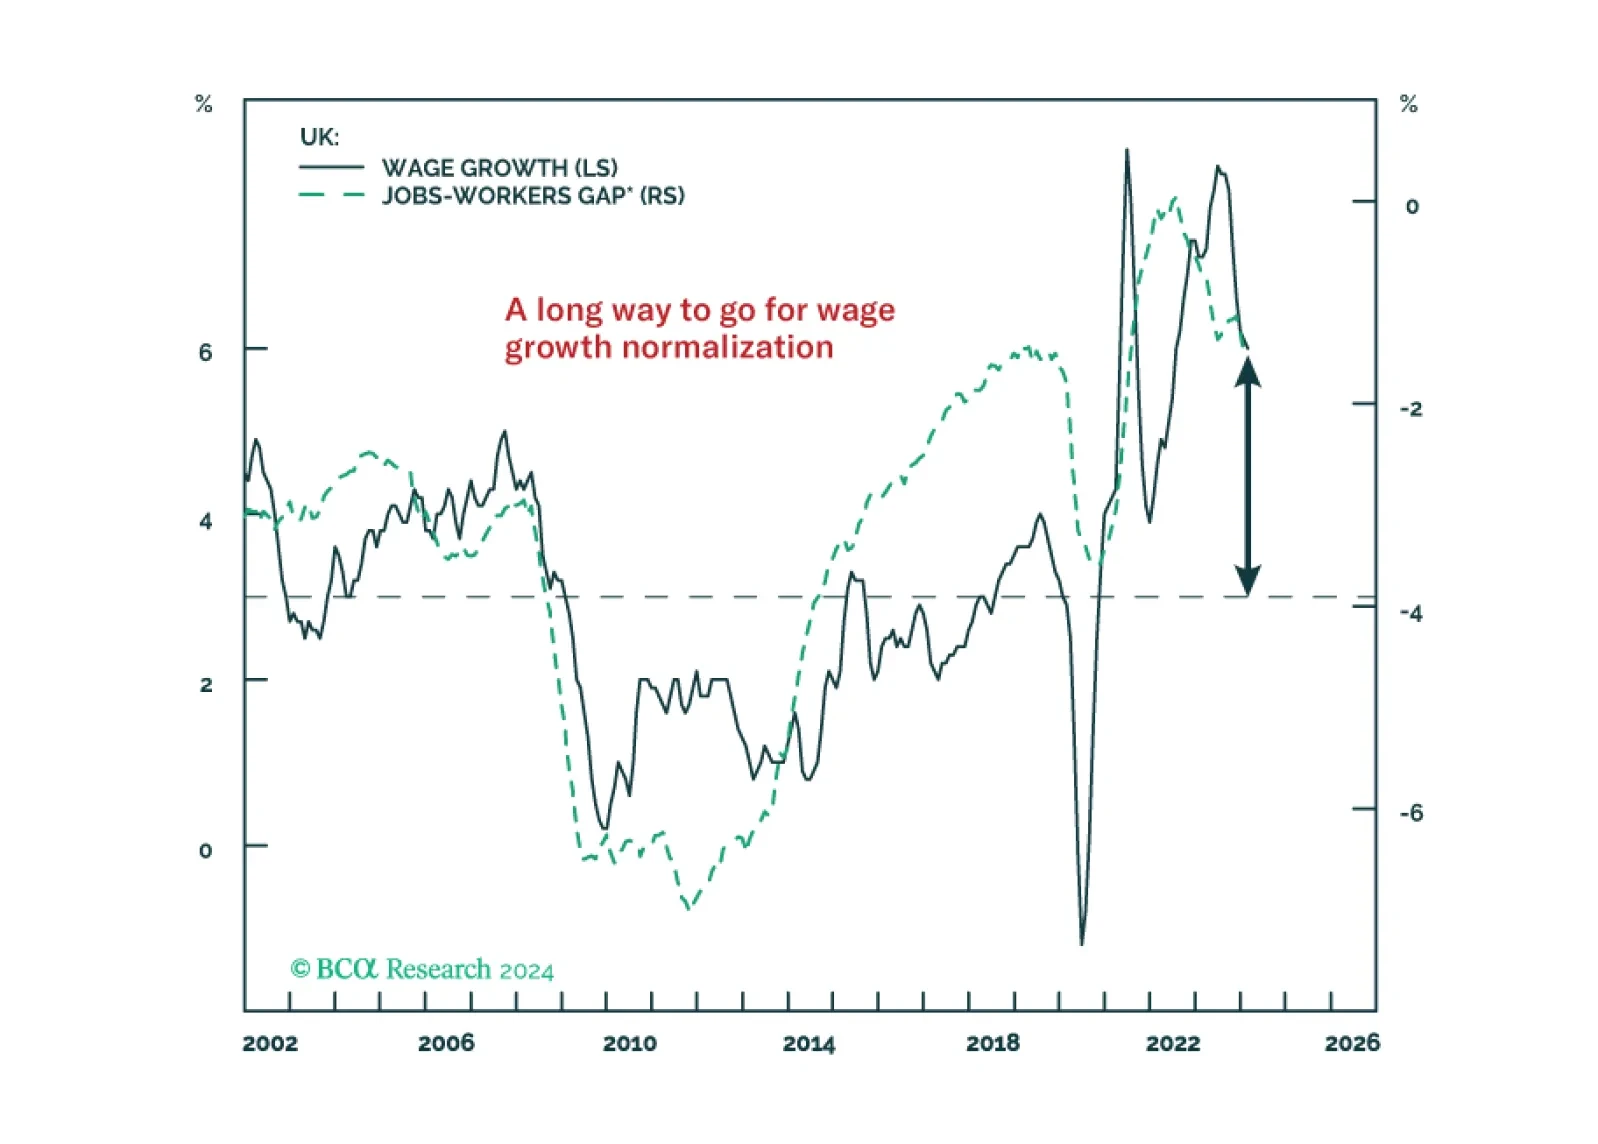
Special Report The UK labor market remains far too tight to expect wage growth to slow to levels consistent with the Bank of England inflation target. A true recession with rising unemployment is needed to finally slay the UK inflation beast. 2024 rate cuts are off the table, with the central bank having to keep monetary policy tighter for longer than markets expect and the UK economy now rebounding. We recommend downgrading UK gilts to underweight in global bond portfolios, while also looking for opportunities to buy the British pound on pullbacks versus the euro, Canadian dollar and Swedish krona.
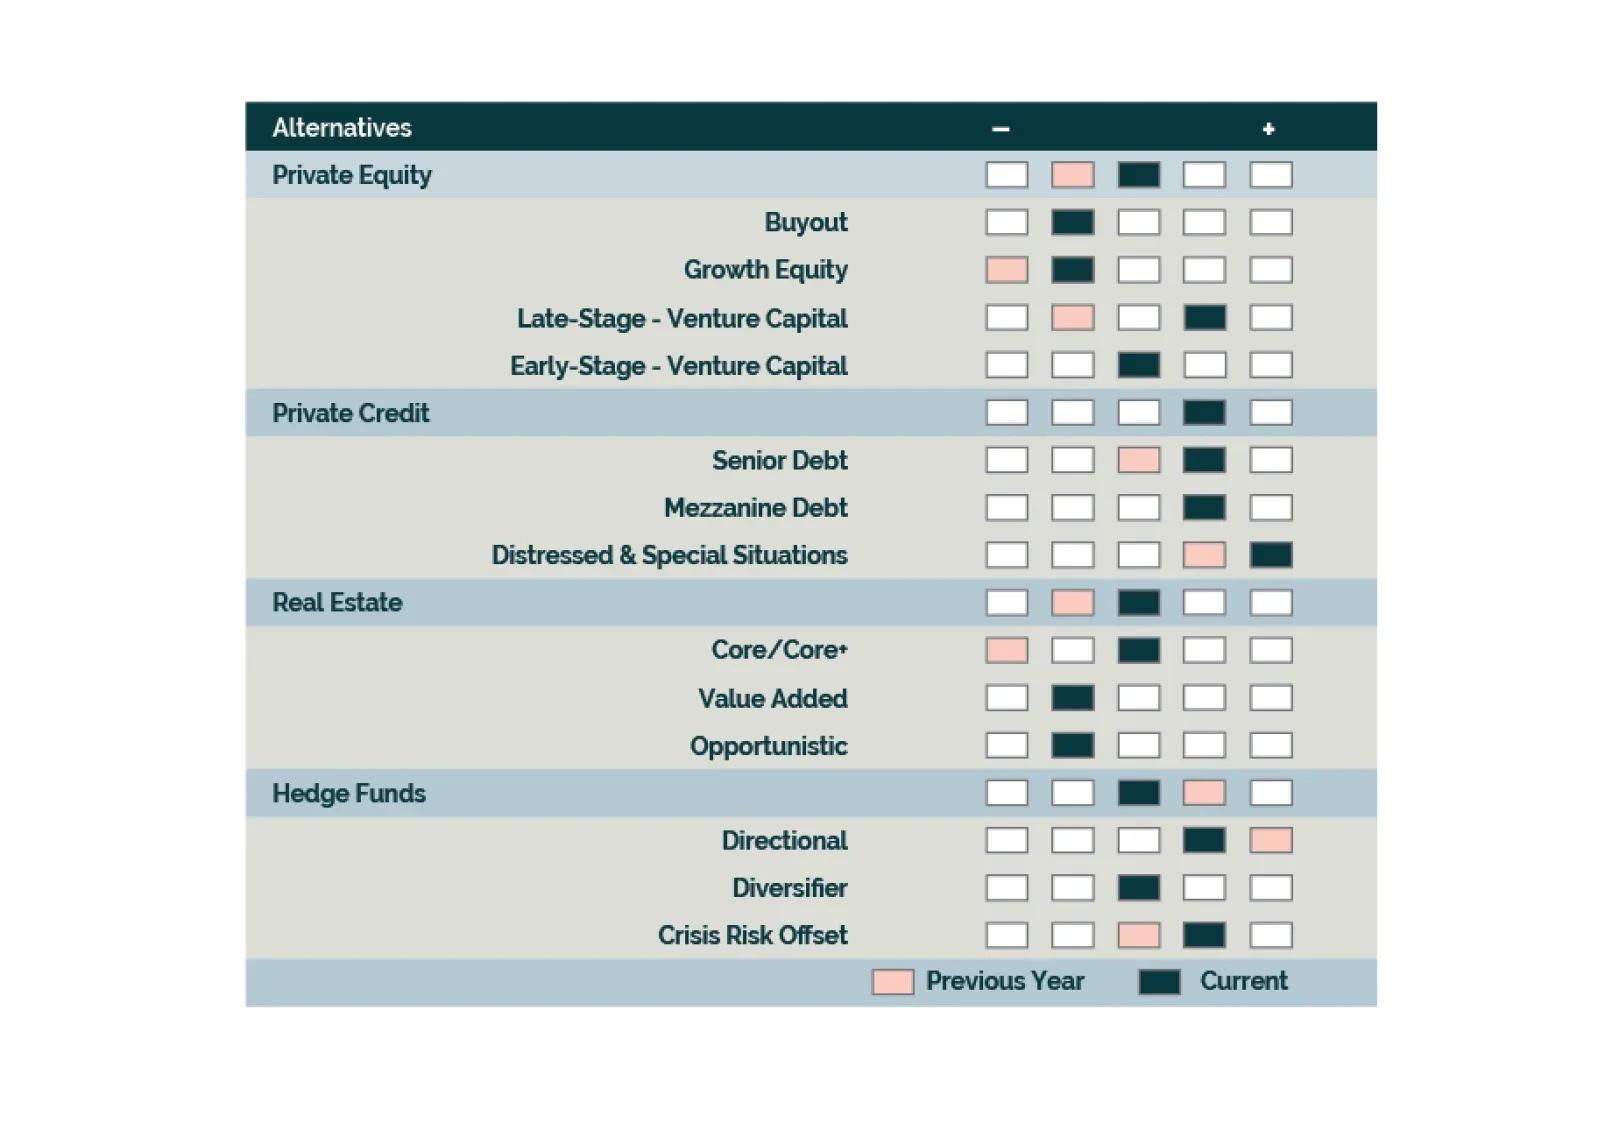
We go overweight Late-Stage Venture Capital and APAC Private Equity but remain underweight North America Buyouts. We maintain our neutral outlook towards Hedge Funds and are positive on Long-Short Equity, Event Driven, and CRO strategies. We are cooling towards Direct Lending strategies as competition and relative opportunities increase. CRE’s downturn continues to unfold; we are starting to be buyers.
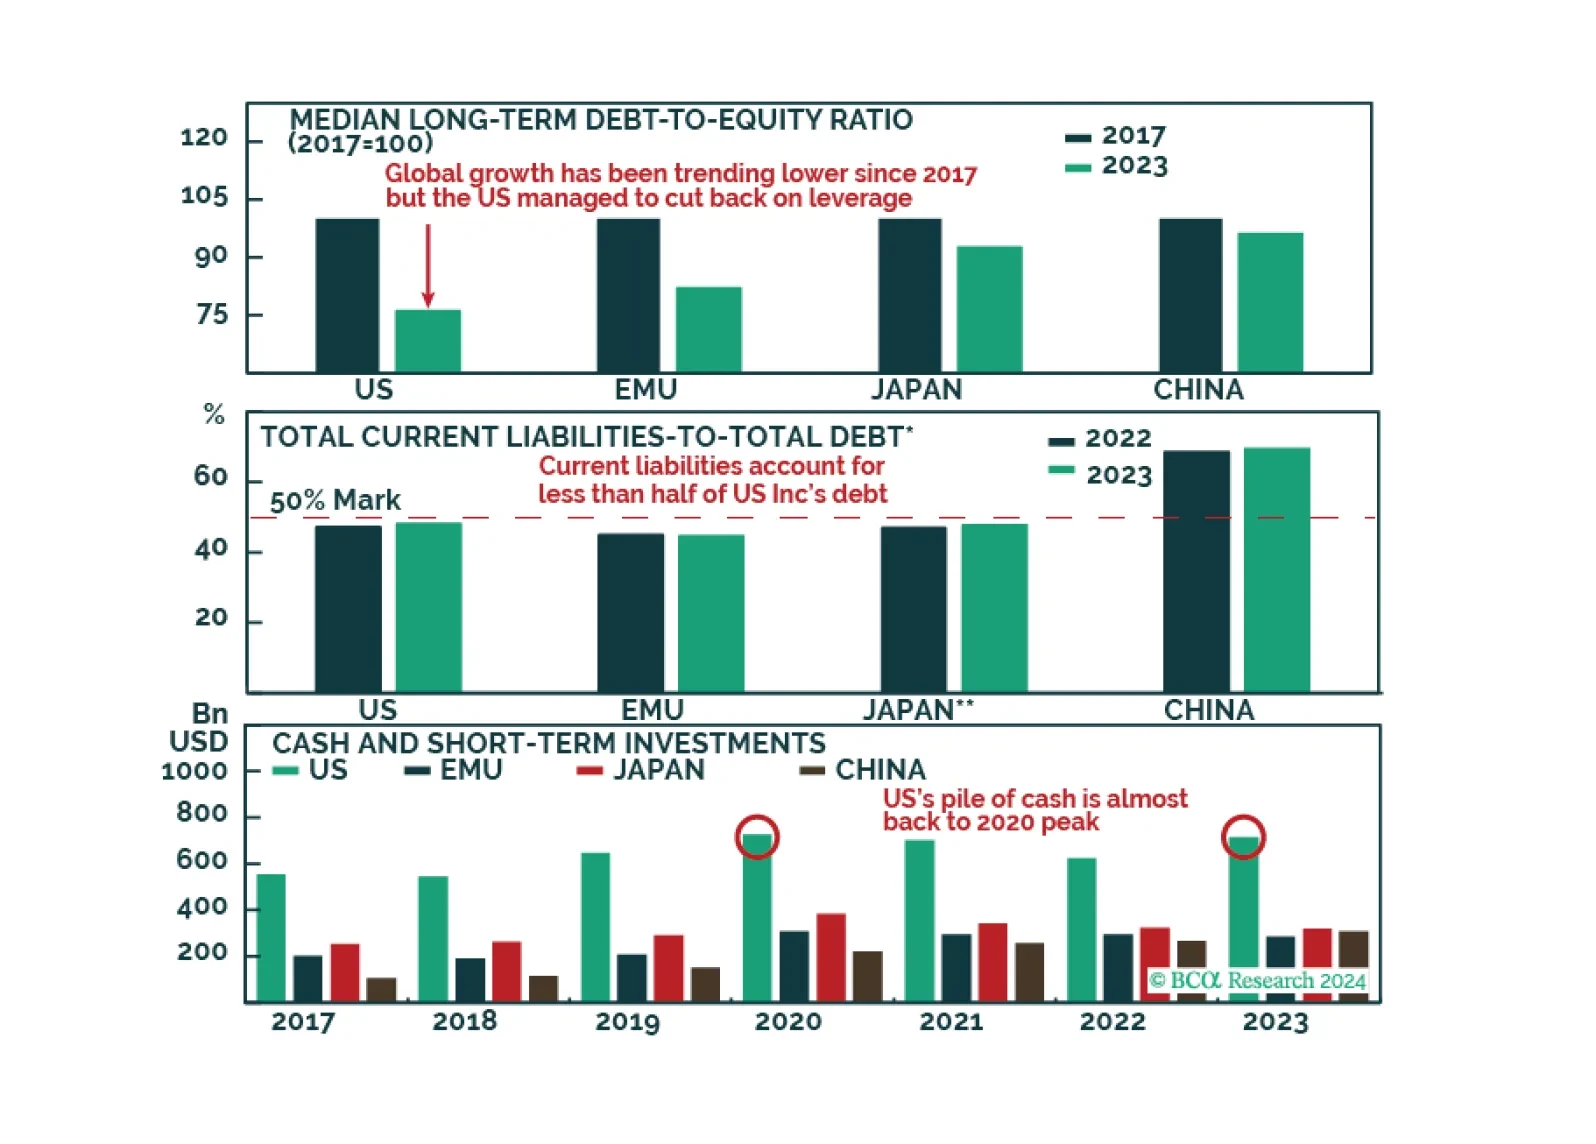
Special Report A deep dive into the balance sheets of top listed firms around the world suggests that corporate health differs substantially across key equity markets. To profit from these differences when the next recession arrives, we recommend that equity investors favor the US and Japan, be neutral on Europe while being wary of China for a range of compelling reasons.
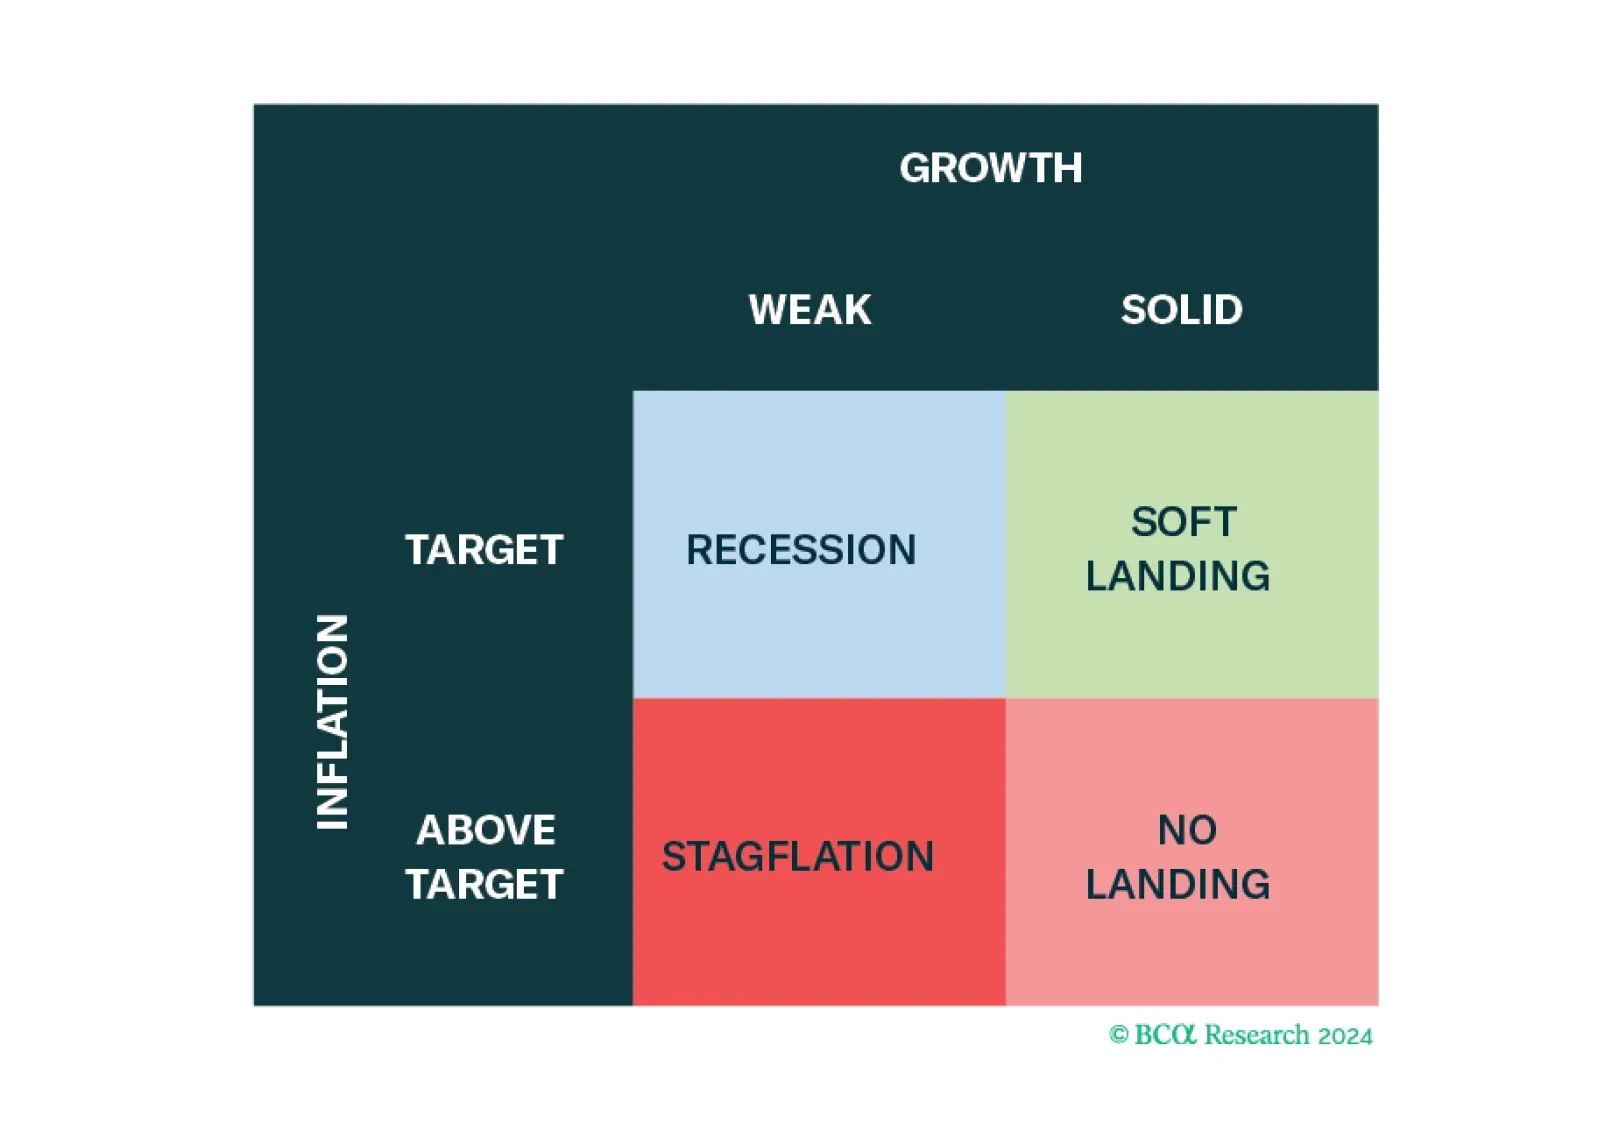
Bank Credit Analyst In a guest authorship of Section I, Doug Peta addresses the recession skepticism often raised by investors. Excess savings are nearly or already drained, labor market indicators remain consistent with an eventual contraction in payroll growth, and there are no signs that credit growth will keep consumer spending afloat. Additionally, this month’s Section II is a guest piece written by Ritika Mankar of BCA’s Global Investment Strategy service. Ritika checks in on the balance sheet health of large, global, listed nonfinancial firms. Firms in the US and Japan appear to be the most resilient in advance of a coming recession, followed by Europe. Chinese firms are the least resilient from a balance sheet perspective.
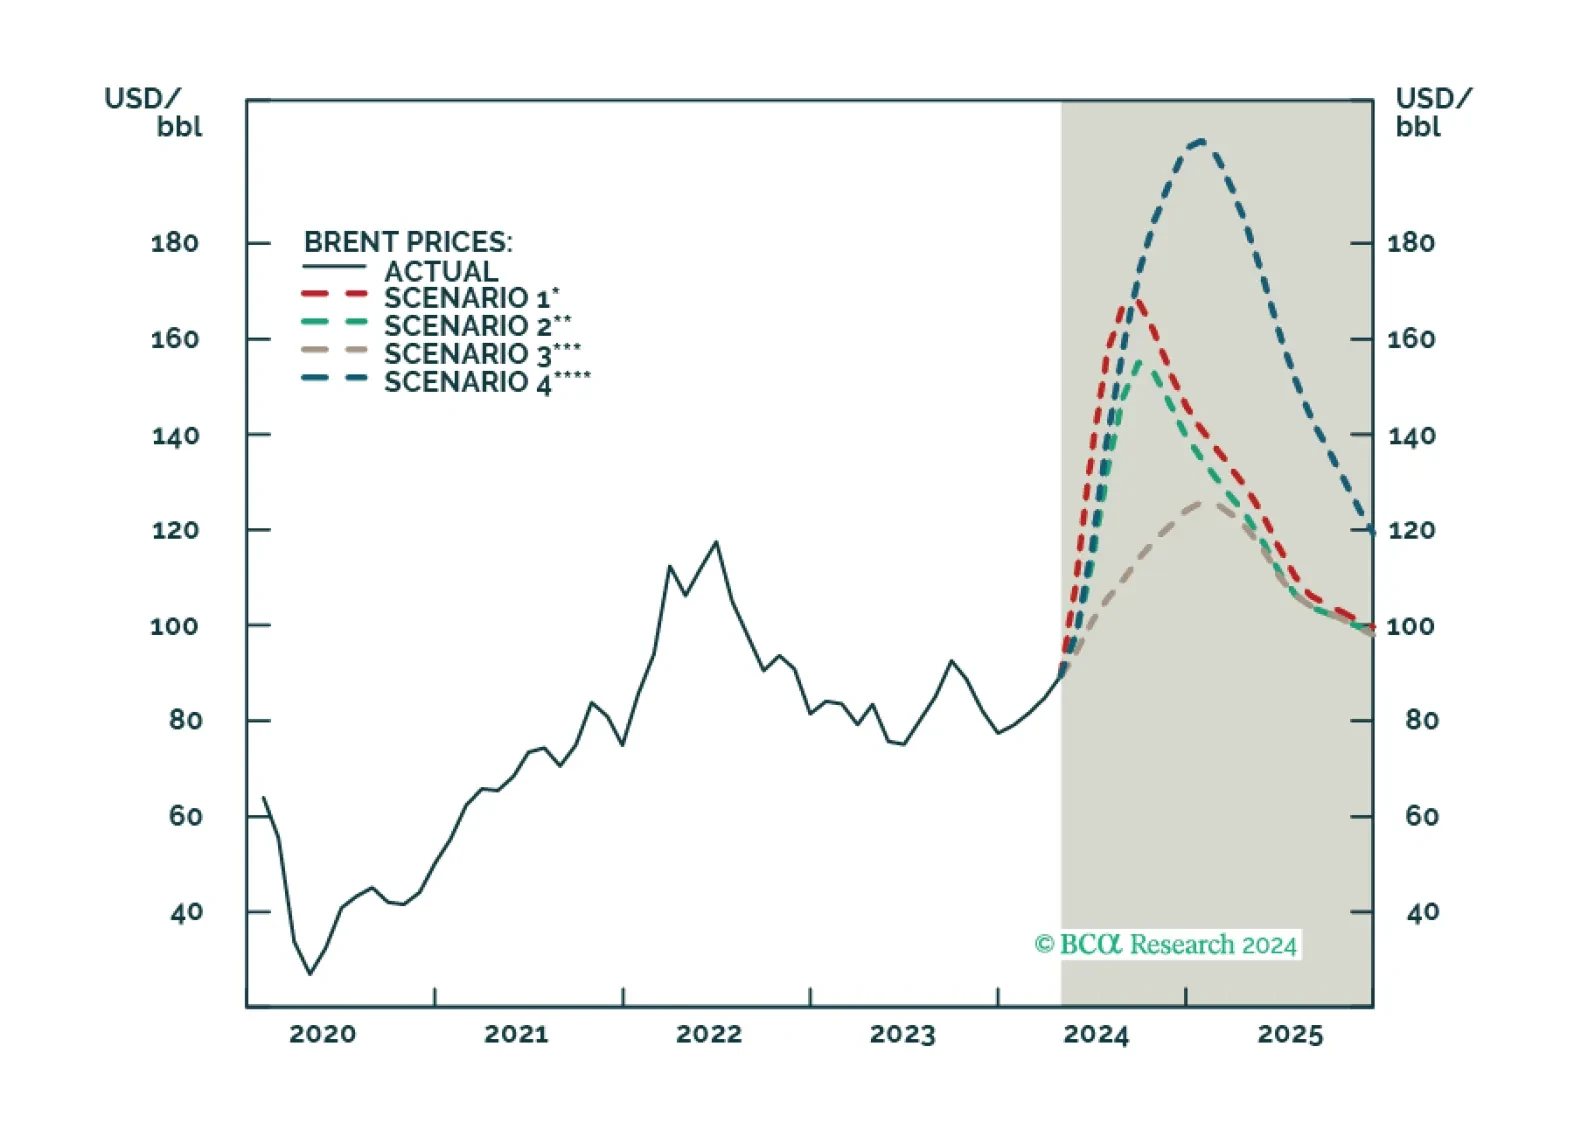
Special Report Investors should not underrate the chance of an oil shock ahead of the US election as Israel needs to push back against Iranian proxies, and Iran needs to demonstrate its regional reach to put a wedge between Israel and the US. We remain strategically long energy commodities and equities, and defense stocks via the COMT, XOP and PPA ETFs, which will continue to outperform cyclicals.
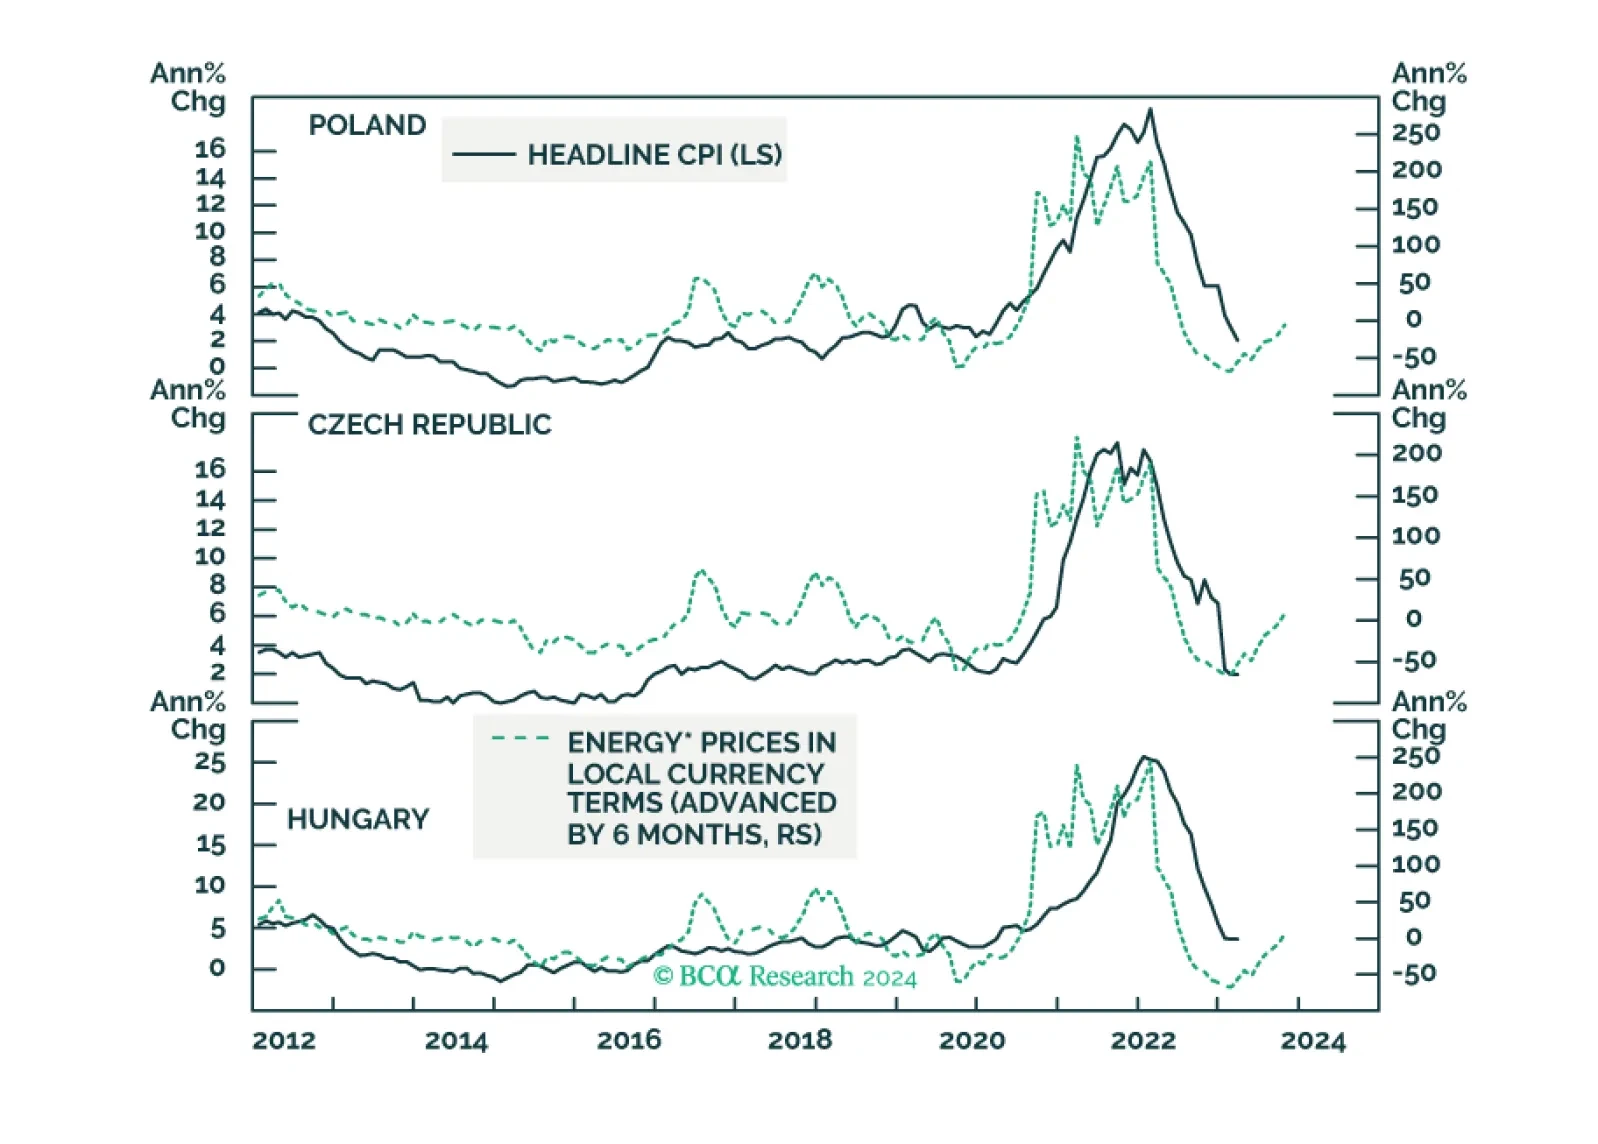
The disinflation process is over in Poland and Hungary. Only the Czech Republic will see its core inflation meet its central bank target this year. The reason is much tighter labor market dynamics in the first two. Investors should continue to short a basket of CE3 currencies vis-à-vis the US dollar.
China’s economy is cruising at a very low altitude. The odds are that China’s equity rebound is running out of time. The RMB will continue to depreciate versus the US dollar in the coming months, albeit the pace may be modest.