Latest from BCA Research
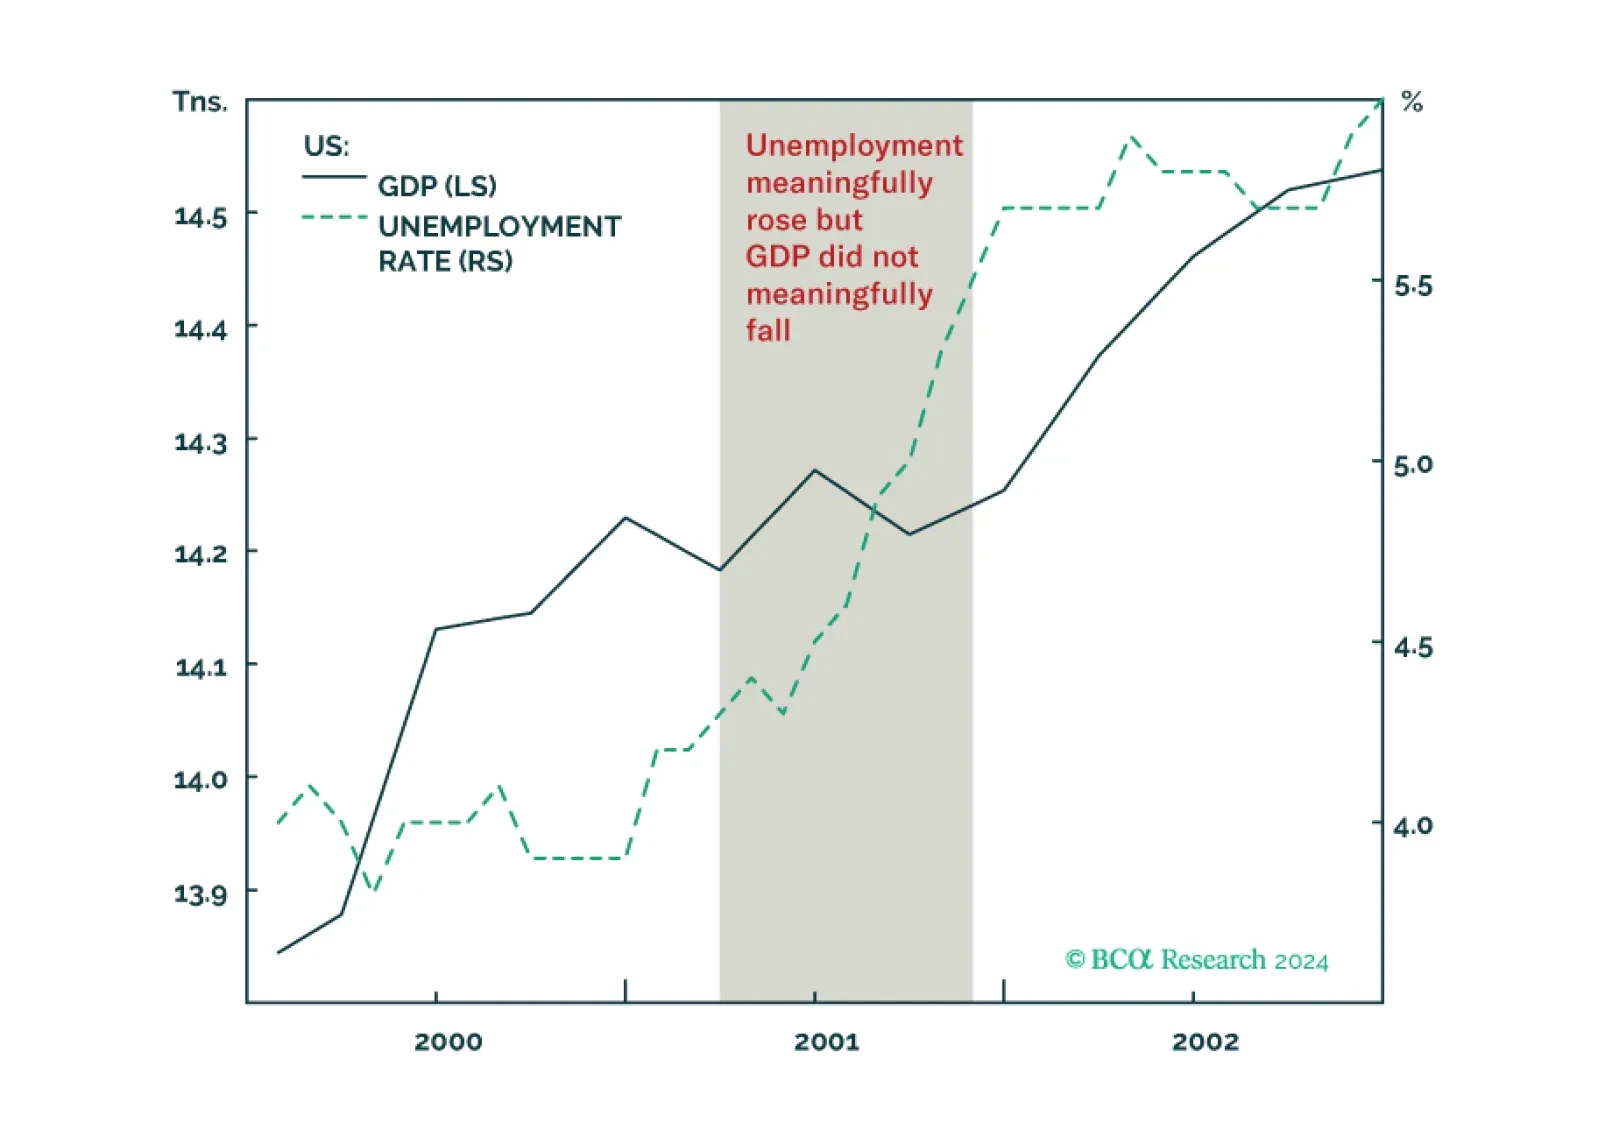
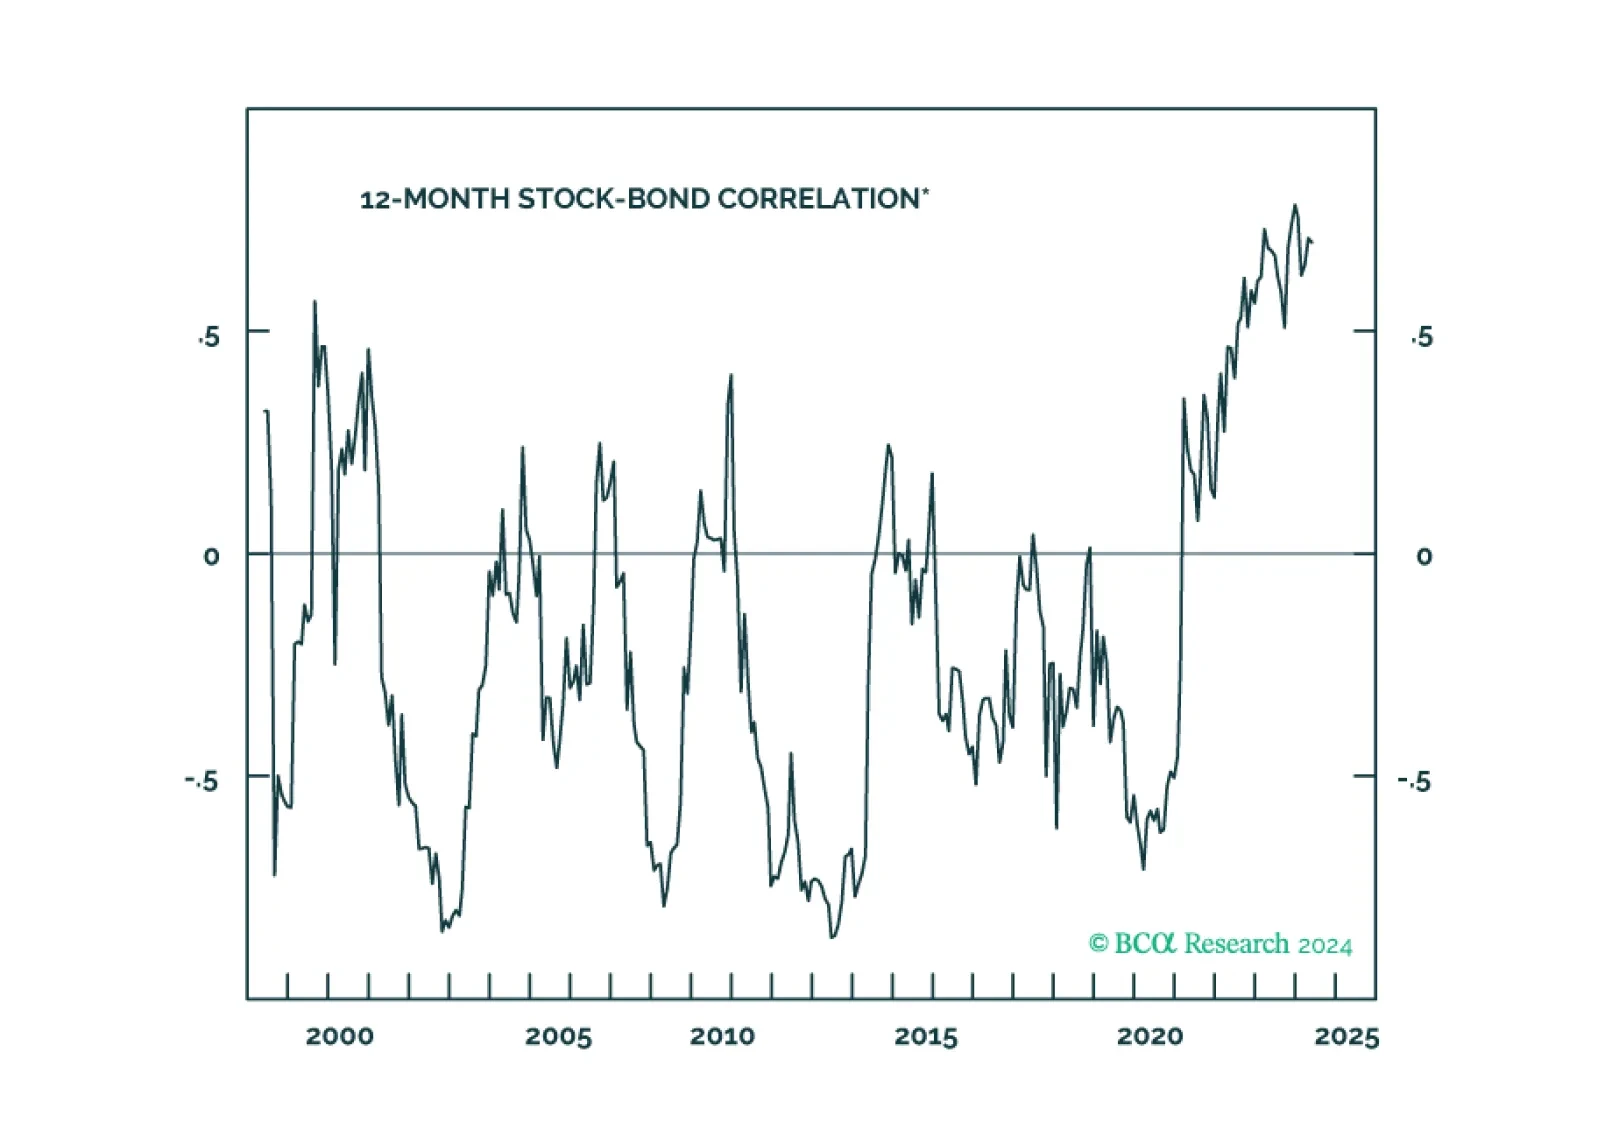
Why the US could get a jobs recession without a GDP recession, as happened in 2001, and what it means for stocks and bonds. Plus, an update on the Joshi rule.
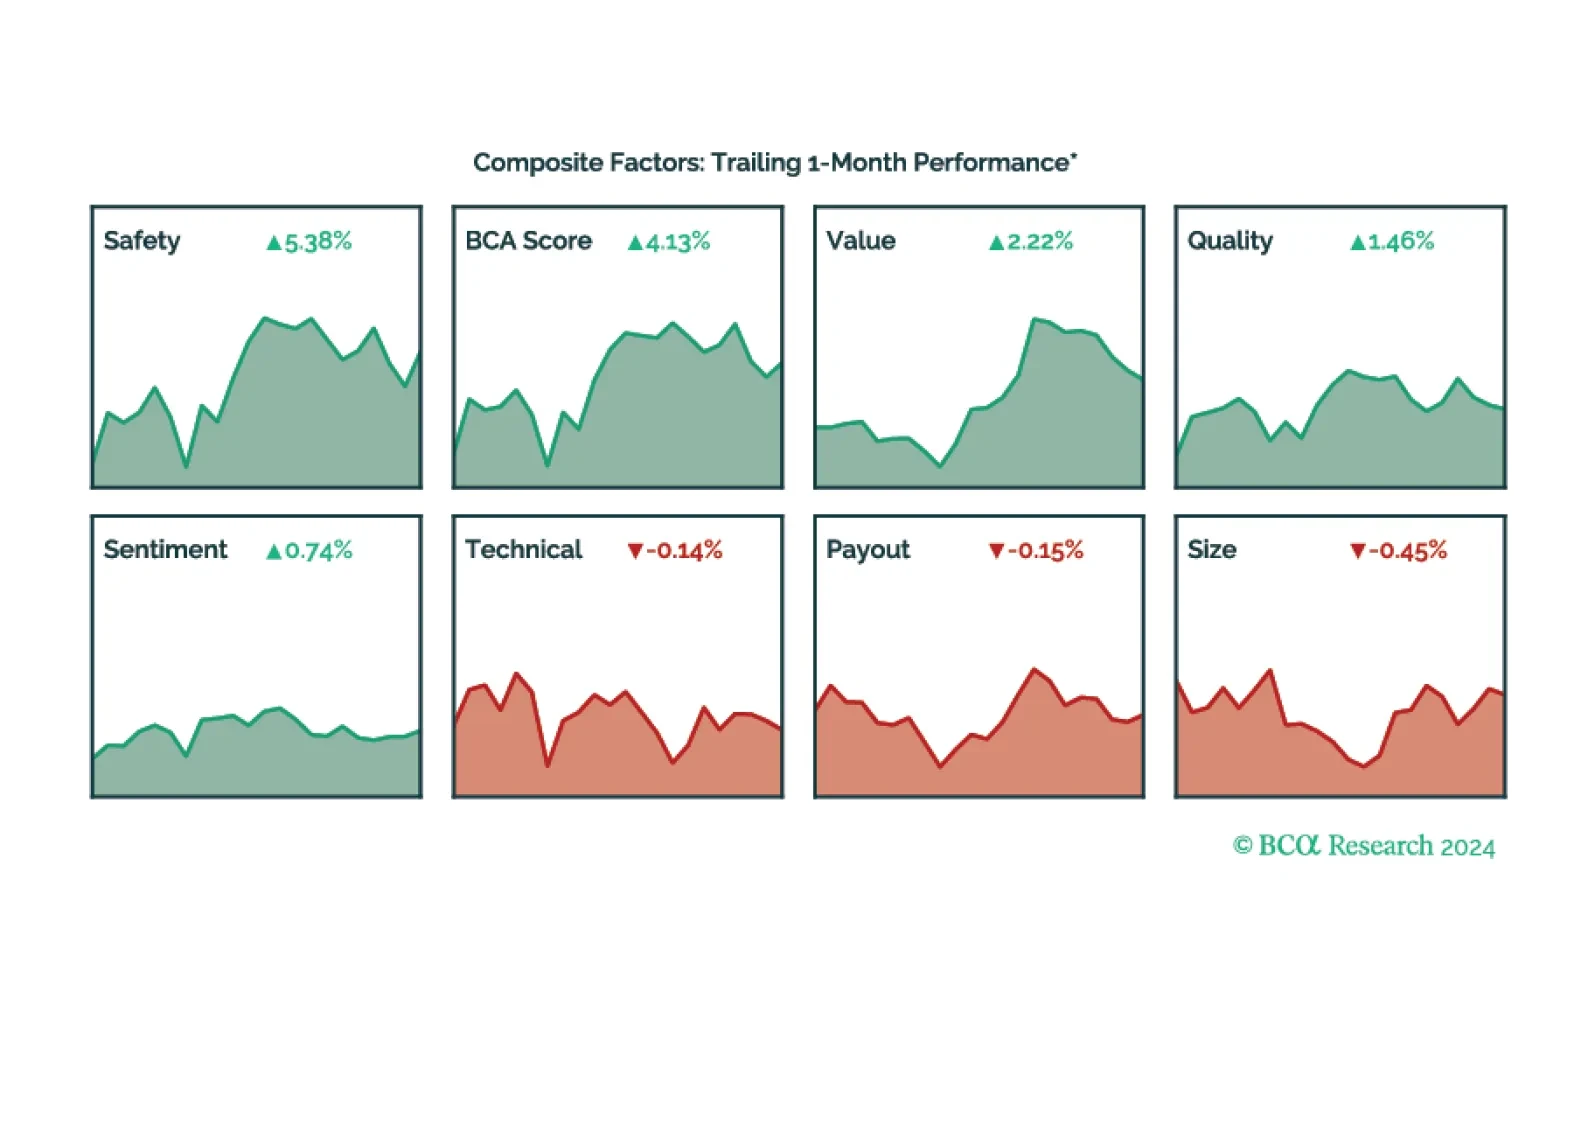
This month both the USHQ and SMID portfolios saw a downturn due to the idiosyncratic risk from the Powell's dovish stance in the May FOMC meeting. However, the Safety, Value, and Quality outperformed, resulting in a 4.13% return in BCA Score L/S.
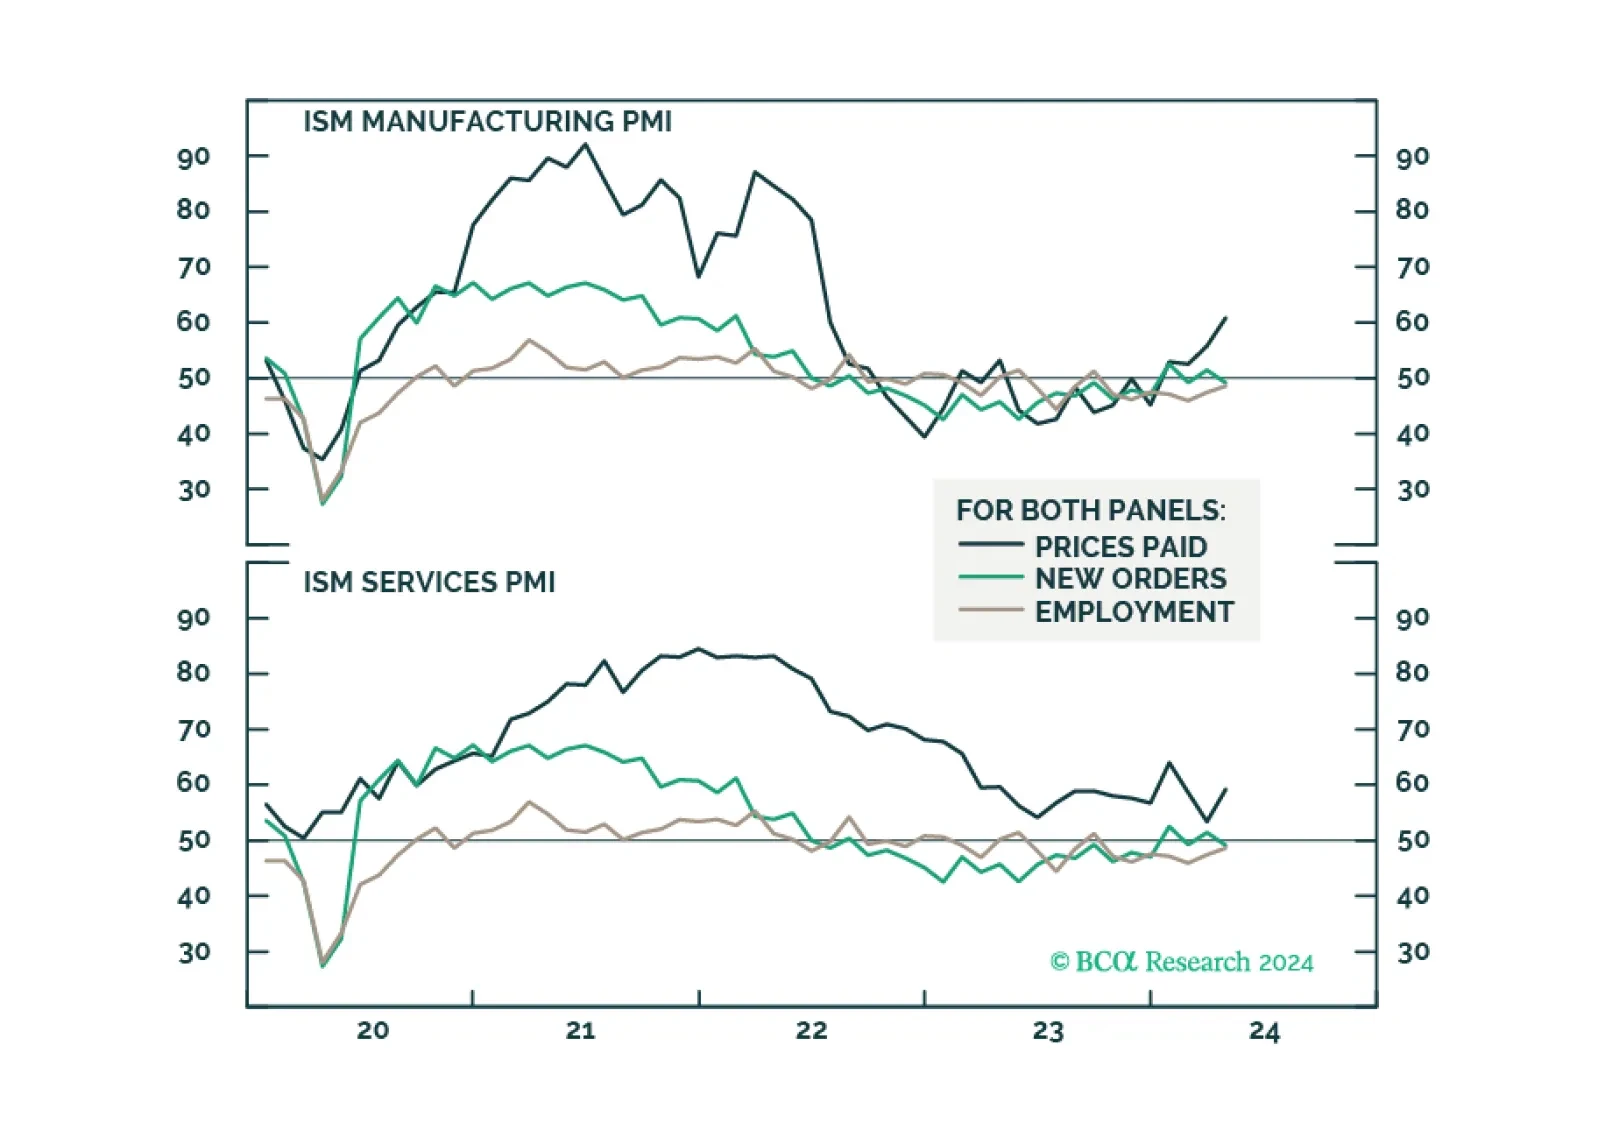
The broad market took a significant step backward in April, as market jitters gripped investors, stoking fears of higher for longer monetary policy. However, our roundtable investor poll has demonstrated that the majority remain constructive on equities, and have plenty of cash ready to be invested, which could prolong the rally. Economic data is deteriorating while inflation is stubborn. However, so far, bad news is good news as many believe that a “Fed put” is still on.
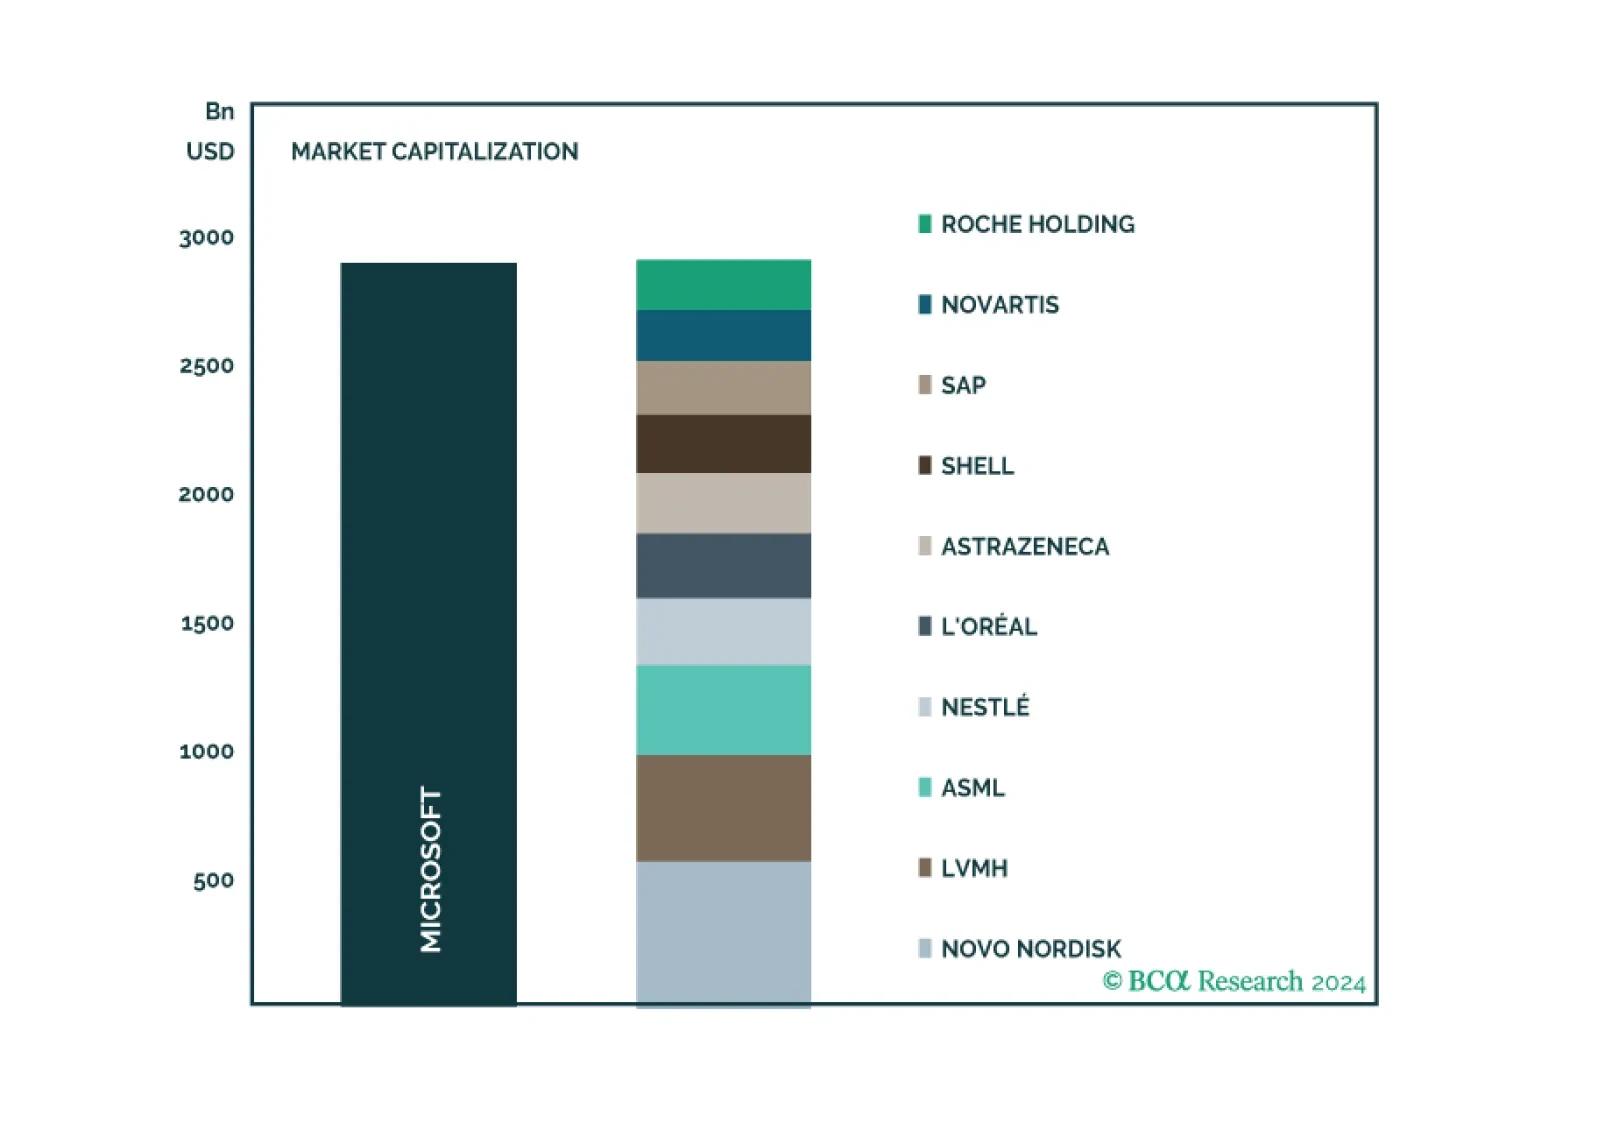

Some thoughts on this morning’s employment report and recent trends in US economic data.
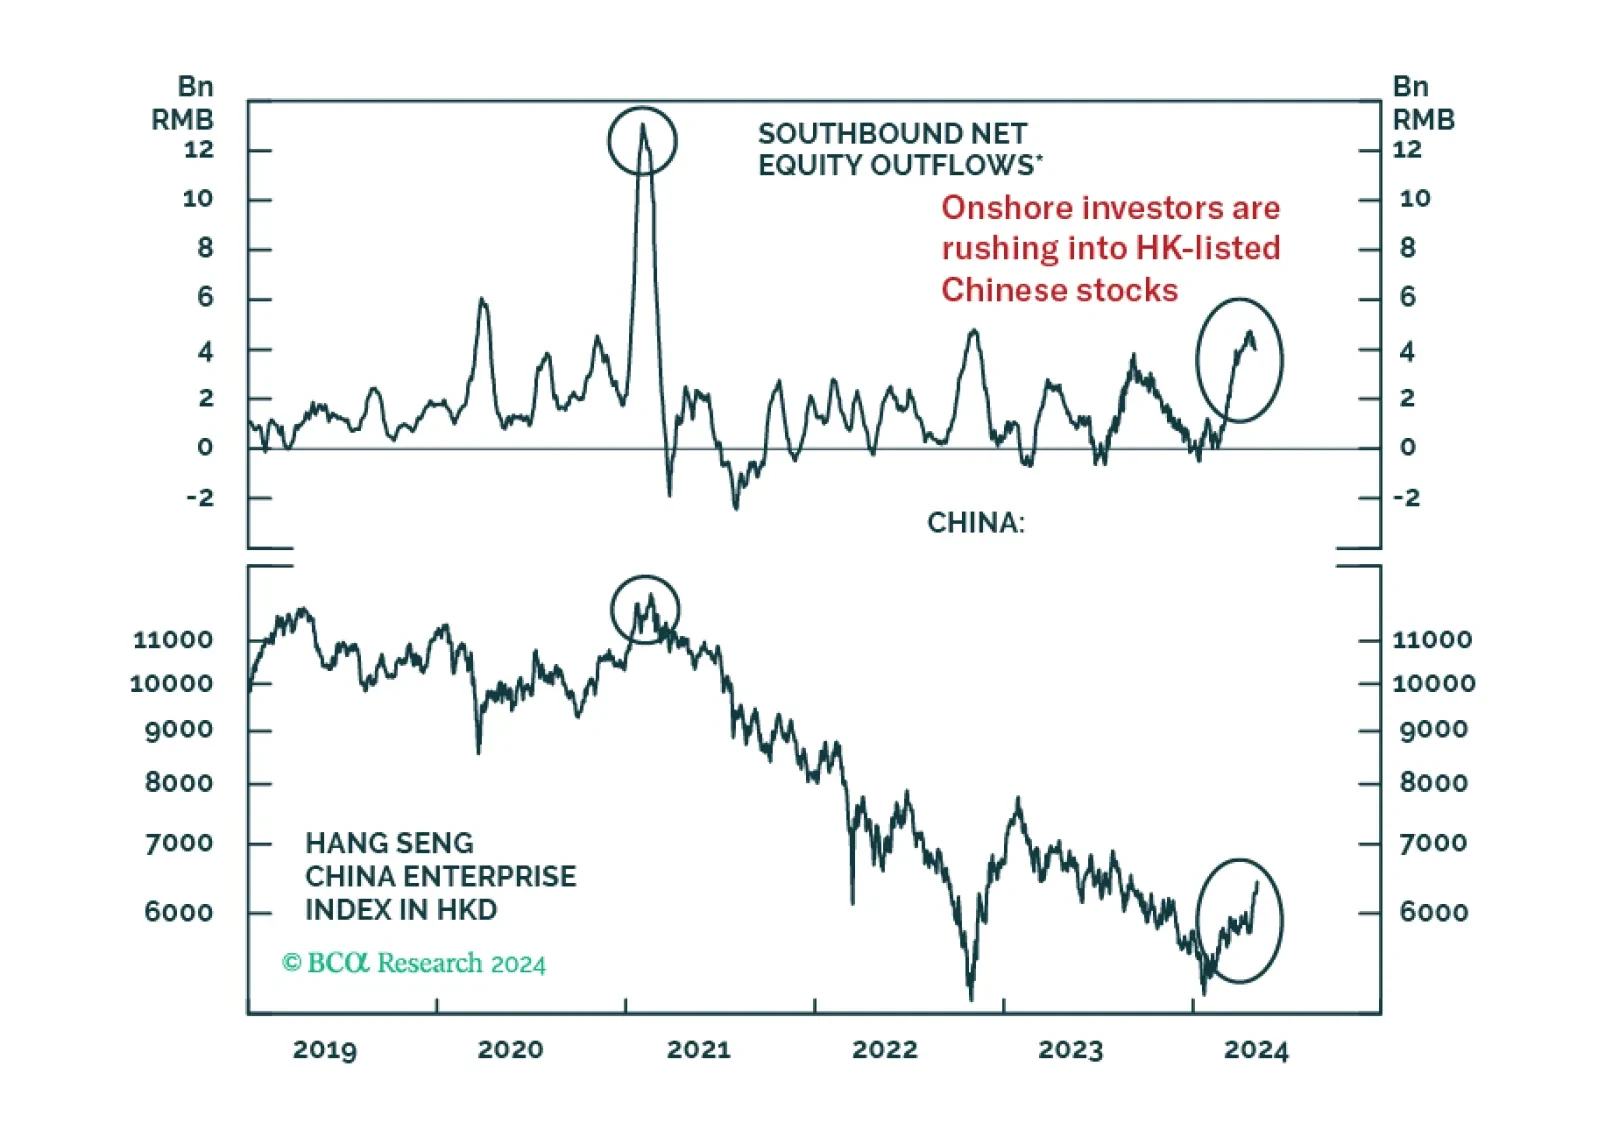
Mainland residents’ investments in gold, other metals, and Hong Kong-traded stocks are a form of capital outflow. Chinese authorities will counter any excessive capital flight with stricter administrative controls. Thus, markets benefiting from these flows will likely be hurt.
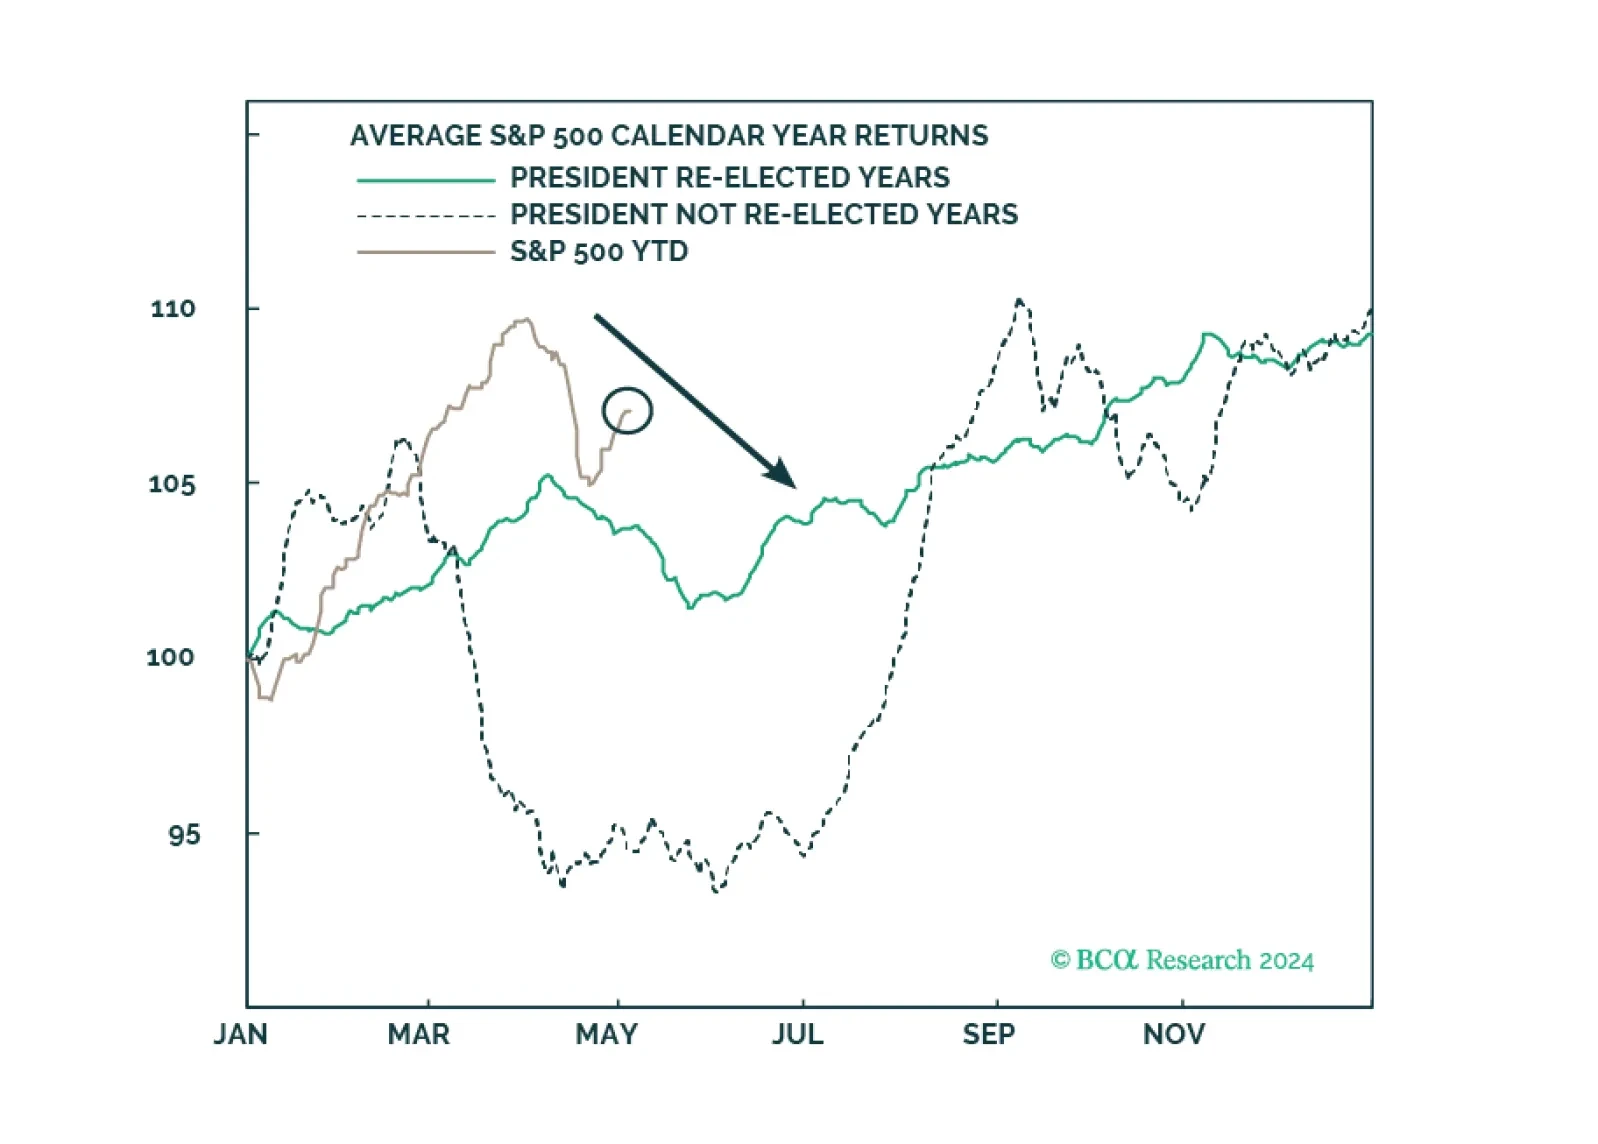
Investors should prepare for economic data to weaken even as policy uncertainty and geopolitical risk skyrocket ahead of the US election.

The Sector model continues to favor Energy and IT but upgraded Financials and Materials at the expense of Health Care and Consumer Discretionary. The Style indicator remains inclined towards Value-Large cap.

The no landing scenario has been gaining traction as the dominant driver of financial markets, providing a tailwind to commodities via increased demand for inflation hedges. Unless commodity markets experience a major supply shock, a narrative shift in favor of the hard landing scenario would create a headwind for commodities. A decisive top in the equity market would provide an early warning for commodity investors.