Latest from BCA Research
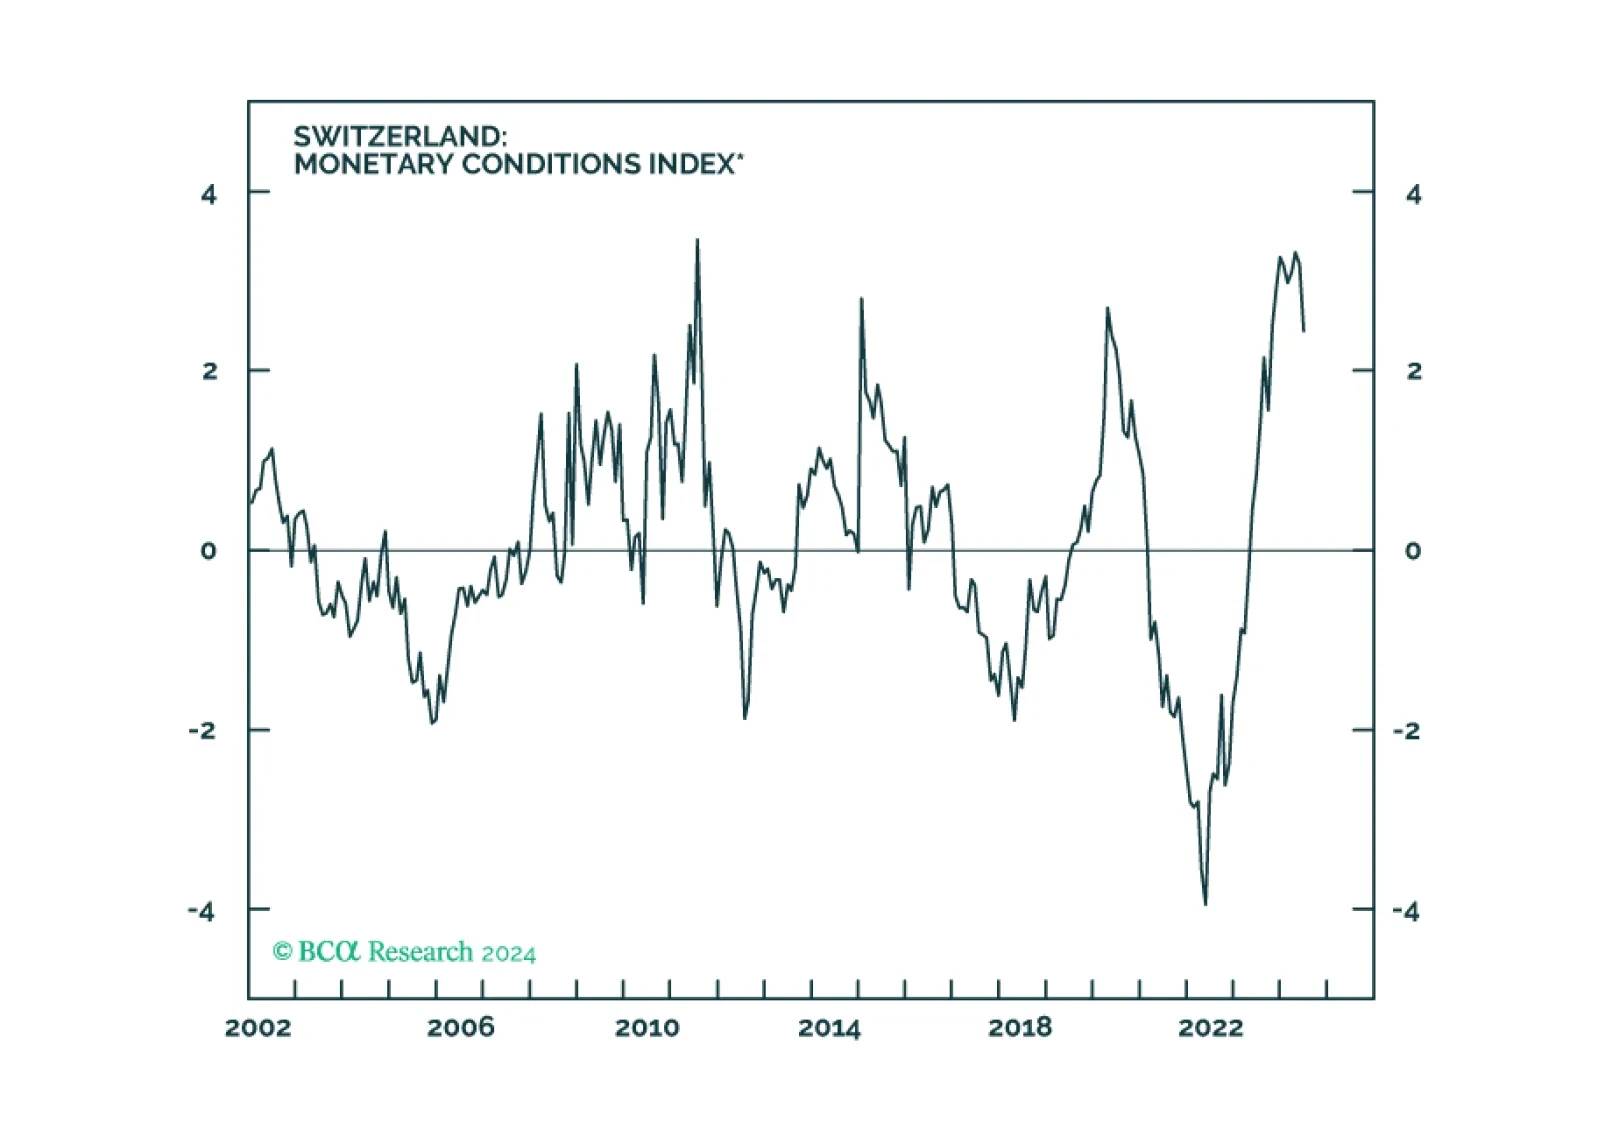
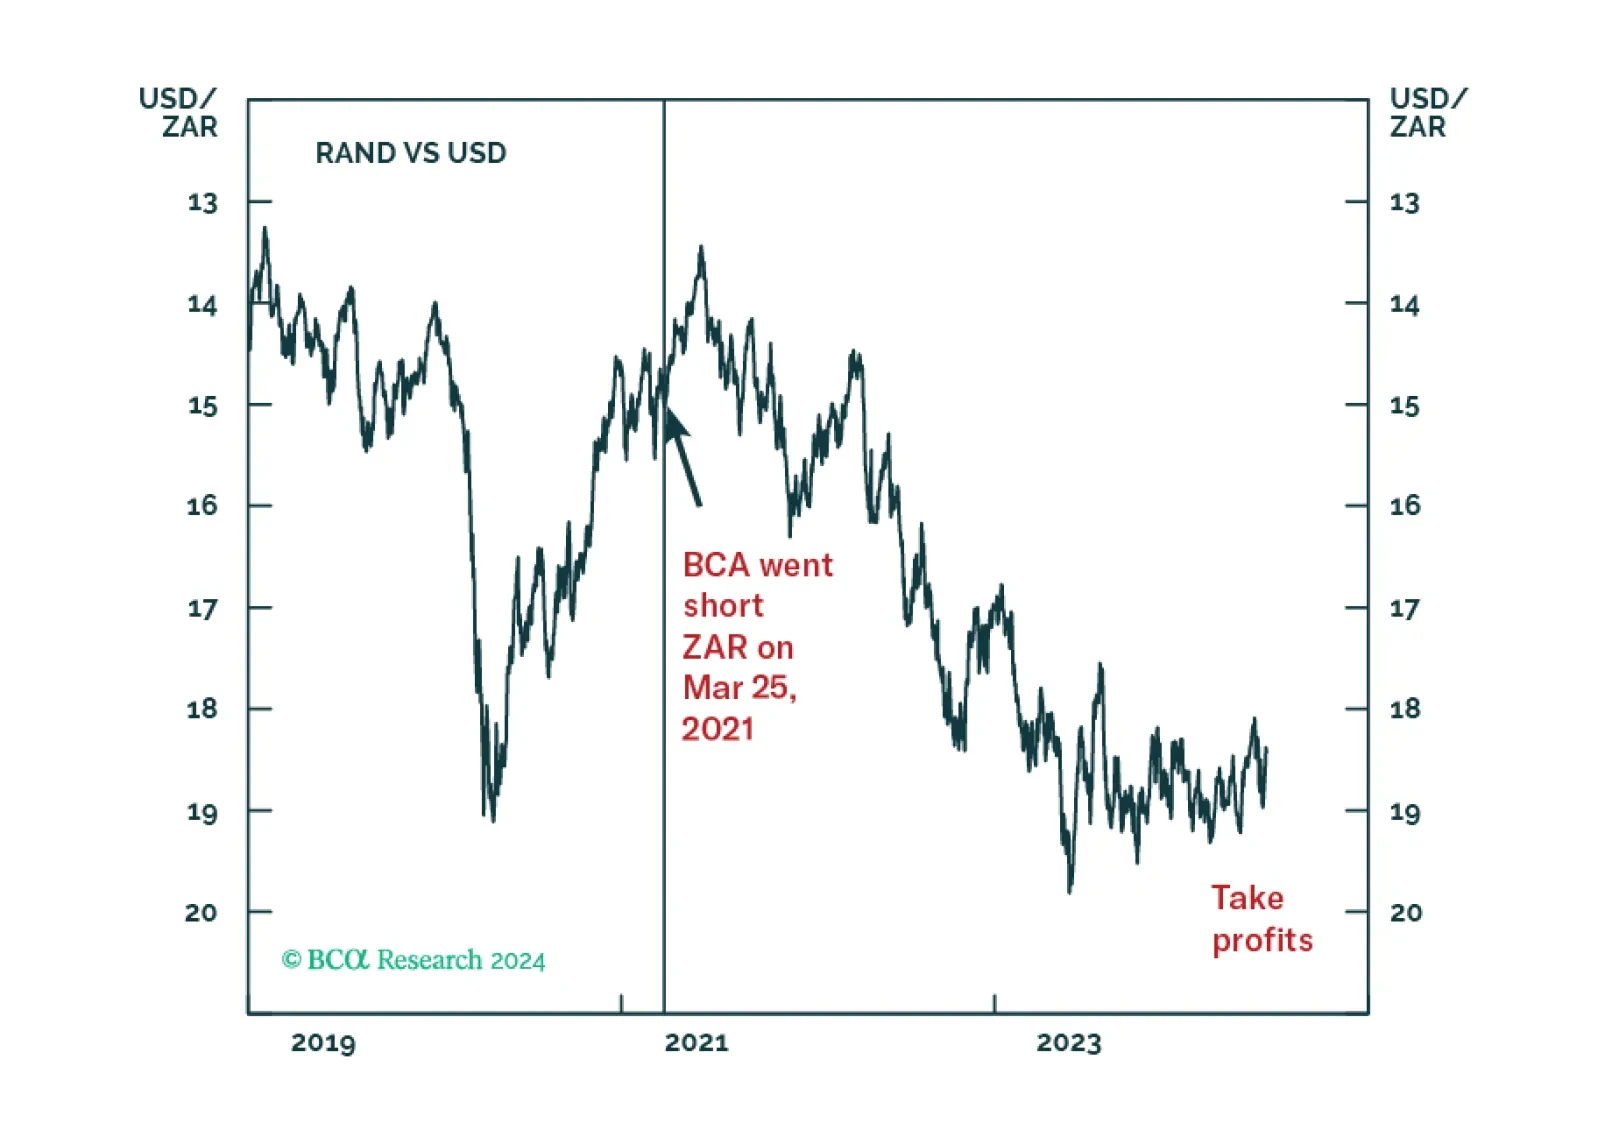
We look at the implications a various European central bank meetings this week, for currency strategy.

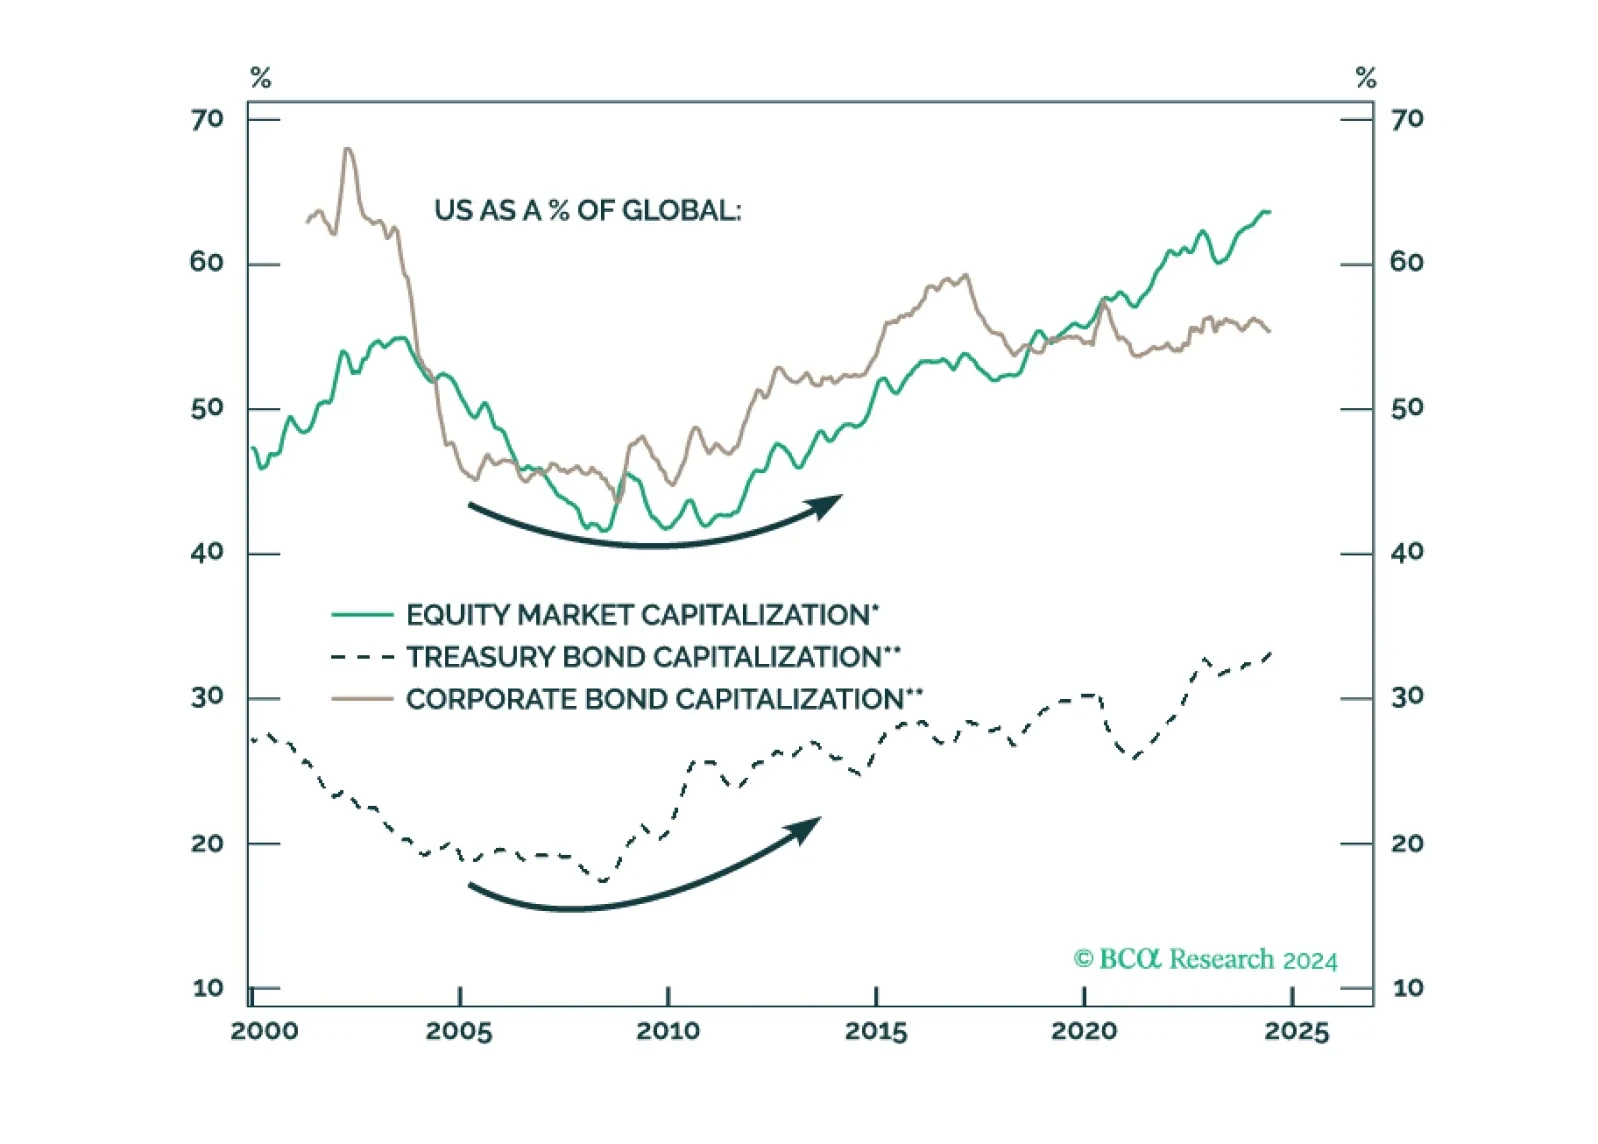
To reduce the Chinese economy’s addiction to credit and use new credit to foster growth, authorities must restructure or shut down numerous negative cash flow enterprises. Slumping US and global growth will lead to lower US bond yields. Yet, the trade-weighted greenback will likely appreciate if global risk assets sell off.

The EU's import tariff increases on Chinese EVs are expected to have a minimal impact on China's overall exports. We anticipate that most Western-brand EV shipments from China will be less affected by the EU import tax hike. Beijing will likely pursue continued negotiations with the EU rather than resort to harsh retaliatory measures.
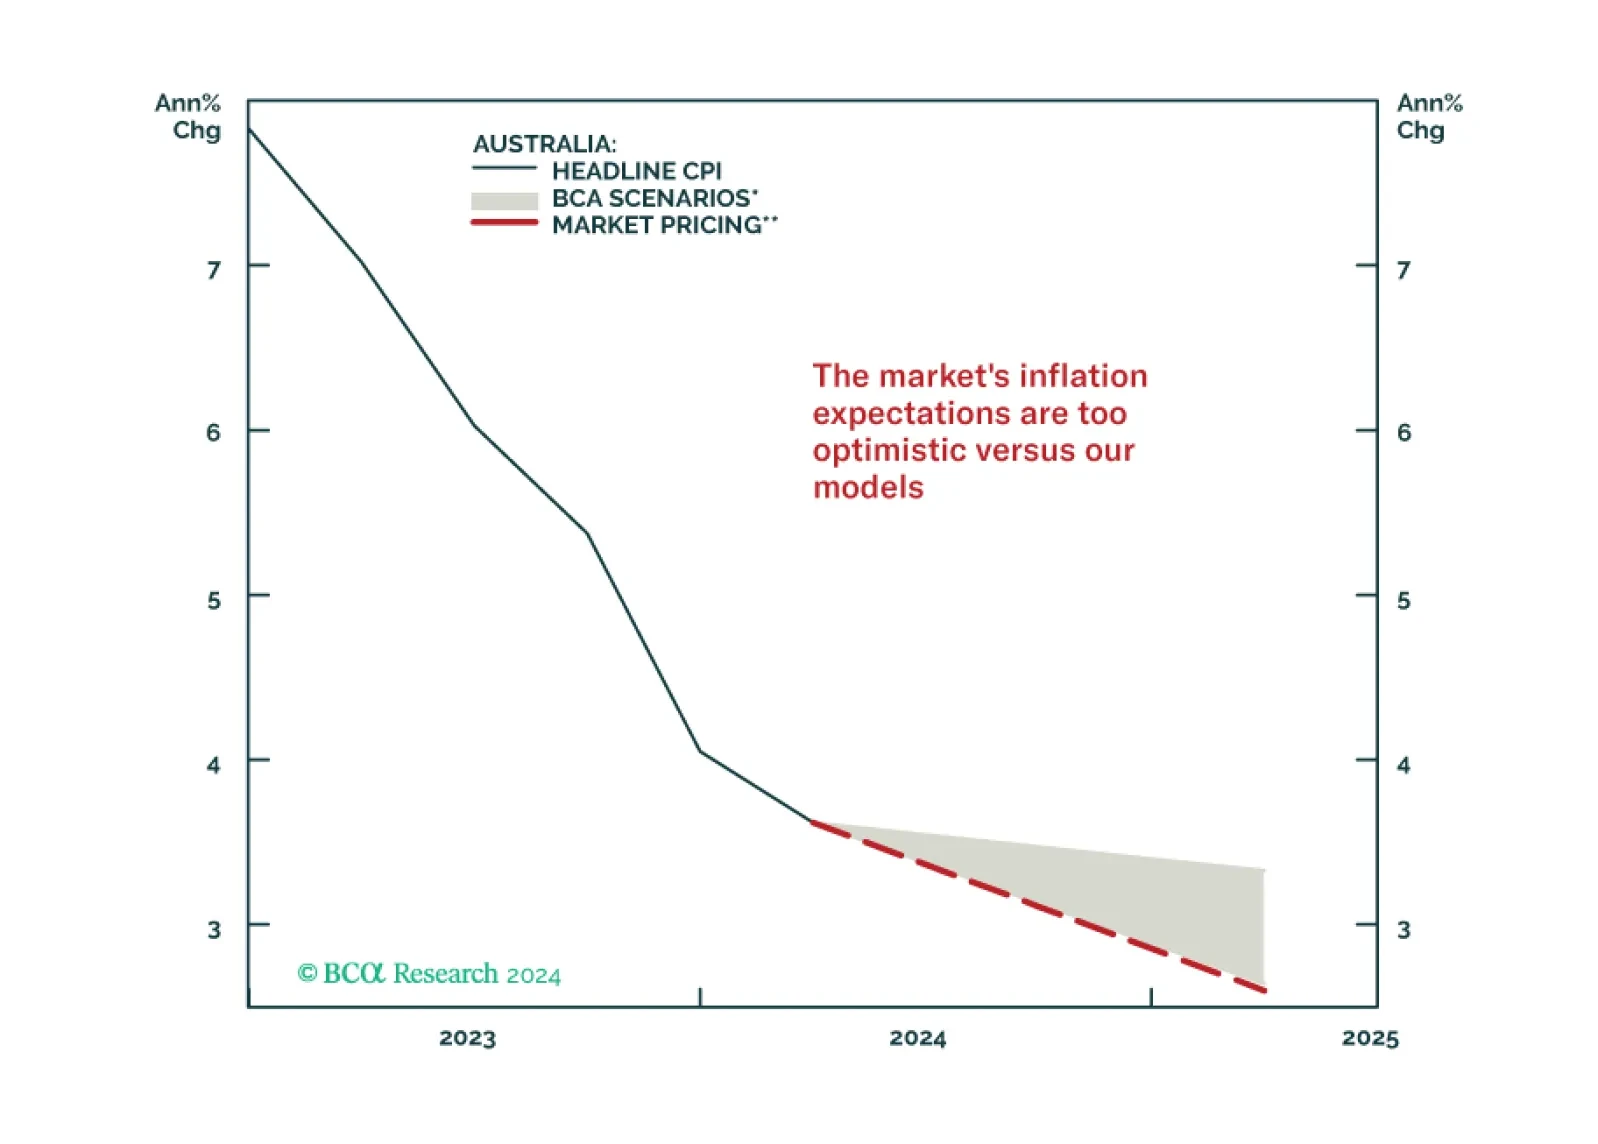
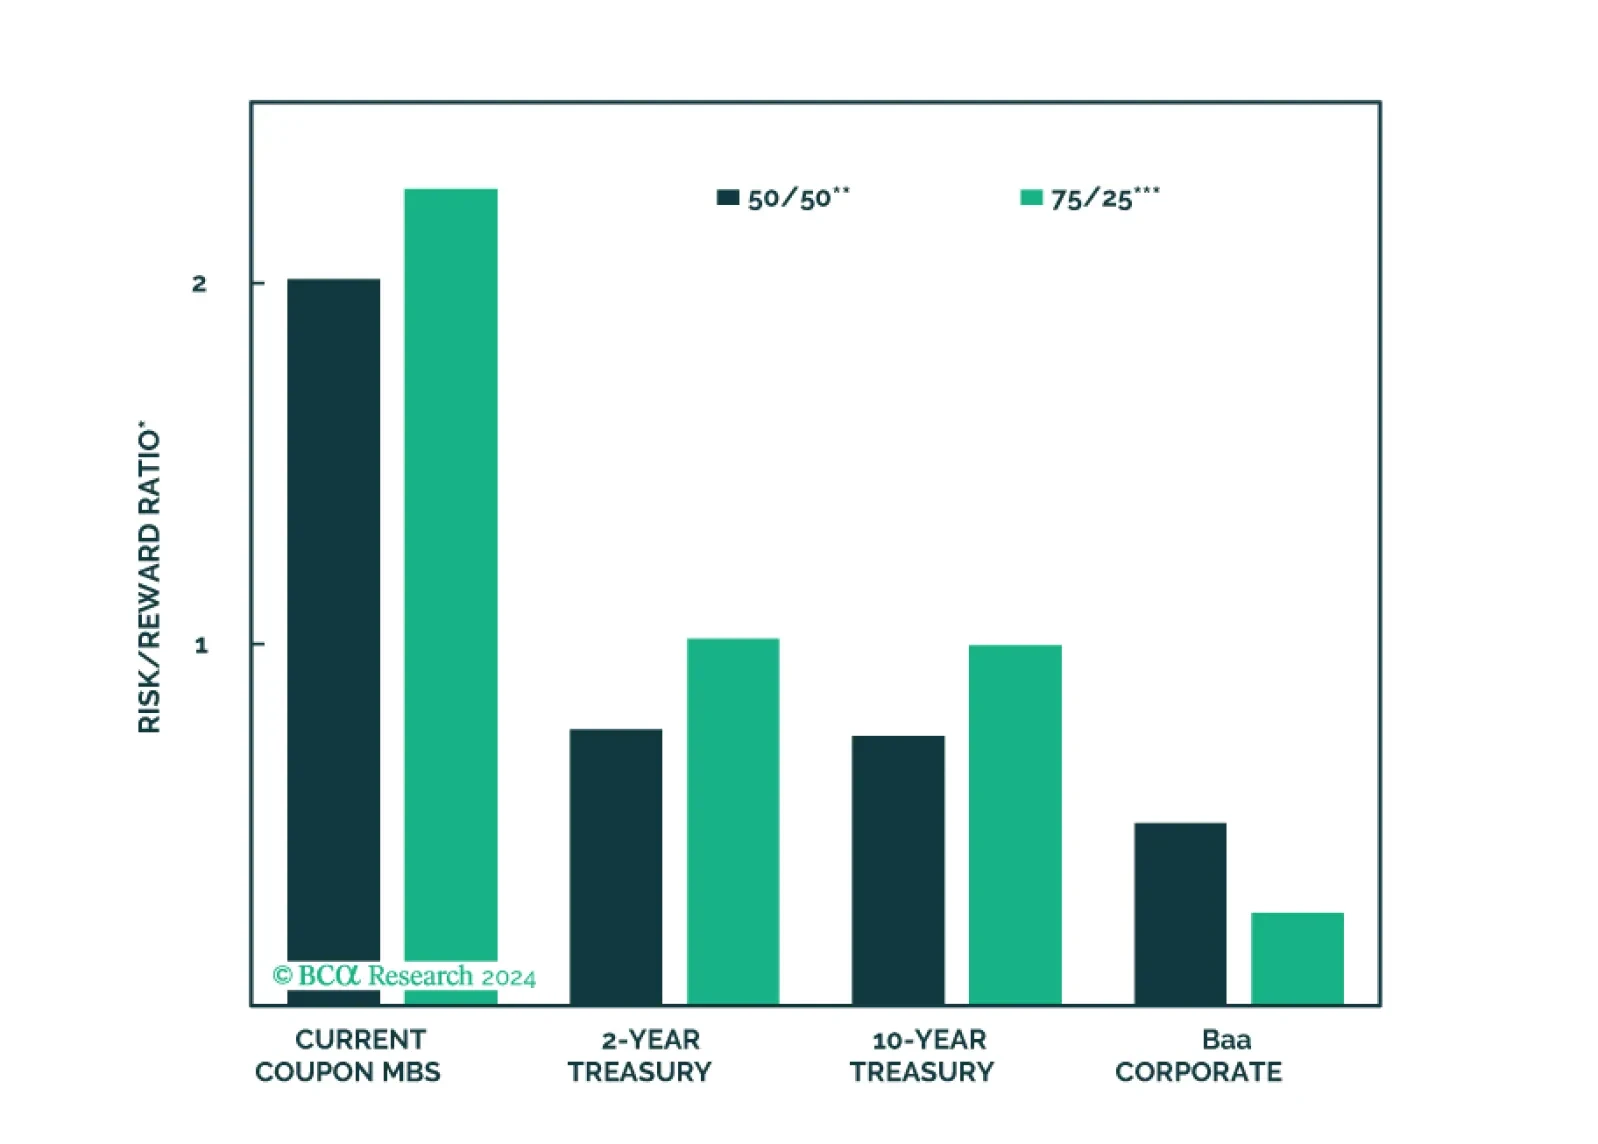
In light of this week’s RBA decision to keep policy on hold, we look at the best possible trades in fixed income markets. In our view, inflation-linked bonds, relative to nominals remain a good bet.
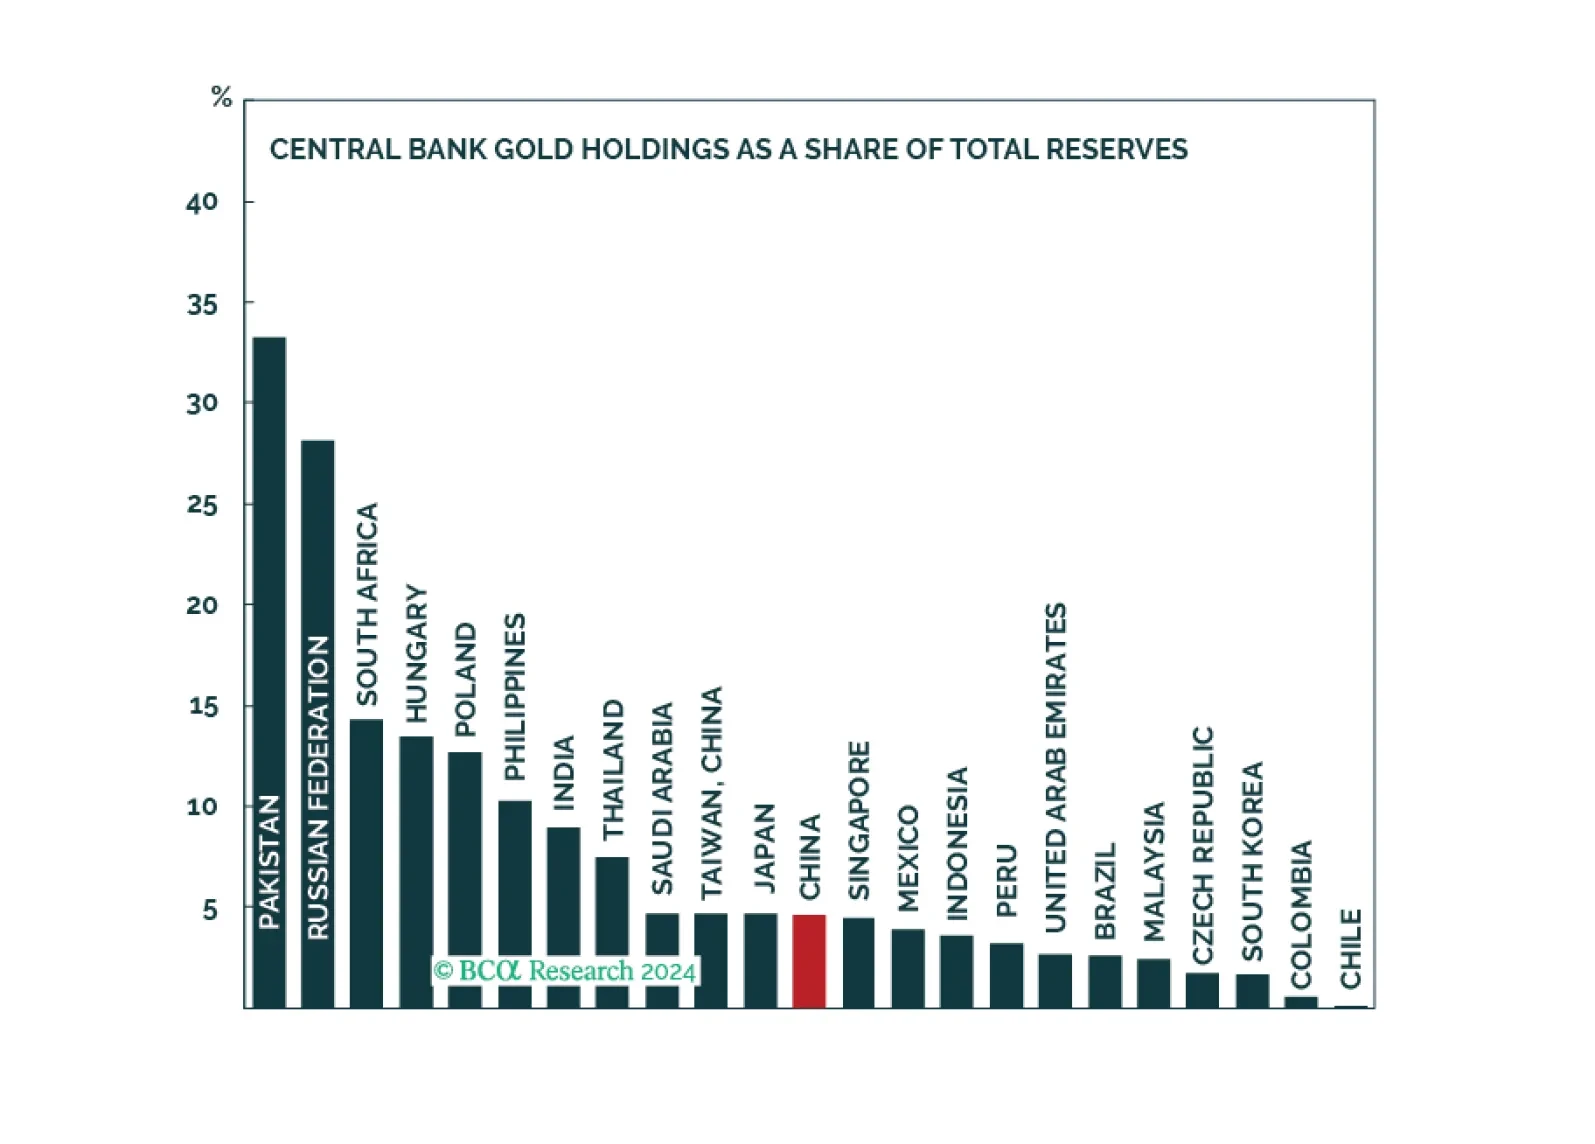
Gold prices might experience a correction or consolidation over the near term. However, cyclical and structural forces will ultimately cause the yellow metal to trend upwards.

European assets are selling off as investors panic about the upcoming French election. Is this panic justified, and if so, for how long?
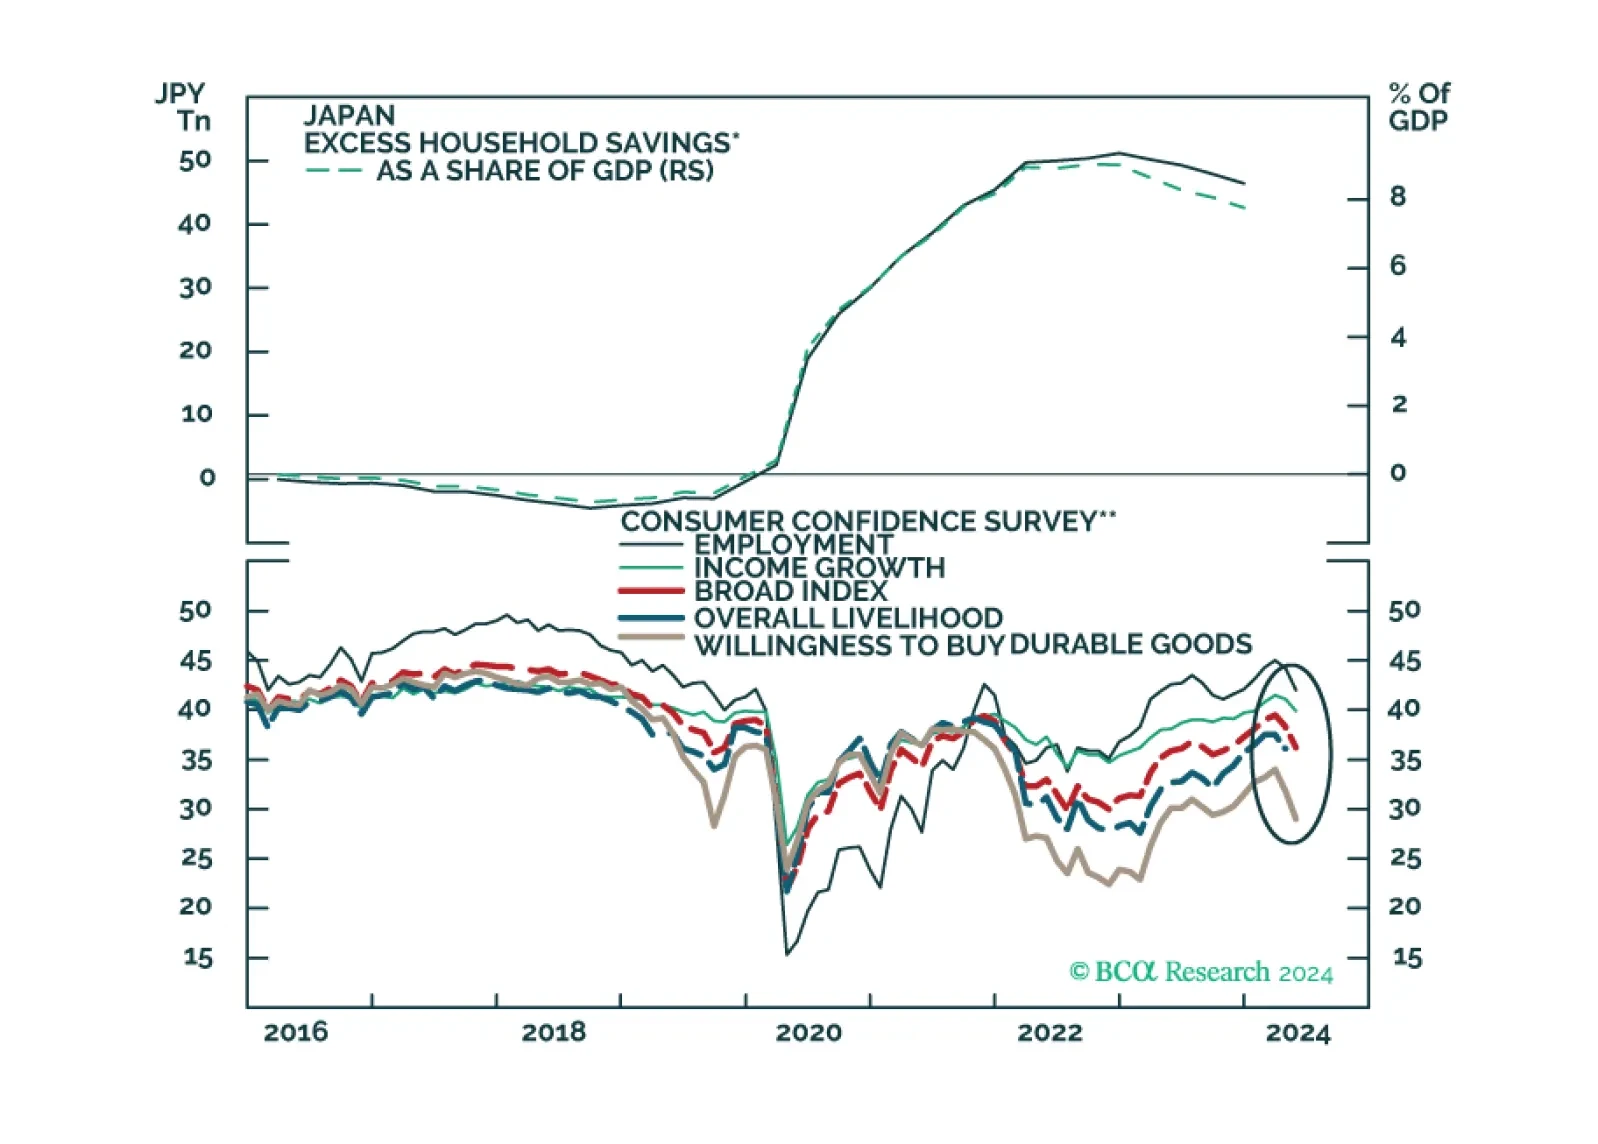
In this insight, we update our thinking on the recent BoJ move in terms of positioning for the yen and JGB yields.