Latest from BCA Research
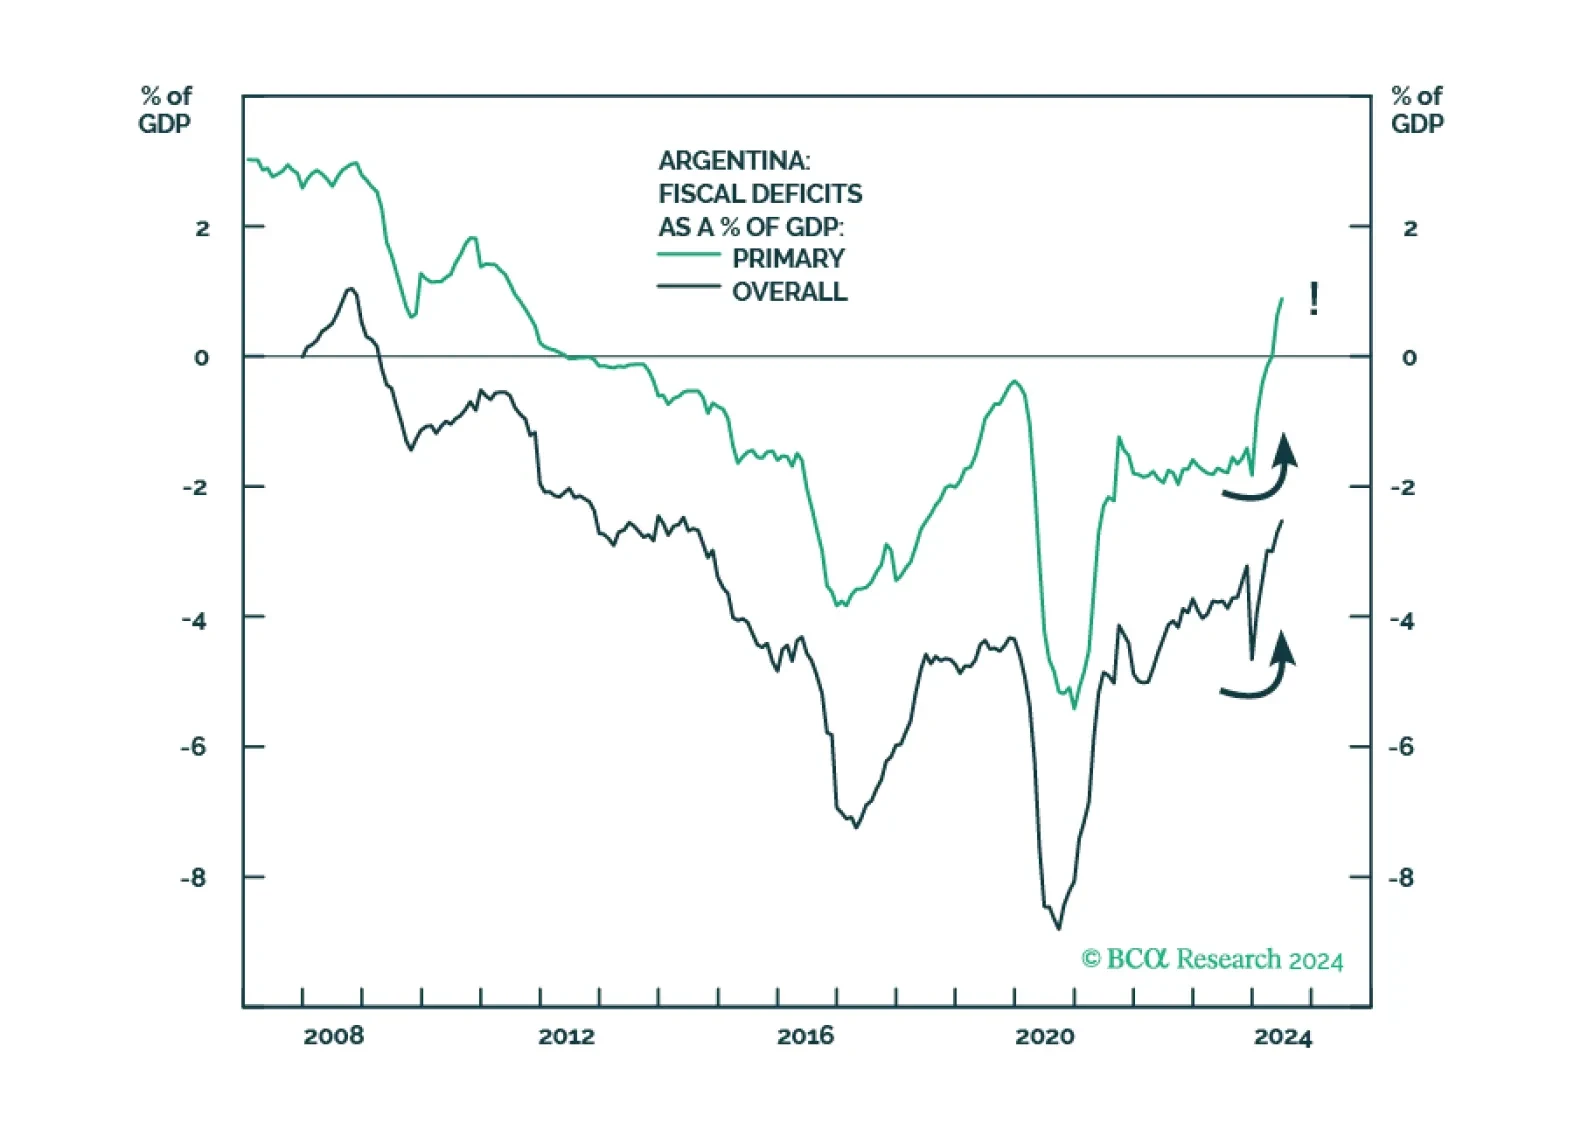
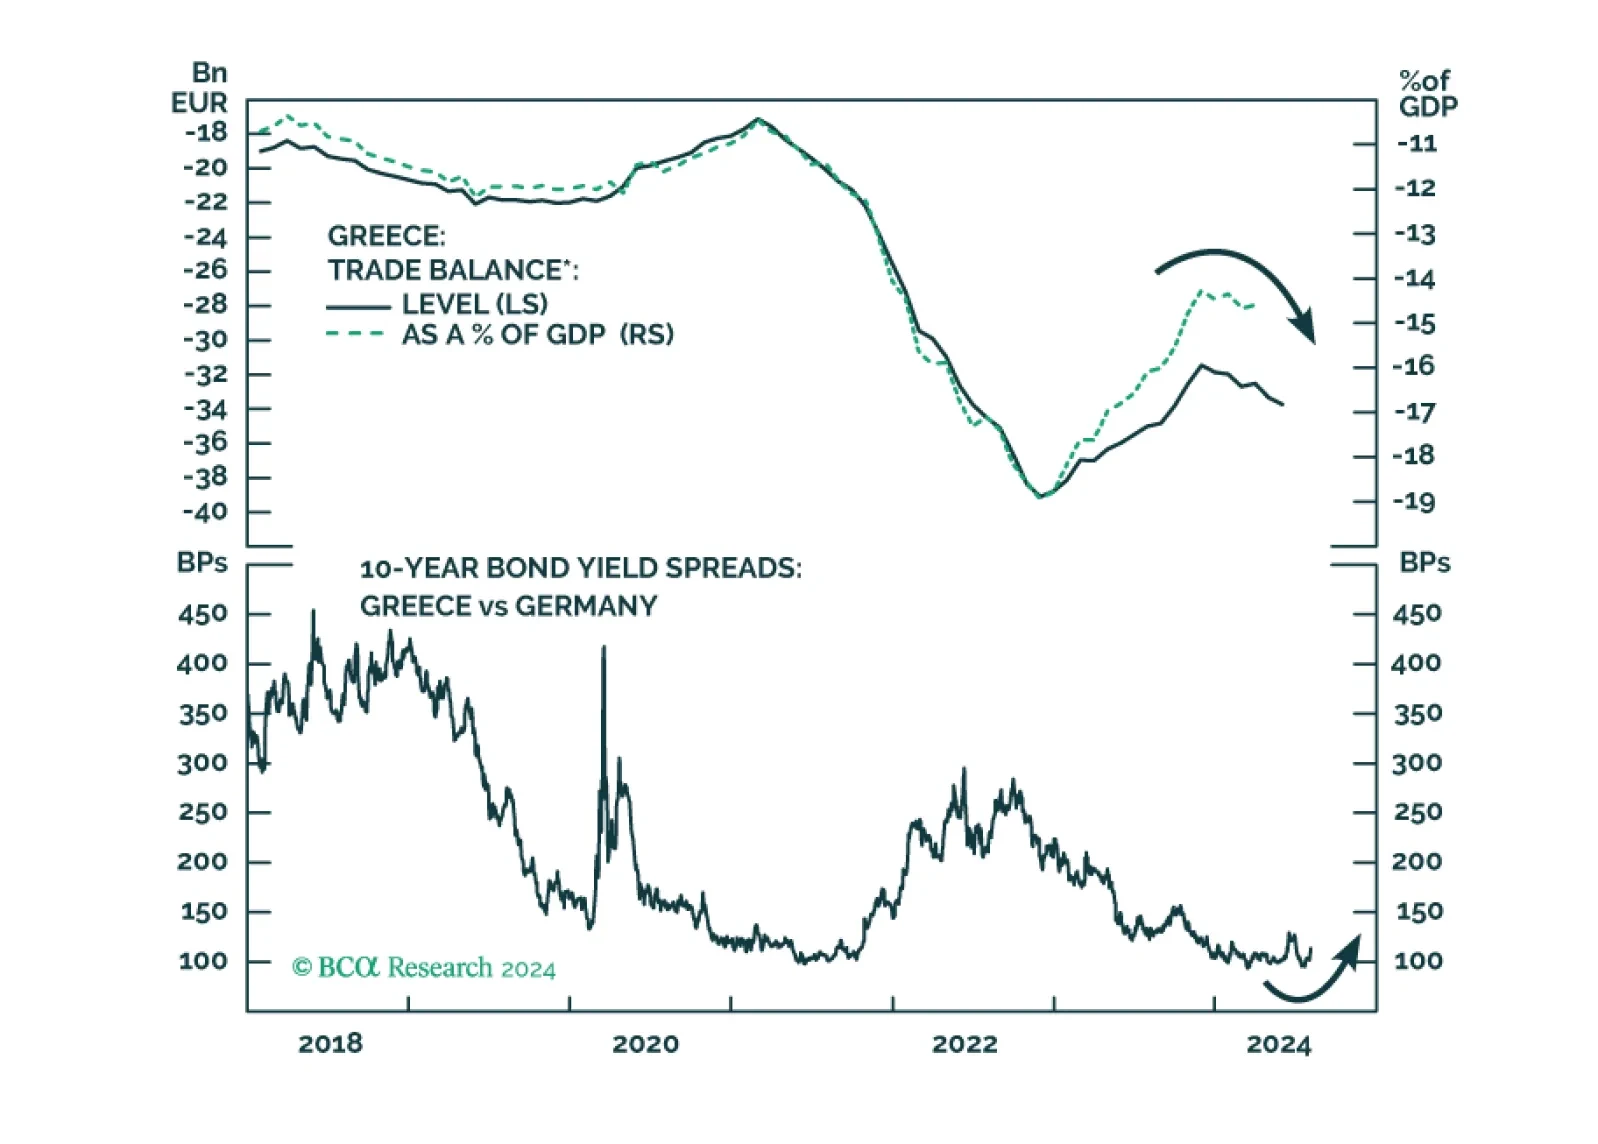
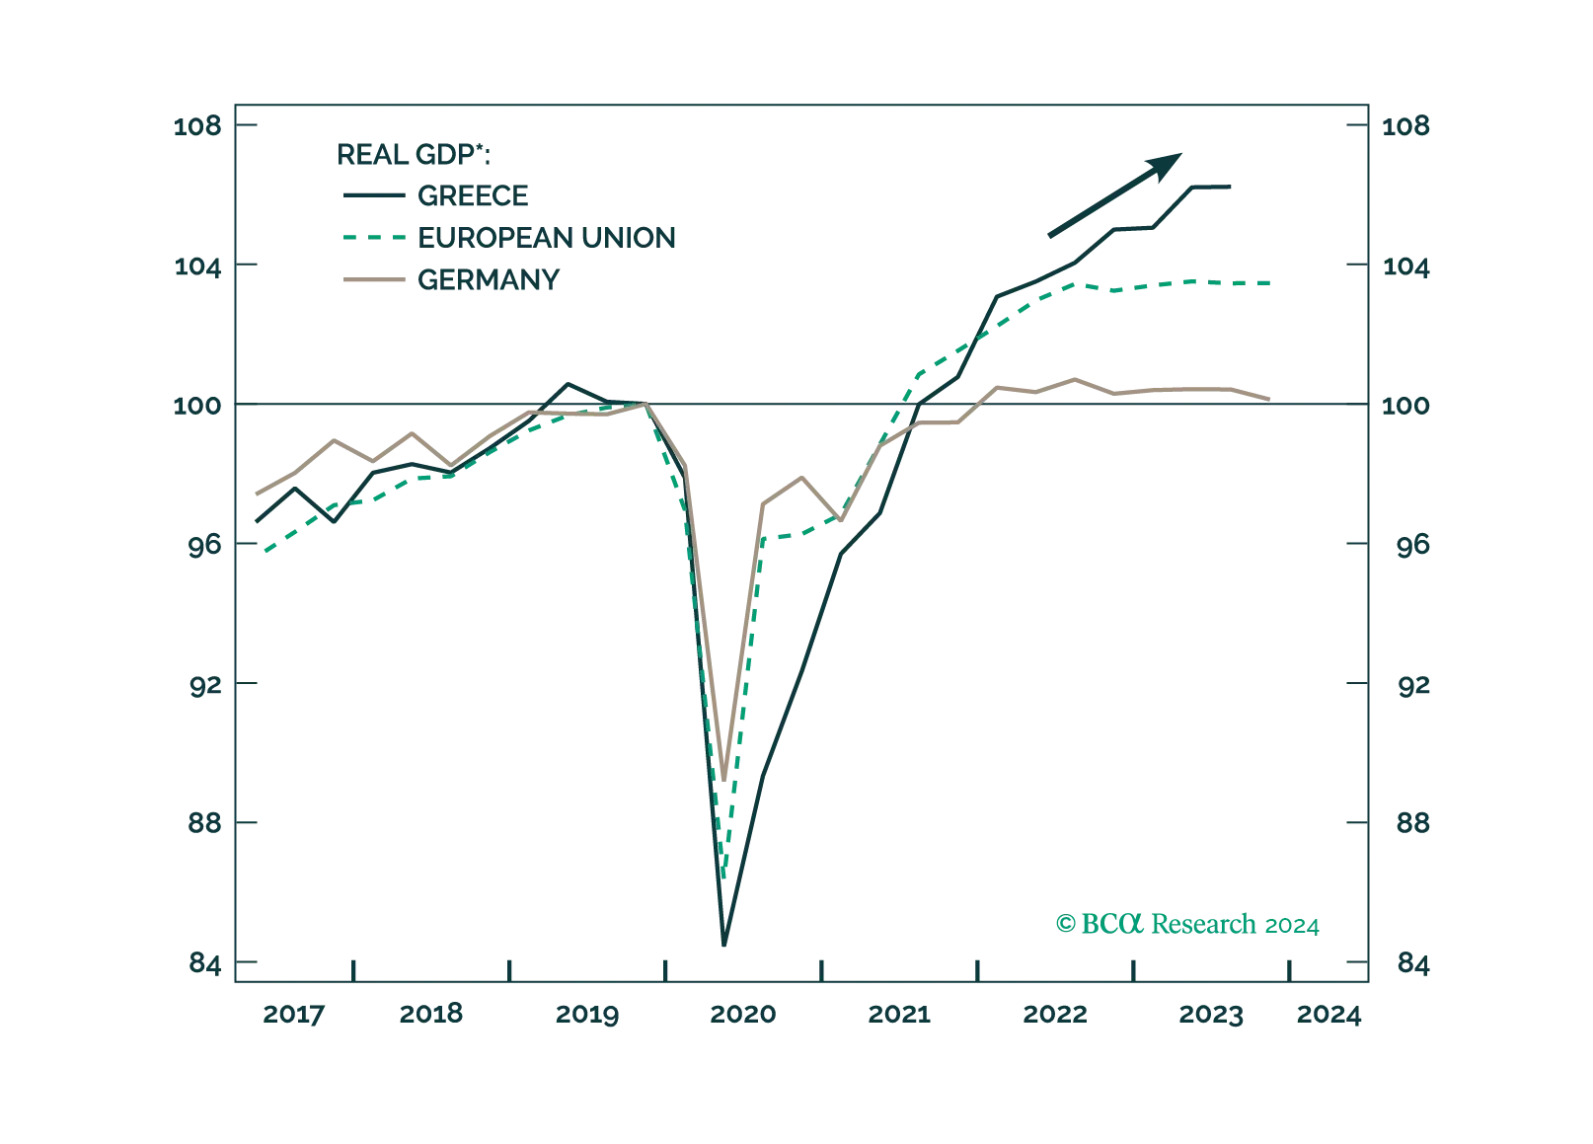
Absolute return investors should be tactically cautious on Greek assets. Dedicated EM equity portfolios, however, should overweight Greek stocks.

The second half of the year will be challenging for equity investors because economic growth is clearly deteriorating. Election uncertainty is adding to volatility. Bad news is now bad news, and equity markets will likely pull back, anticipating a hard landing. The GAI trade has run its course and now attracts more scrutiny. Take profits from recent winners. Don’t buy on a dip (at least not yet). Defensive and other laggards offer downside protection and will deliver positive relative returns. Close overweights or even go underweight in the Magnificent Seven sectors.
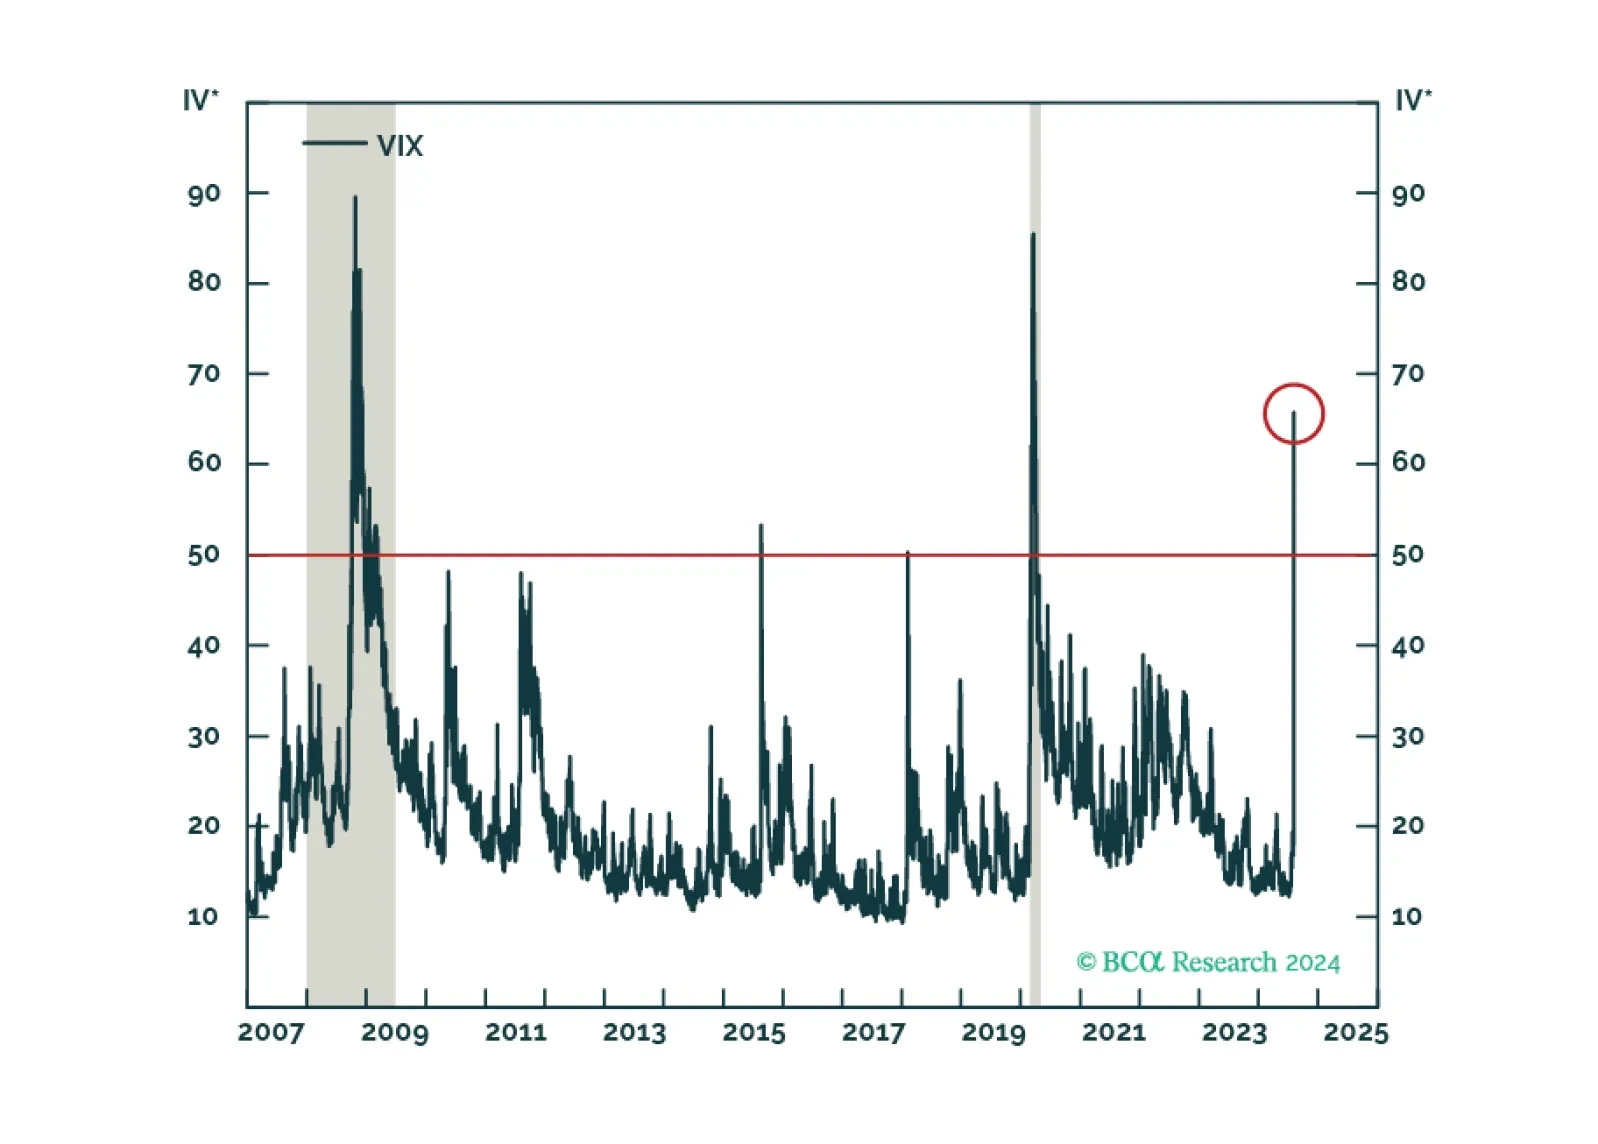
Market volatility has surged. Investors should no longer be allocating into Tail Risk structures. For those invested, start monetizing gains and let CTAs and Developed Market Fixed Income take the wheel from here.
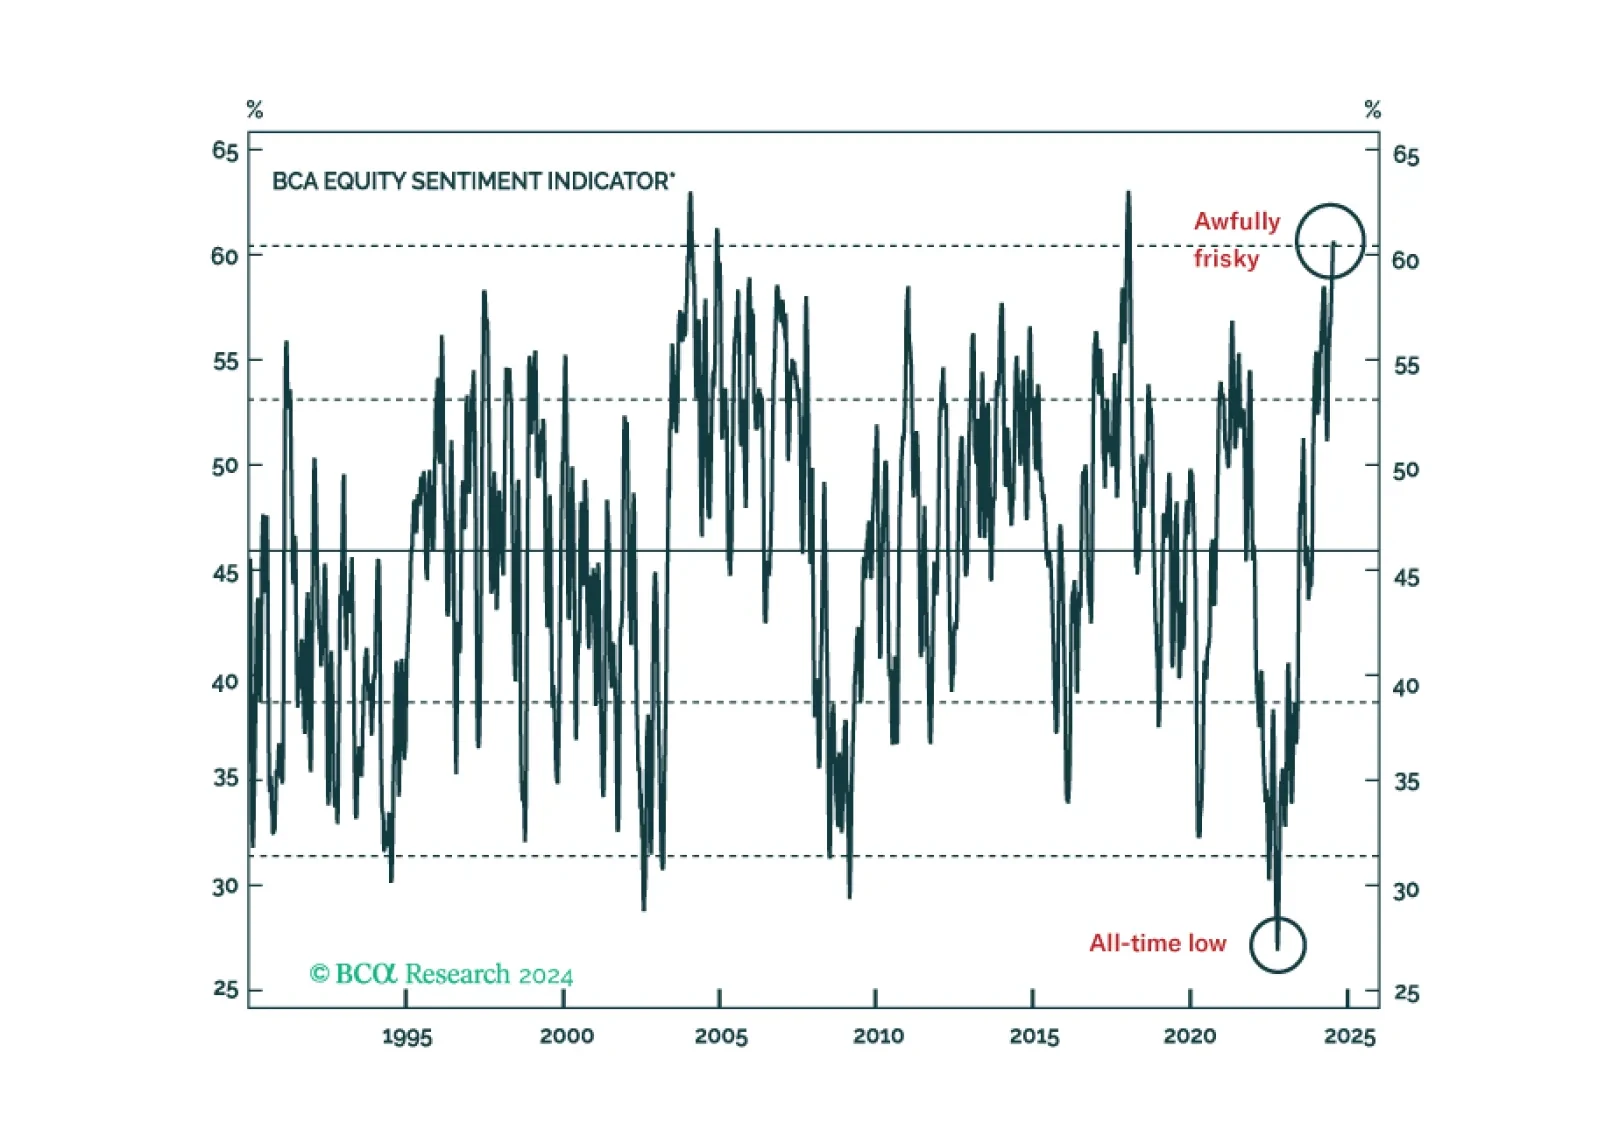
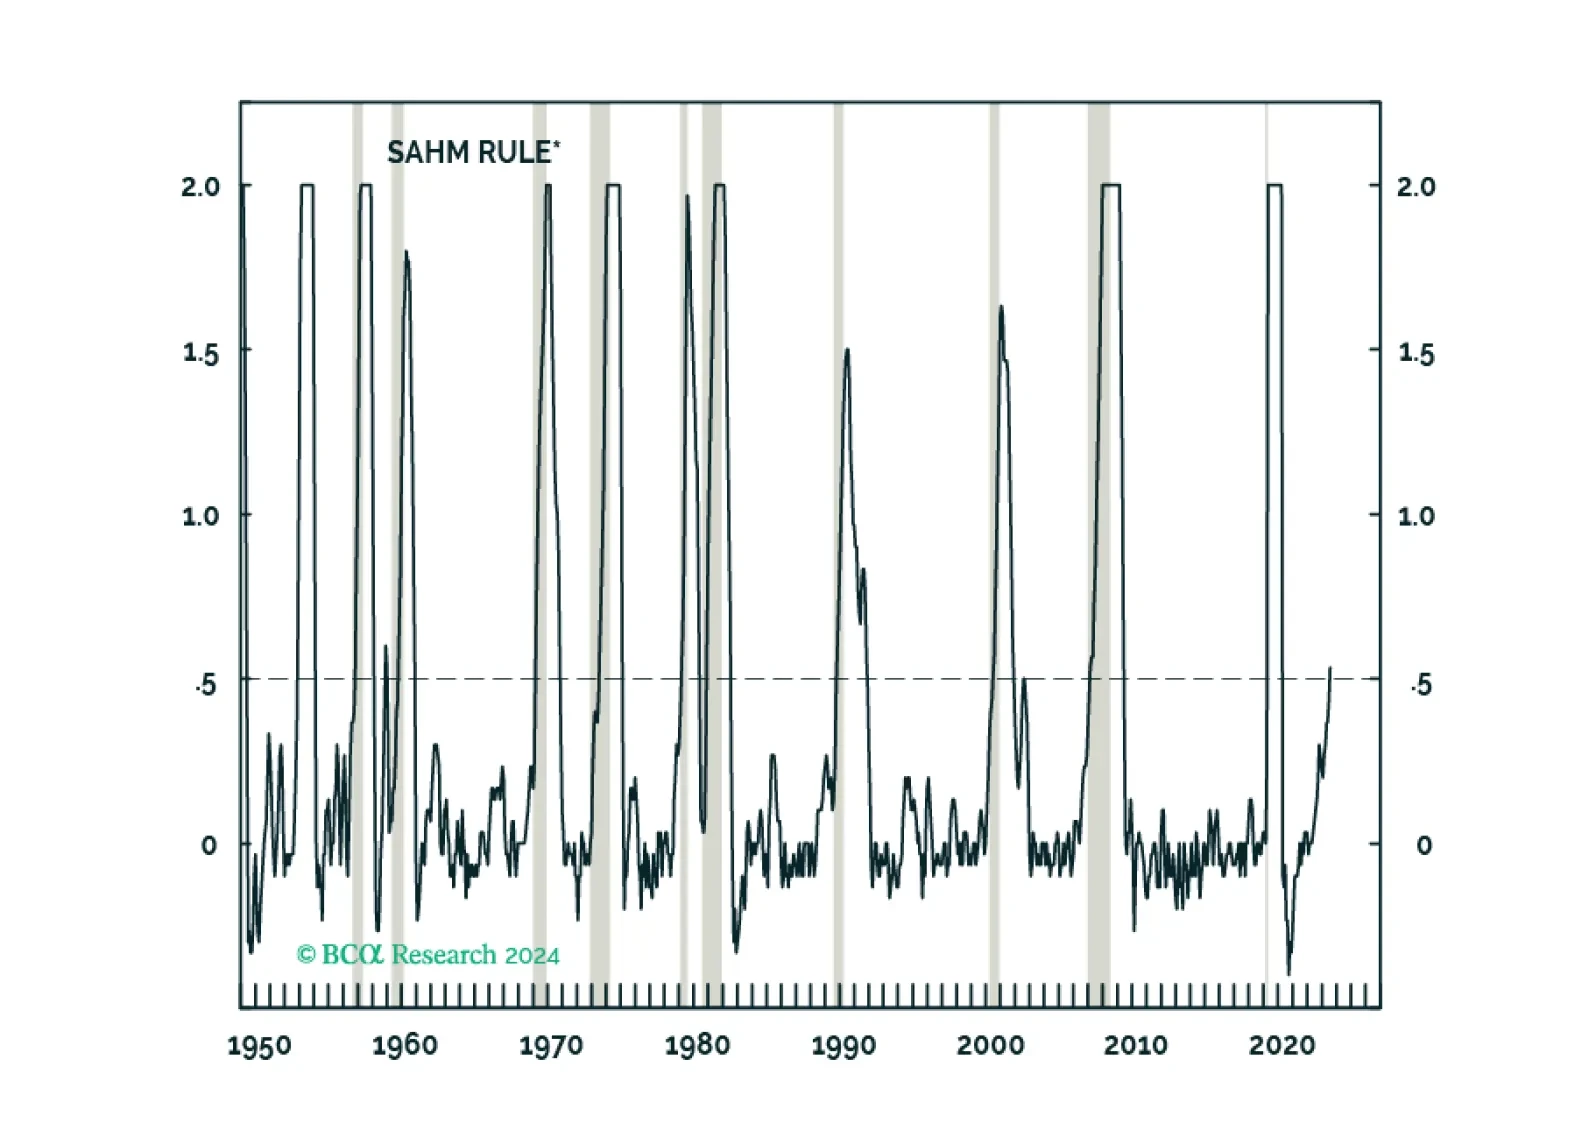
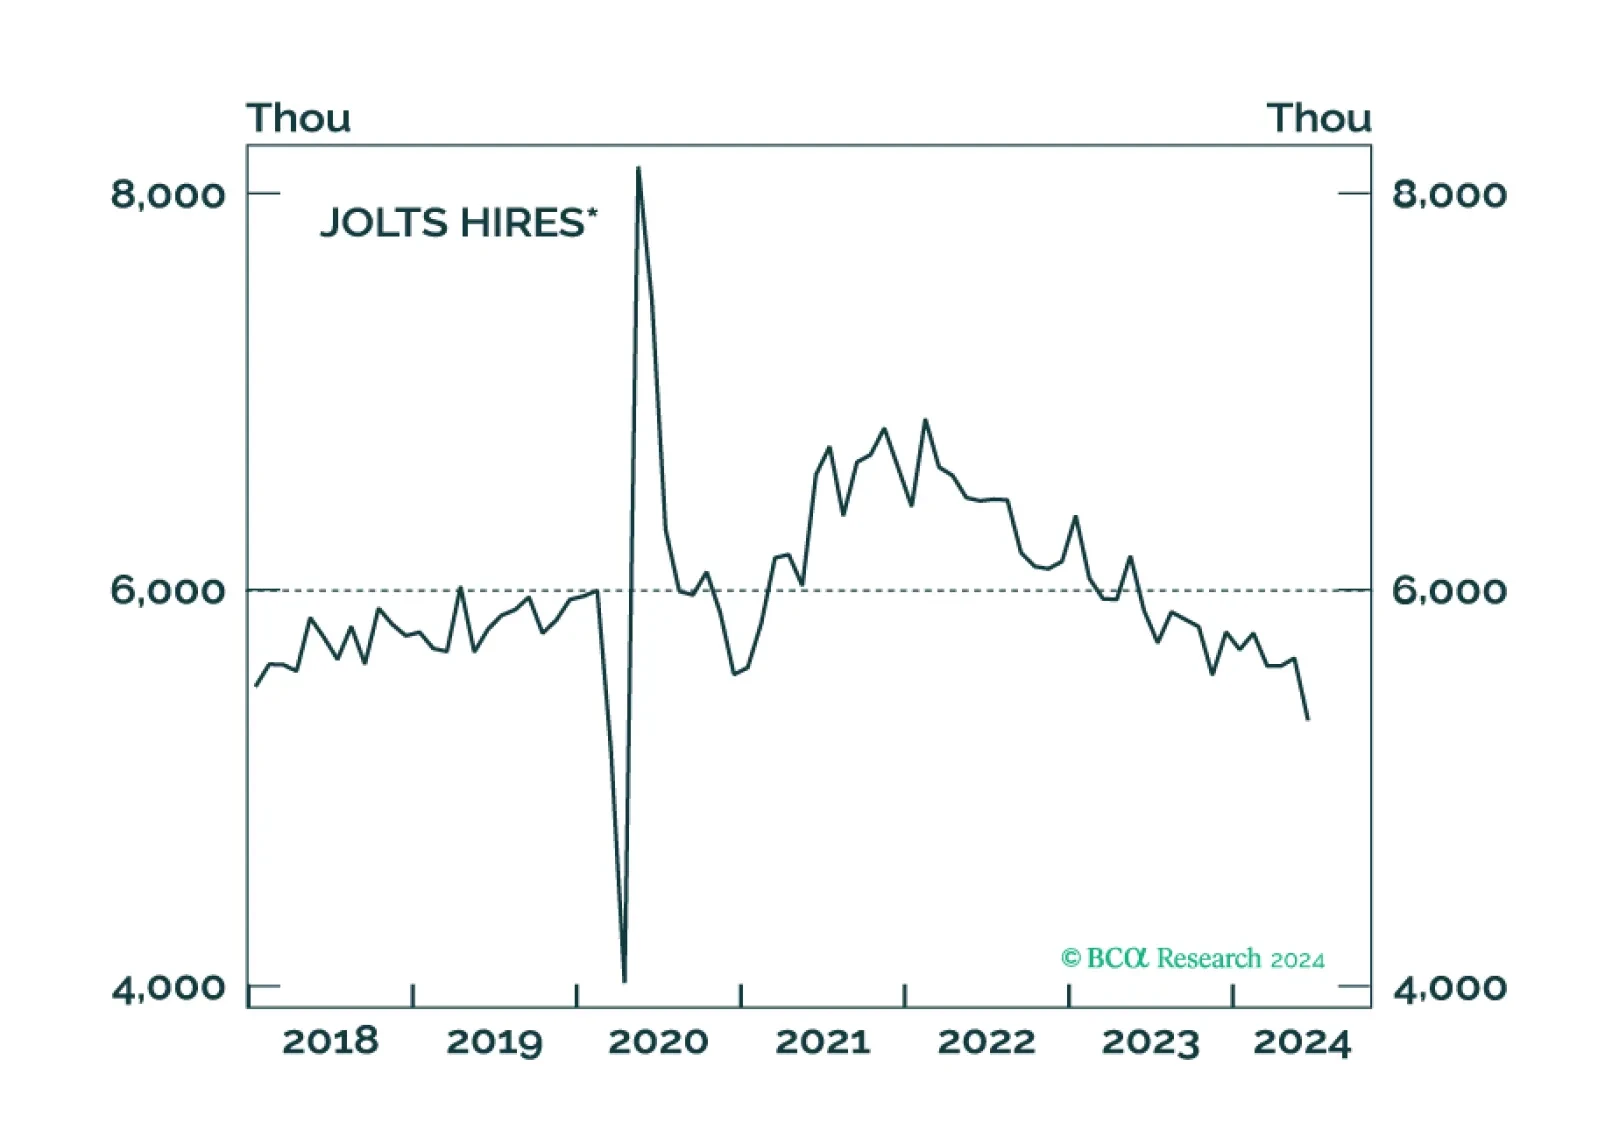
Mounting evidence that the labor market is on its way to cracking checked two more boxes on our checklist, driving us to tactically downgrade equities to underweight while upgrading fixed income to overweight. Our tactical and cyclical (6-12 months) views are now aligned as our conviction that a recession will begin before year-end has increased.
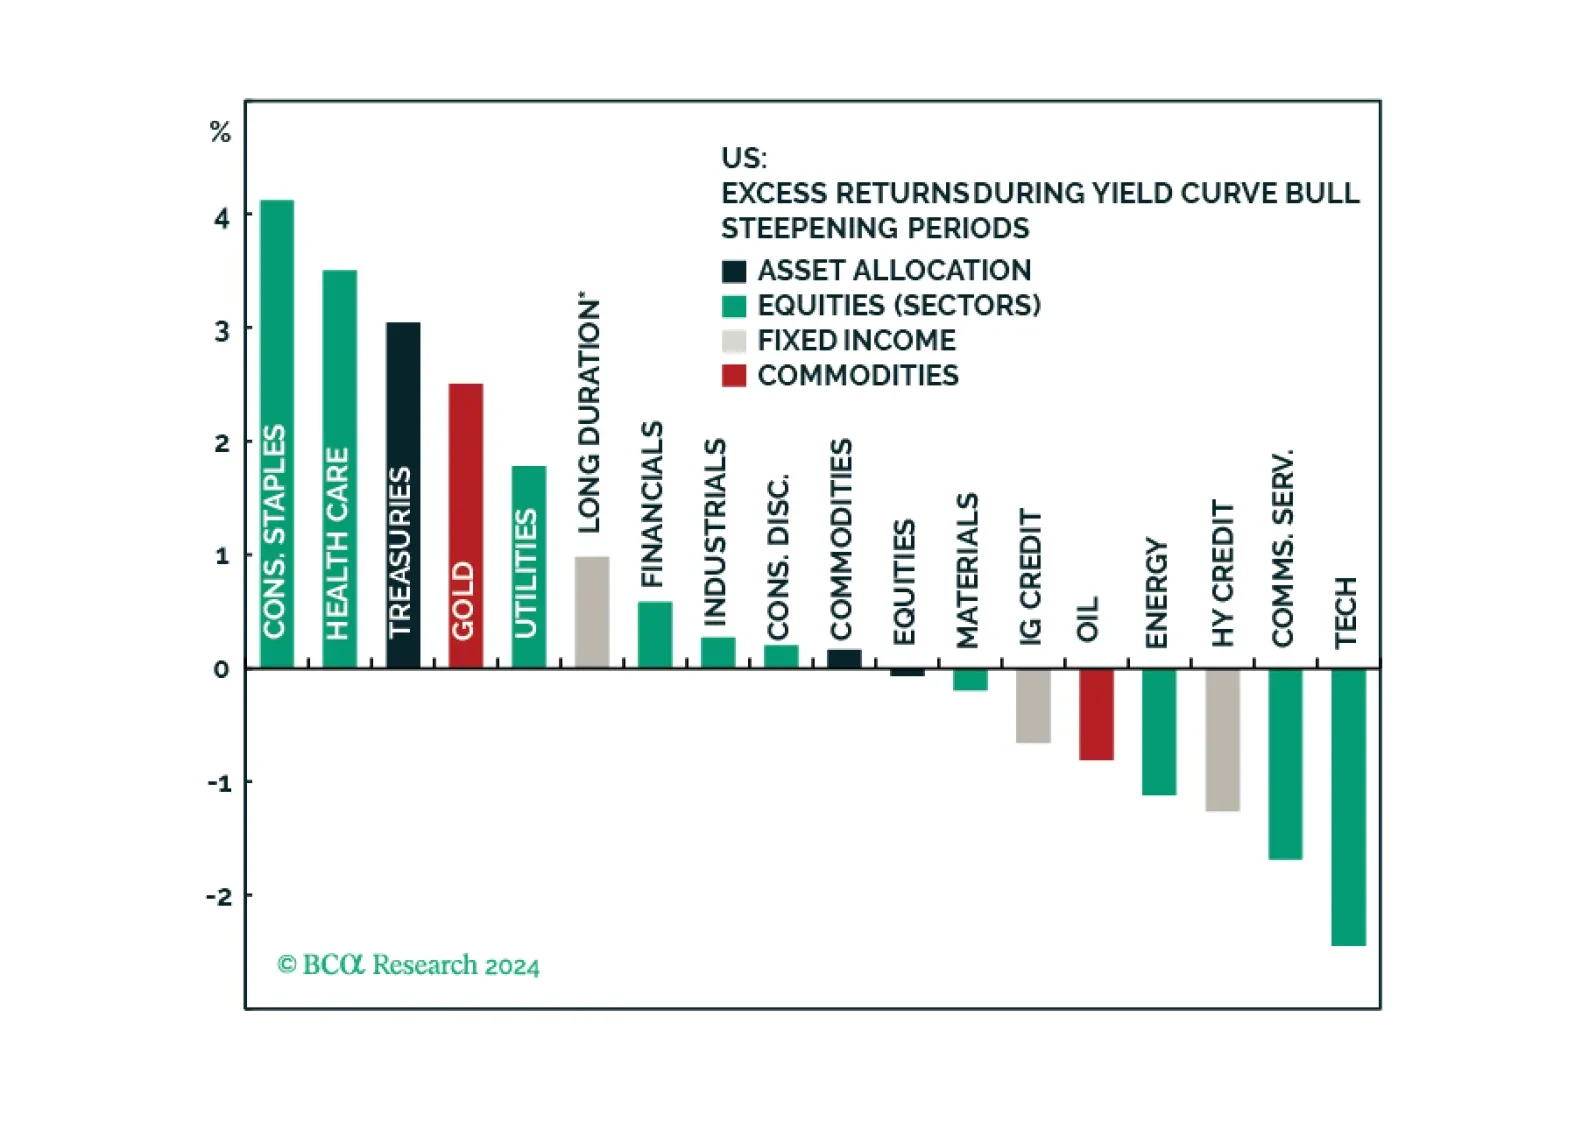
As the first Fed cut of this cycle approaches, this Strategy Insight looks at the cross-asset implications of a Treasury curve bull steepening. Investors should maintain a defensive positioning.
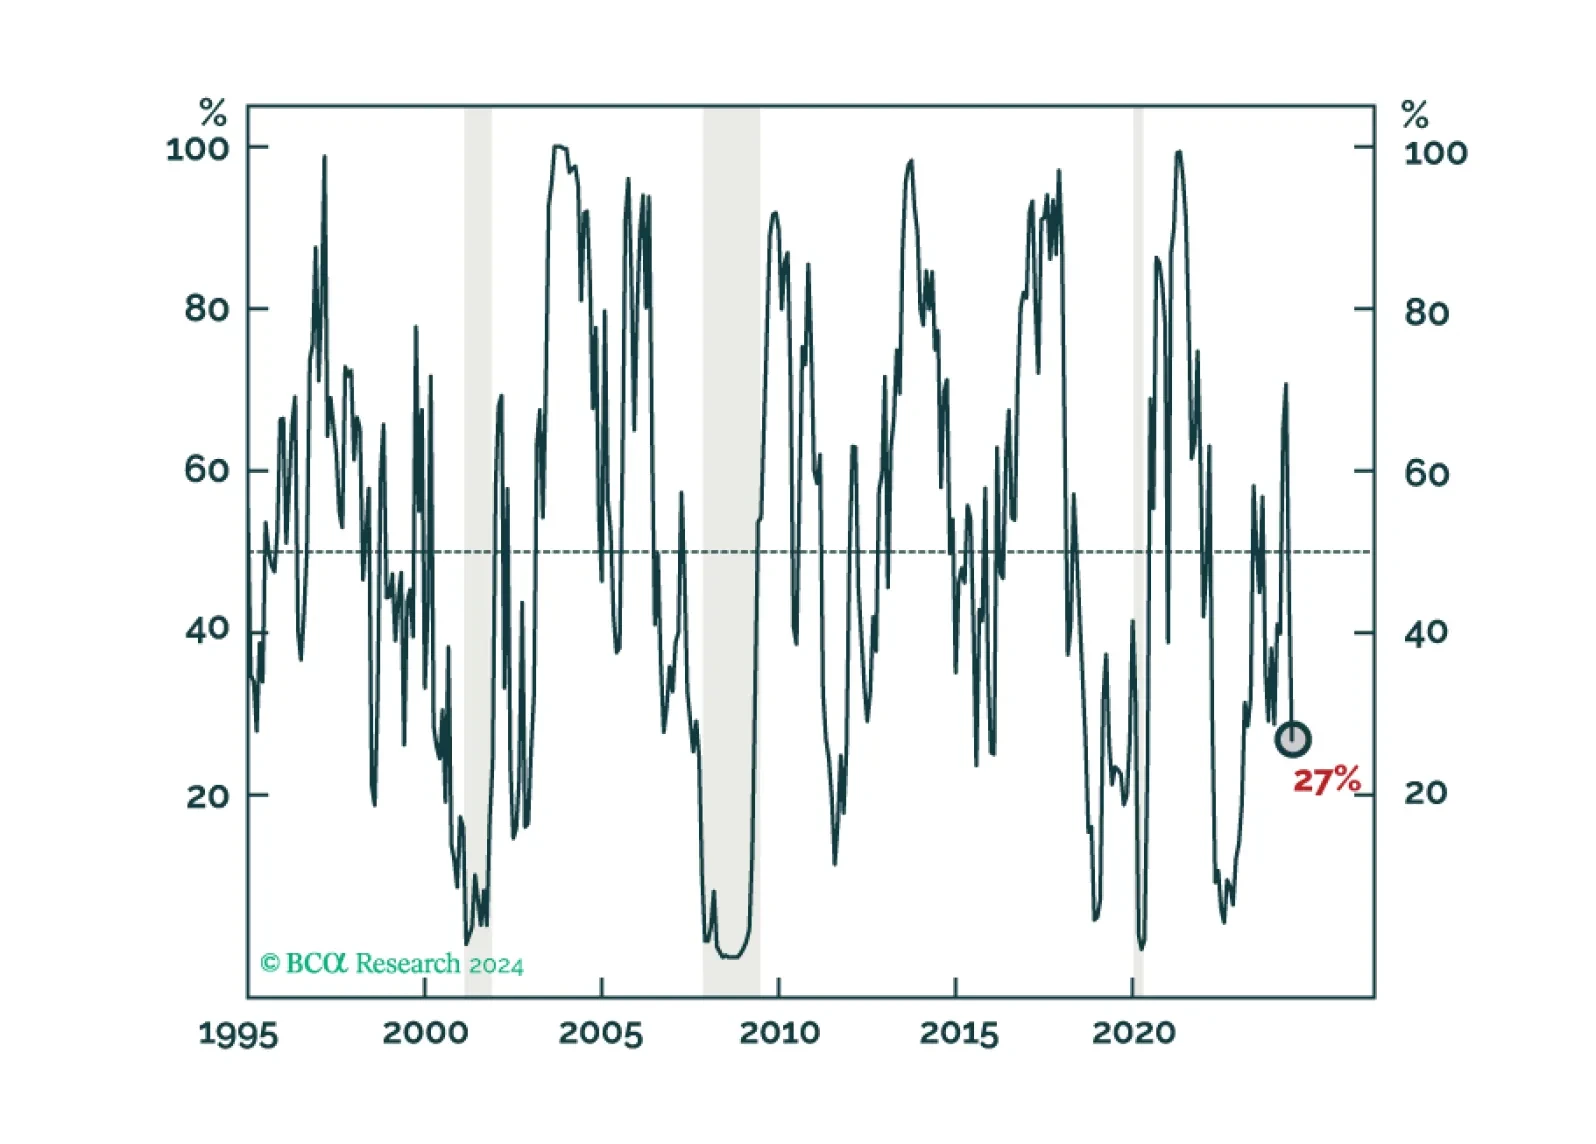
Global Equity Score turns bearish, while Global Bond Score remains neutral. Sector Model upgrades Health Care and downgrades Technology and Consumer Discretionary.