Latest from BCA Research

Our negative stance on European growth and assets is not devoid of risks. To gauge whether these risks warrant upgrading our growth outlook, we monitor Sweden closely. So, what is the current message from this Nordic economy?
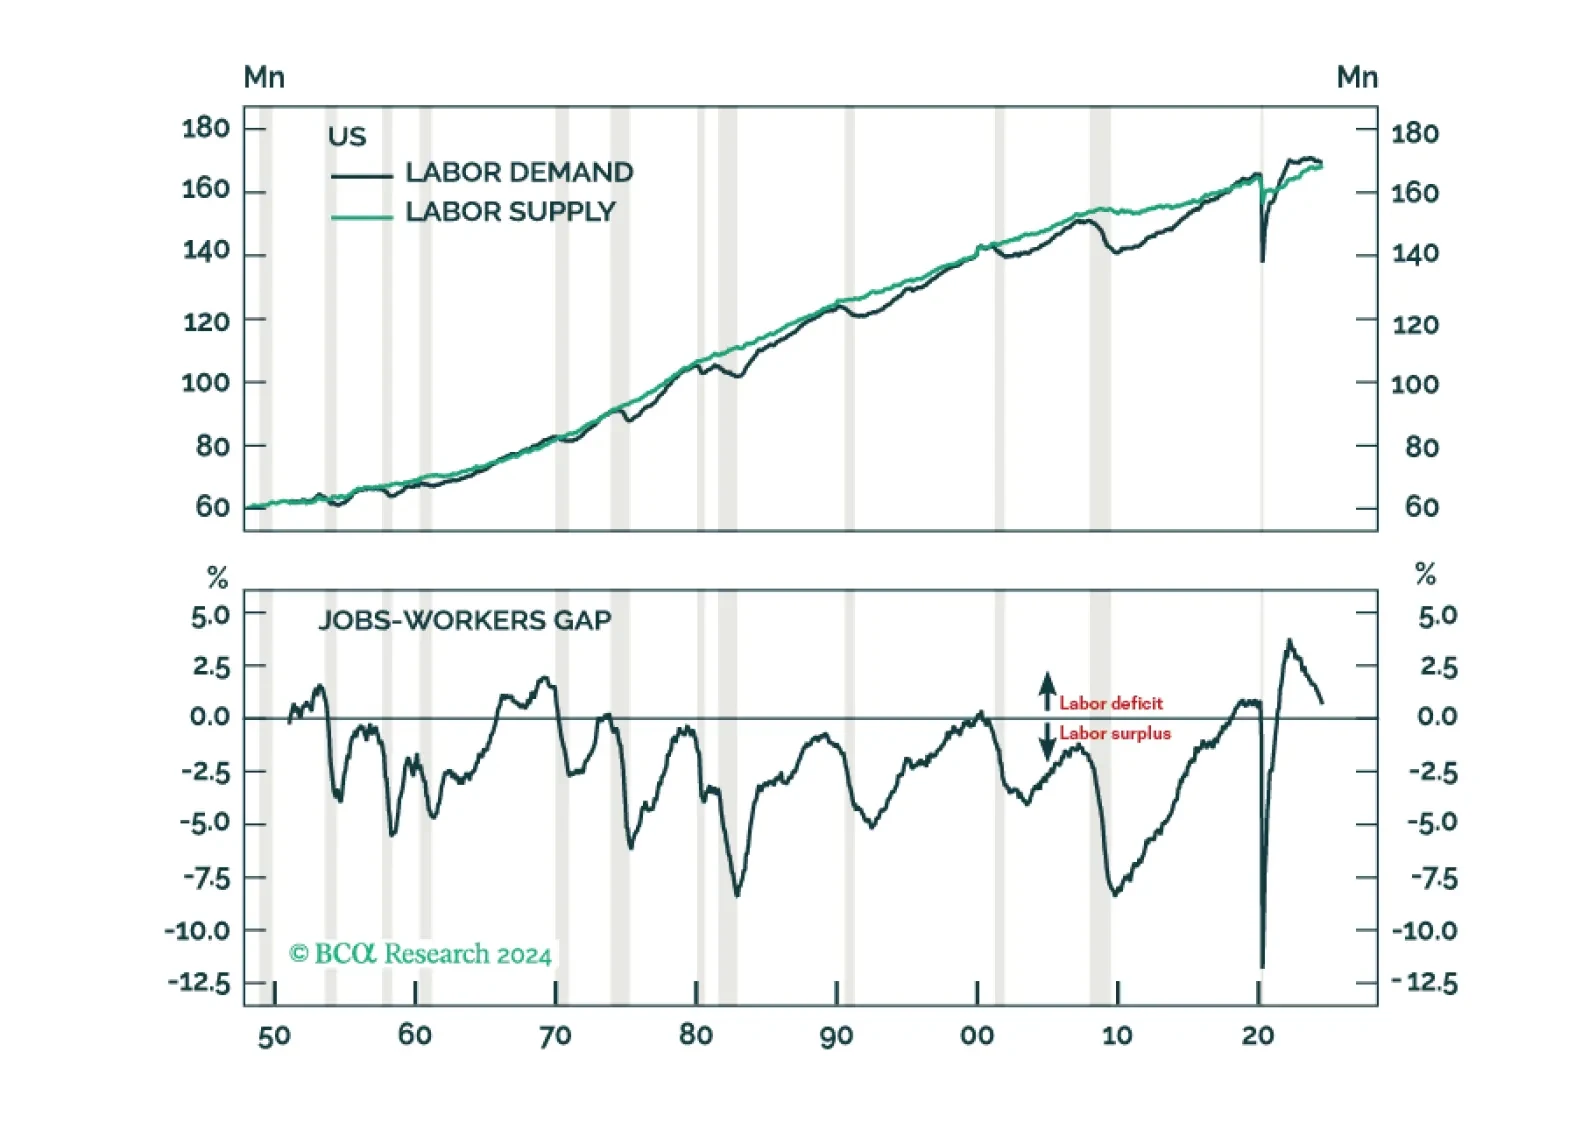
The great US labor market shortage is over. Labor demand will likely fall short of supply by the end of this year, causing unemployment to soar. Neither fiscal nor monetary policy will be able to prevent the coming recession. Investors should underweight stocks and overweight Treasuries.

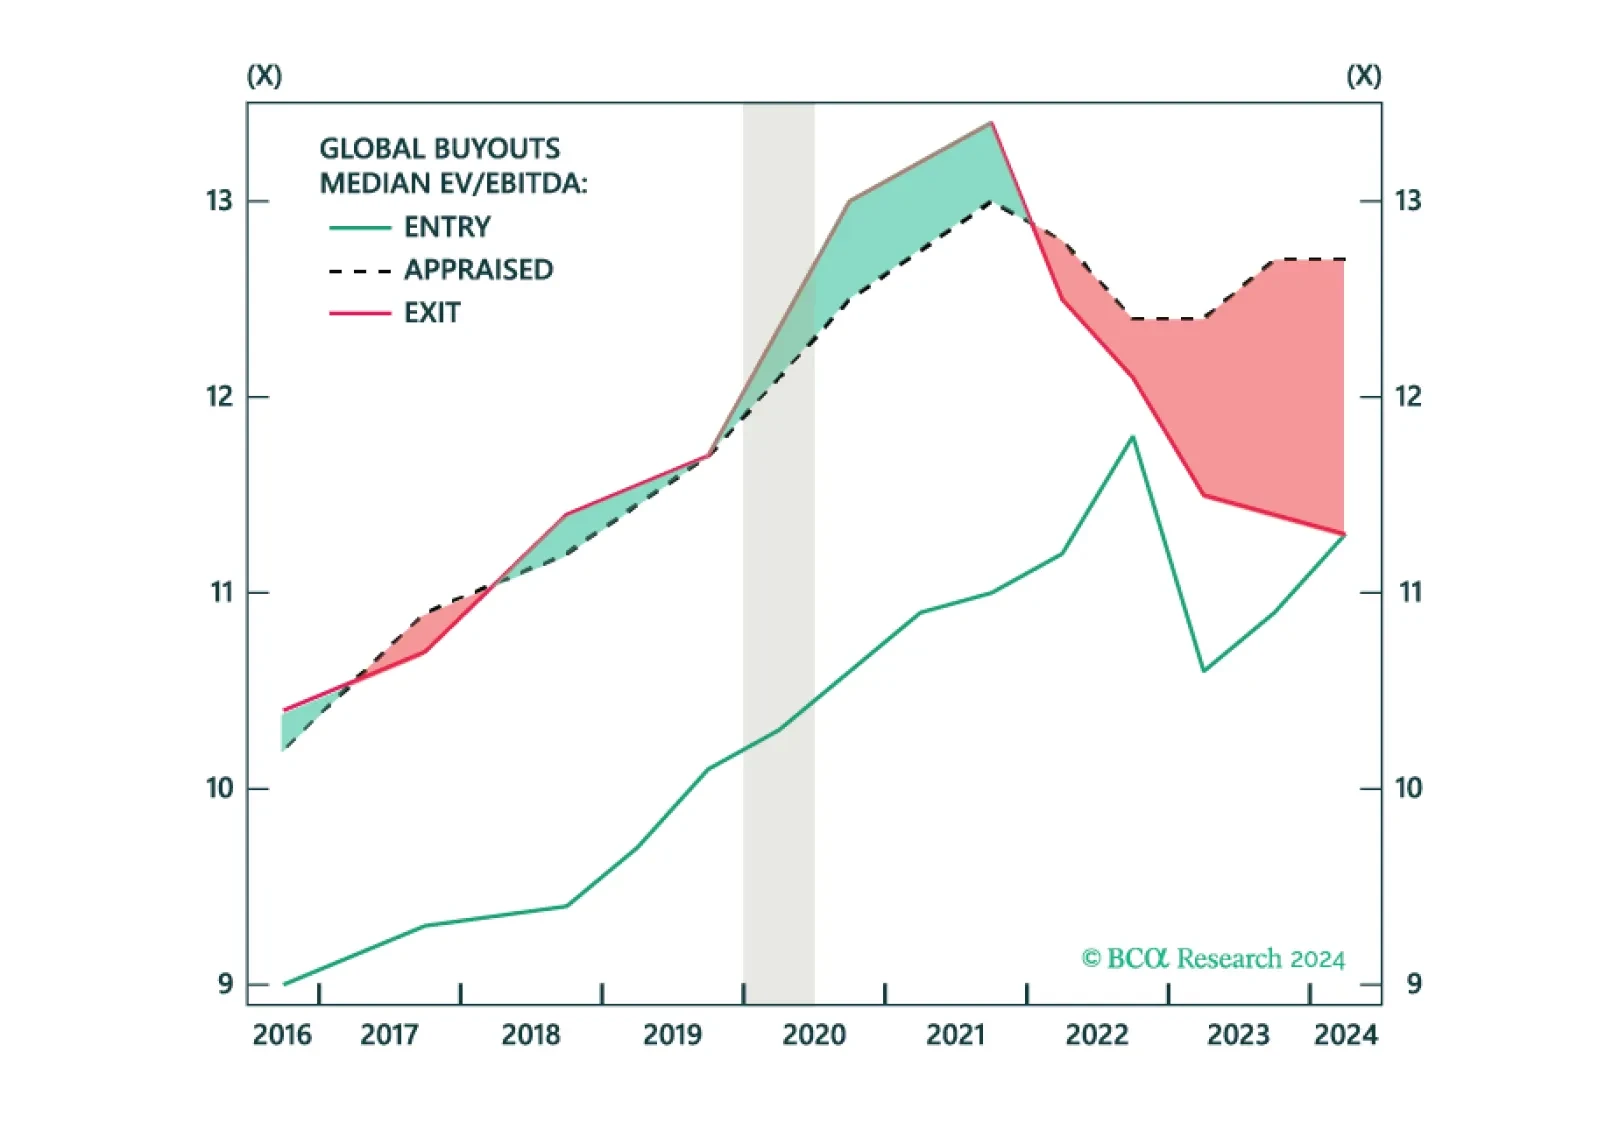
Private Equity Secondaries have grown but so have their opportunities. Near-term opportunities will be fertile while underlying trends will sustain the asset class in the long-term. Private Equity investors should be greedy.
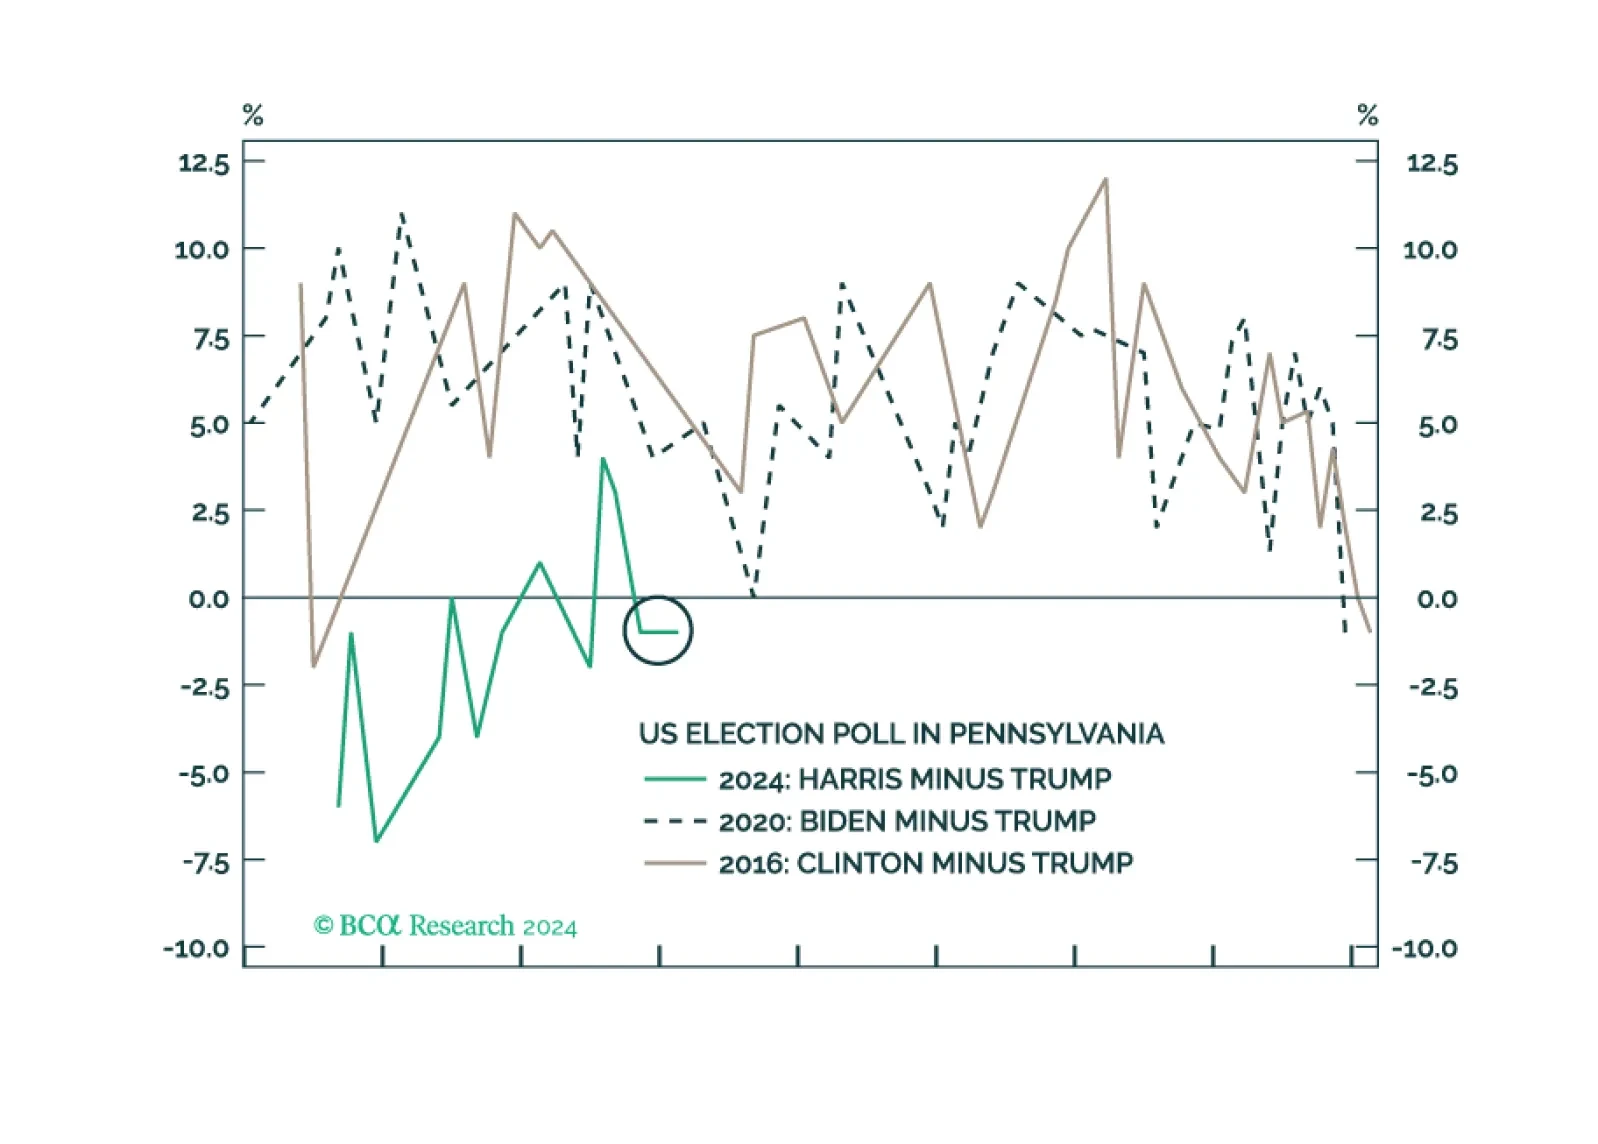
Investors should buy protection against further volatility. The shakeup in early August was a taste of things to come. The US election is a pivotal moment in modern history that will drive up uncertainty, while other countries take advantage of US division and distraction.

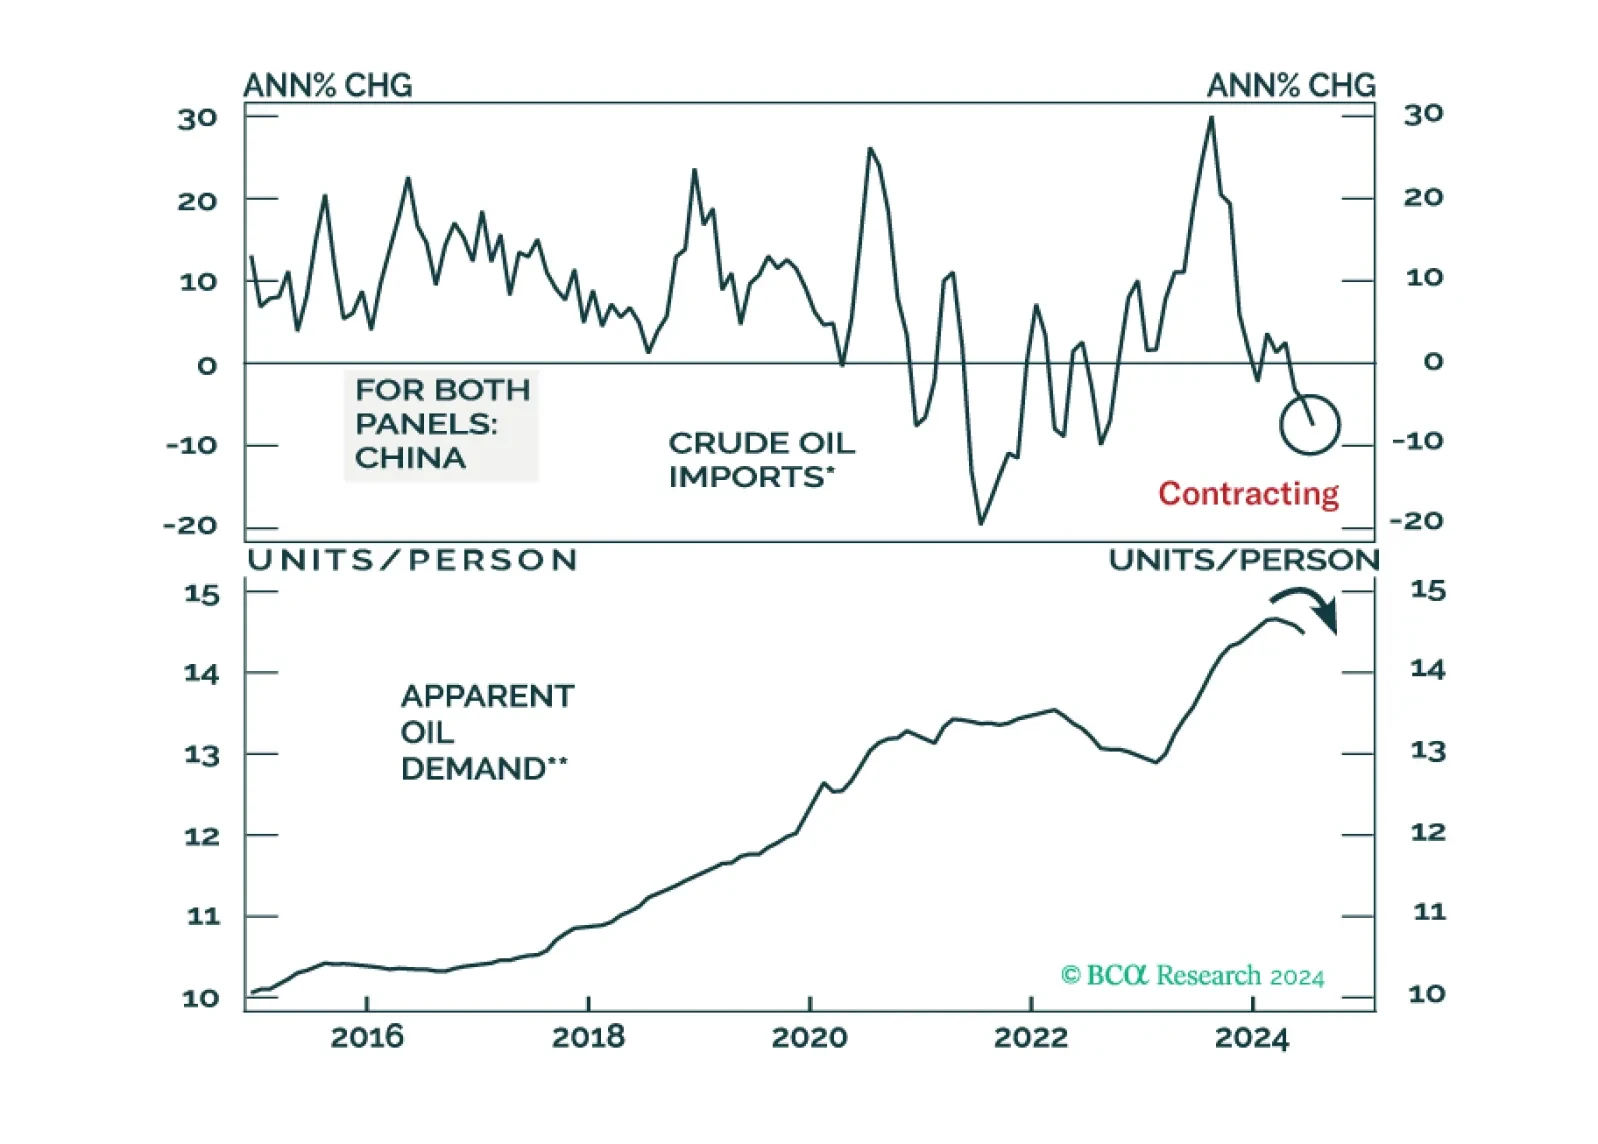
Oil prices are caught in a tug-of-war. Concerns about the demand outlook are acting as a price ceiling while the risk of a geopolitically induced supply shock is providing a floor. Prices are likely to remain rangebound over the near term. Yet the path of least resistance over a 6-to-12-month horizon is to the downside.
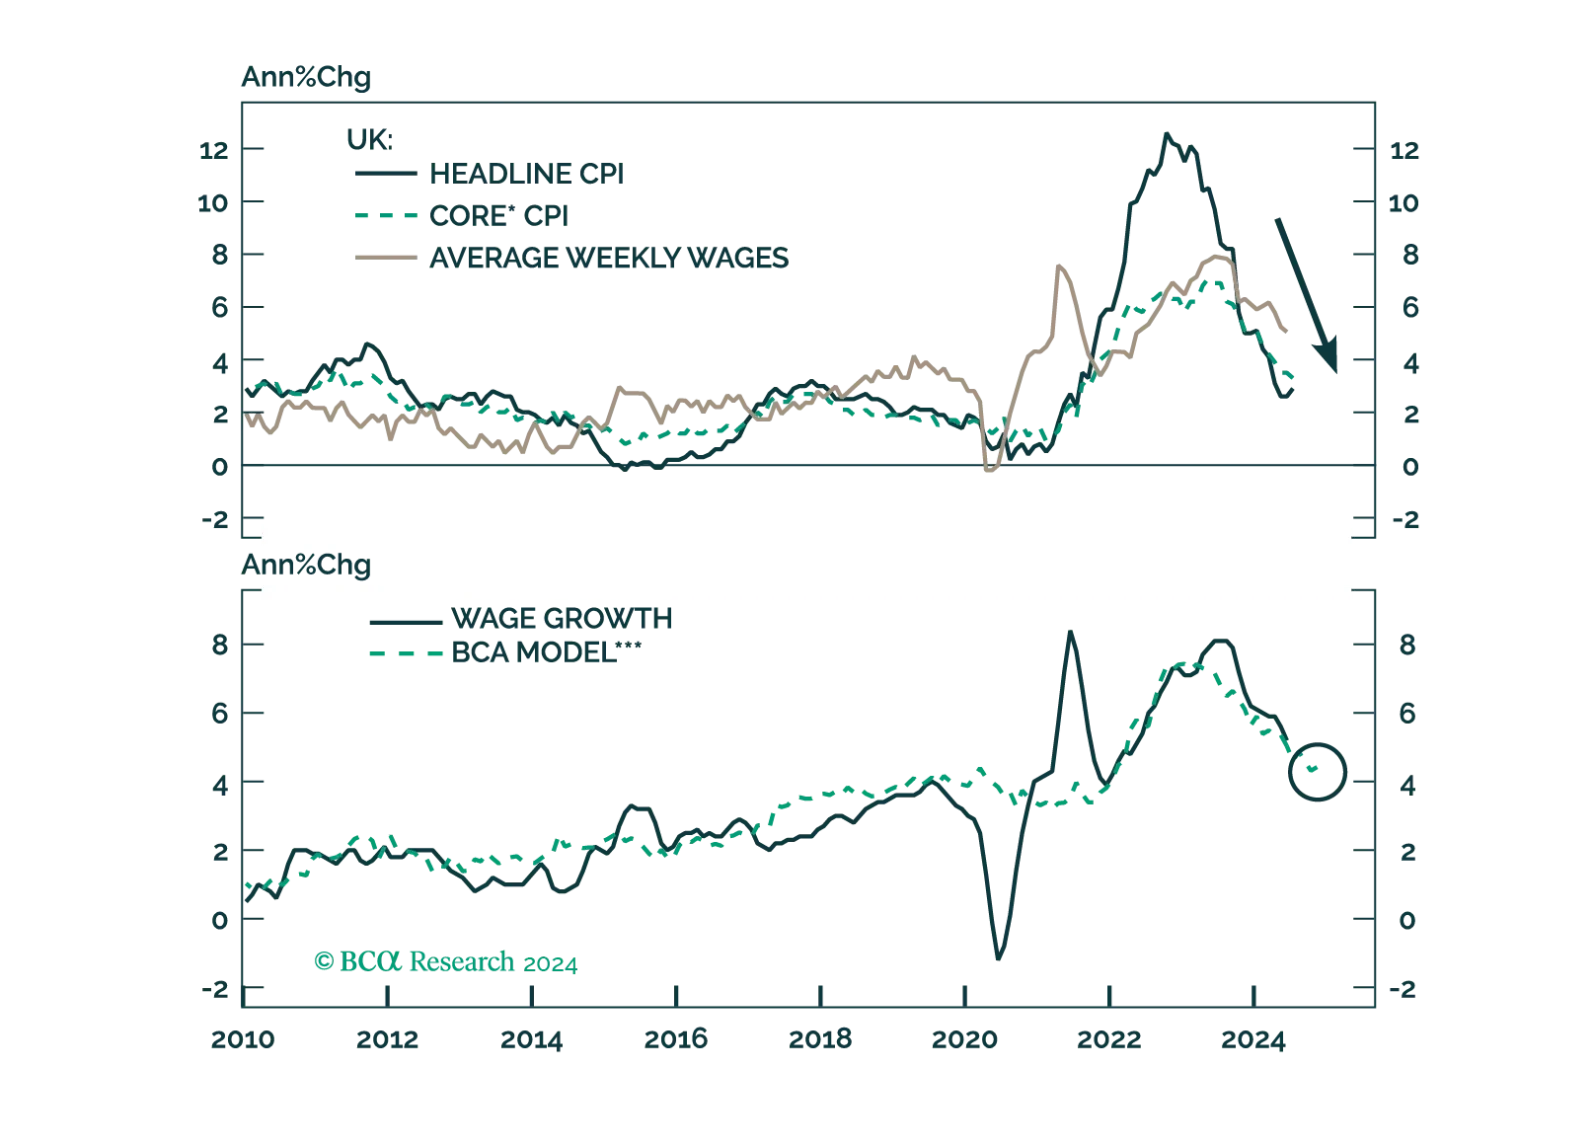
What do the mixed signals sent by the UK economy mean for the Bank of England, and what are the implications for Gilts and the British pound?