Latest from BCA Research
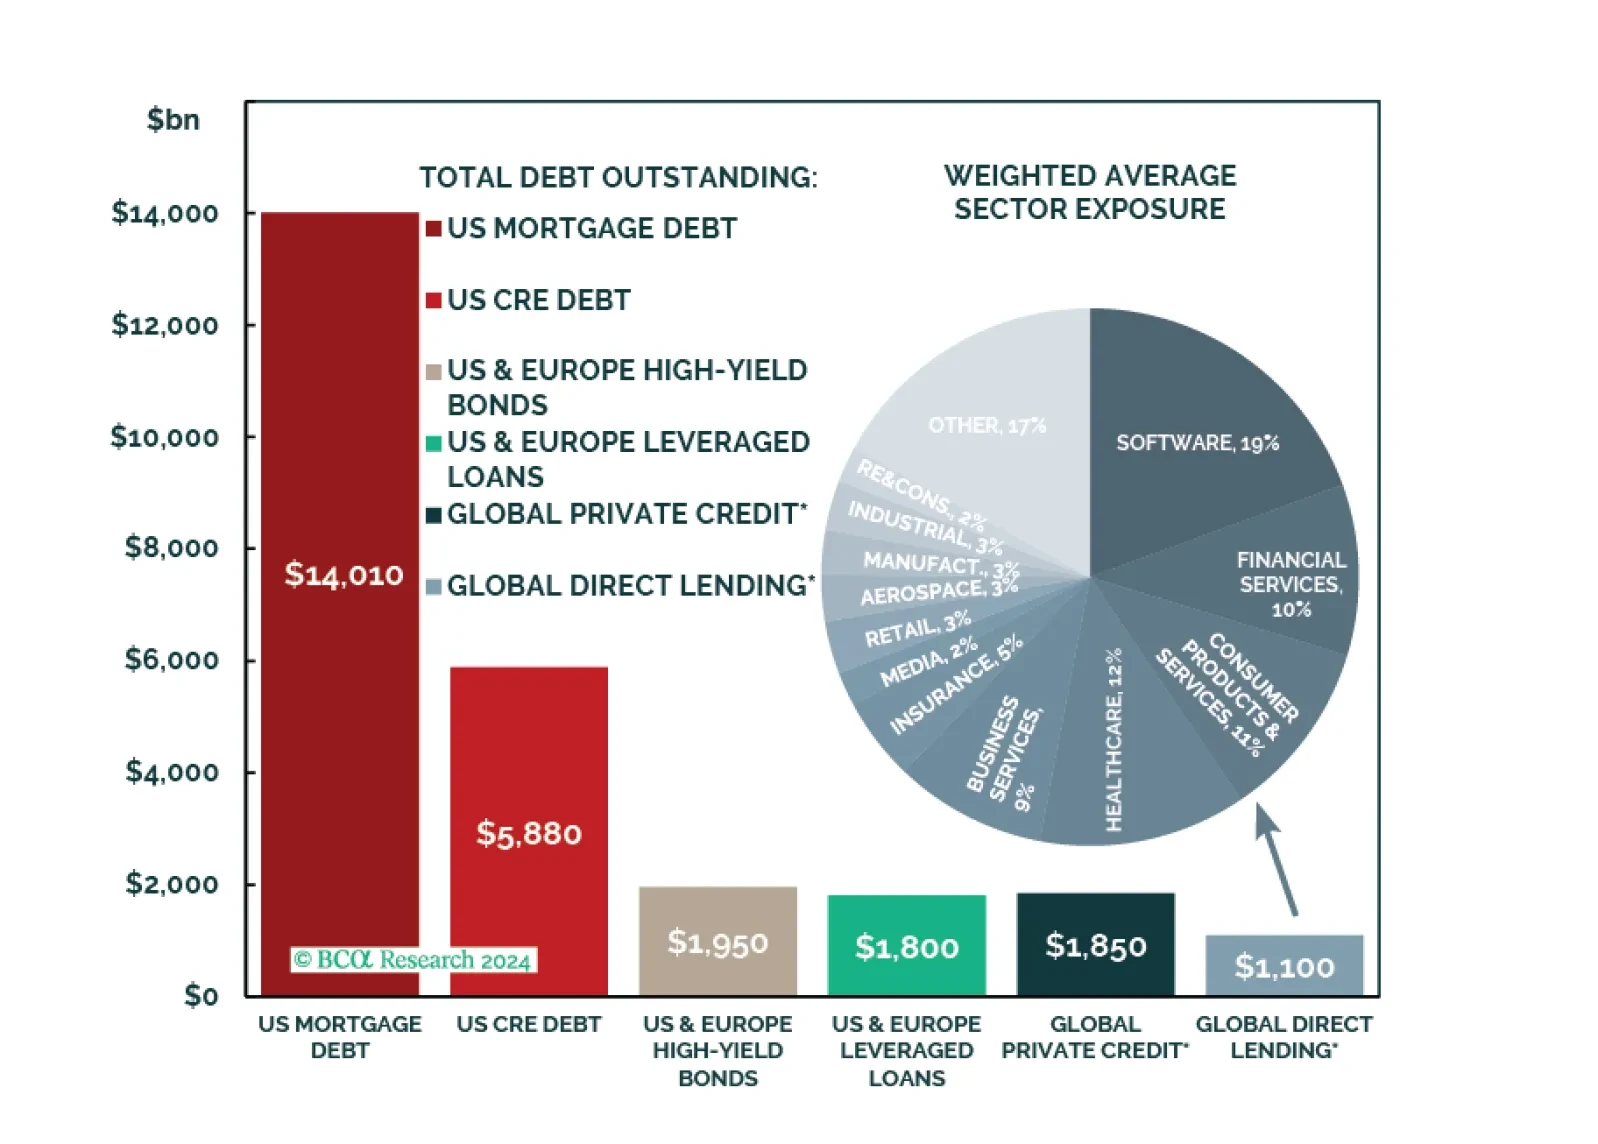
Understanding the risks across Private Credit will enable investors to be offensive, not just with sizing but across their total portfolio. Senior Direct Lending is not risk-free, Private Credit is not systemic, and a liquidity crisis will not be born in this asset class.

A confluence of both supply and demand factors contributed to the natural gas rally over the past few months. This trend could continue for a while longer. However, cyclical and structural factors ultimately argue against a sustained increase in prices.
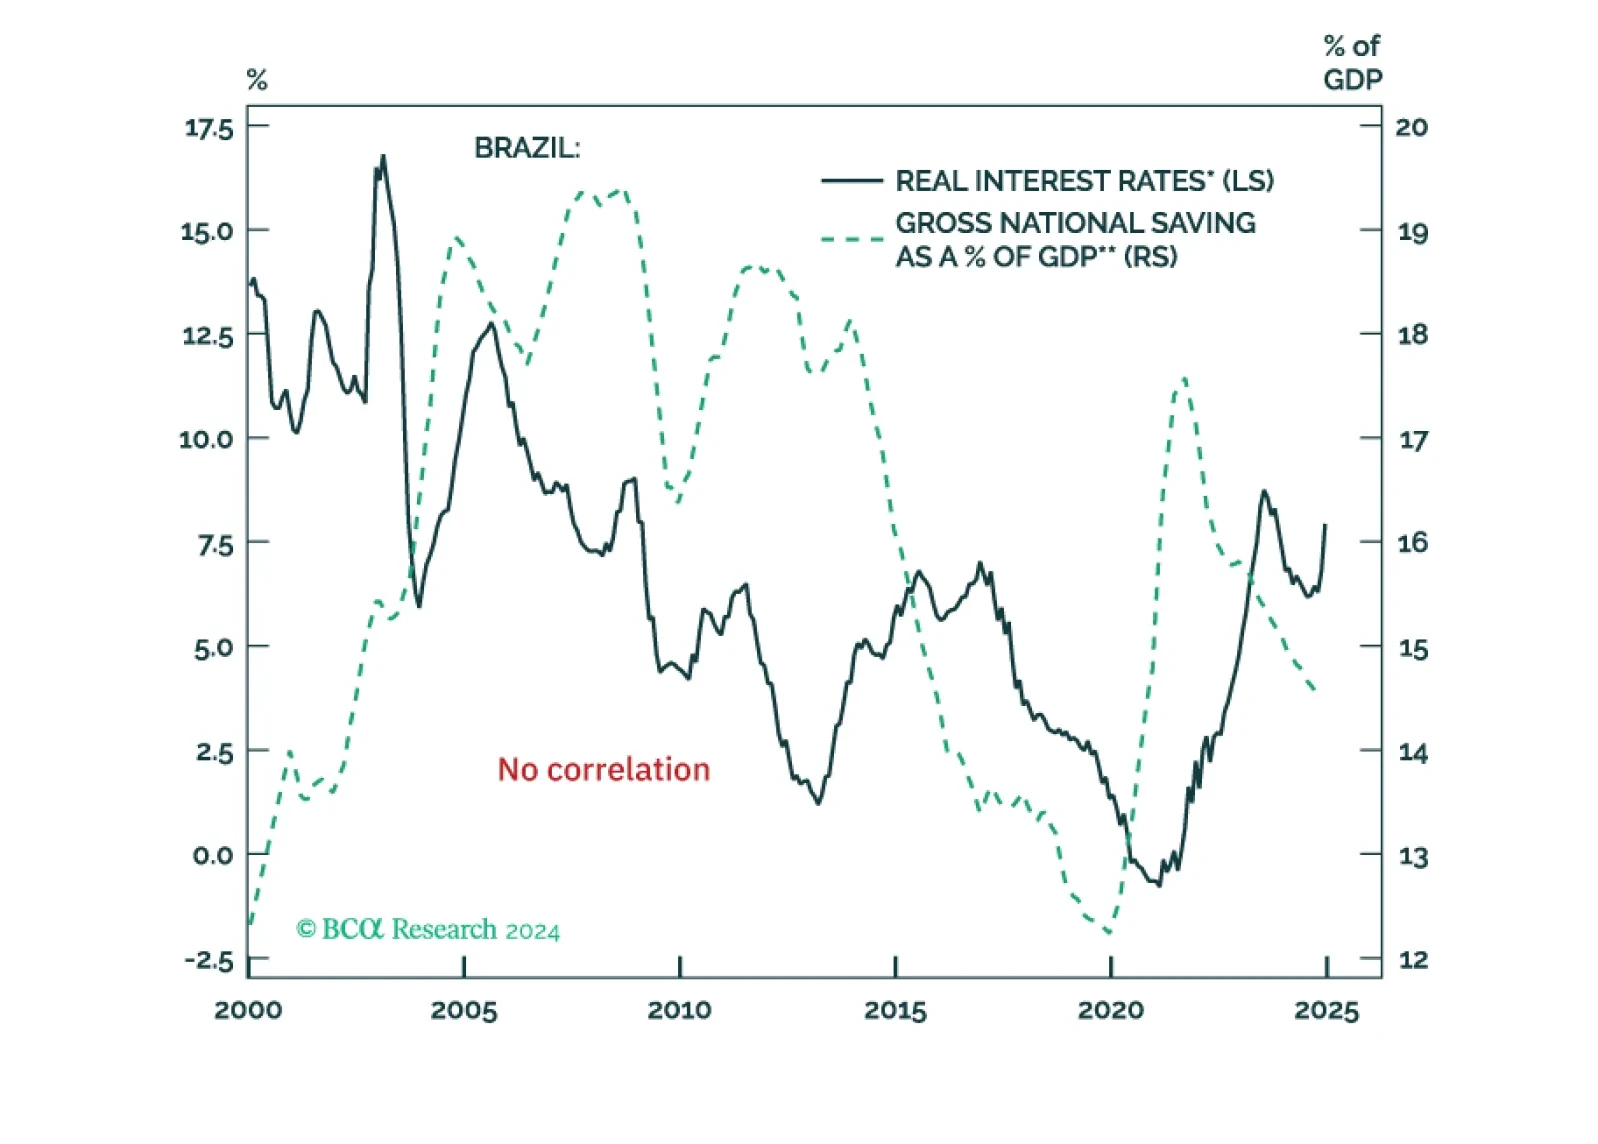
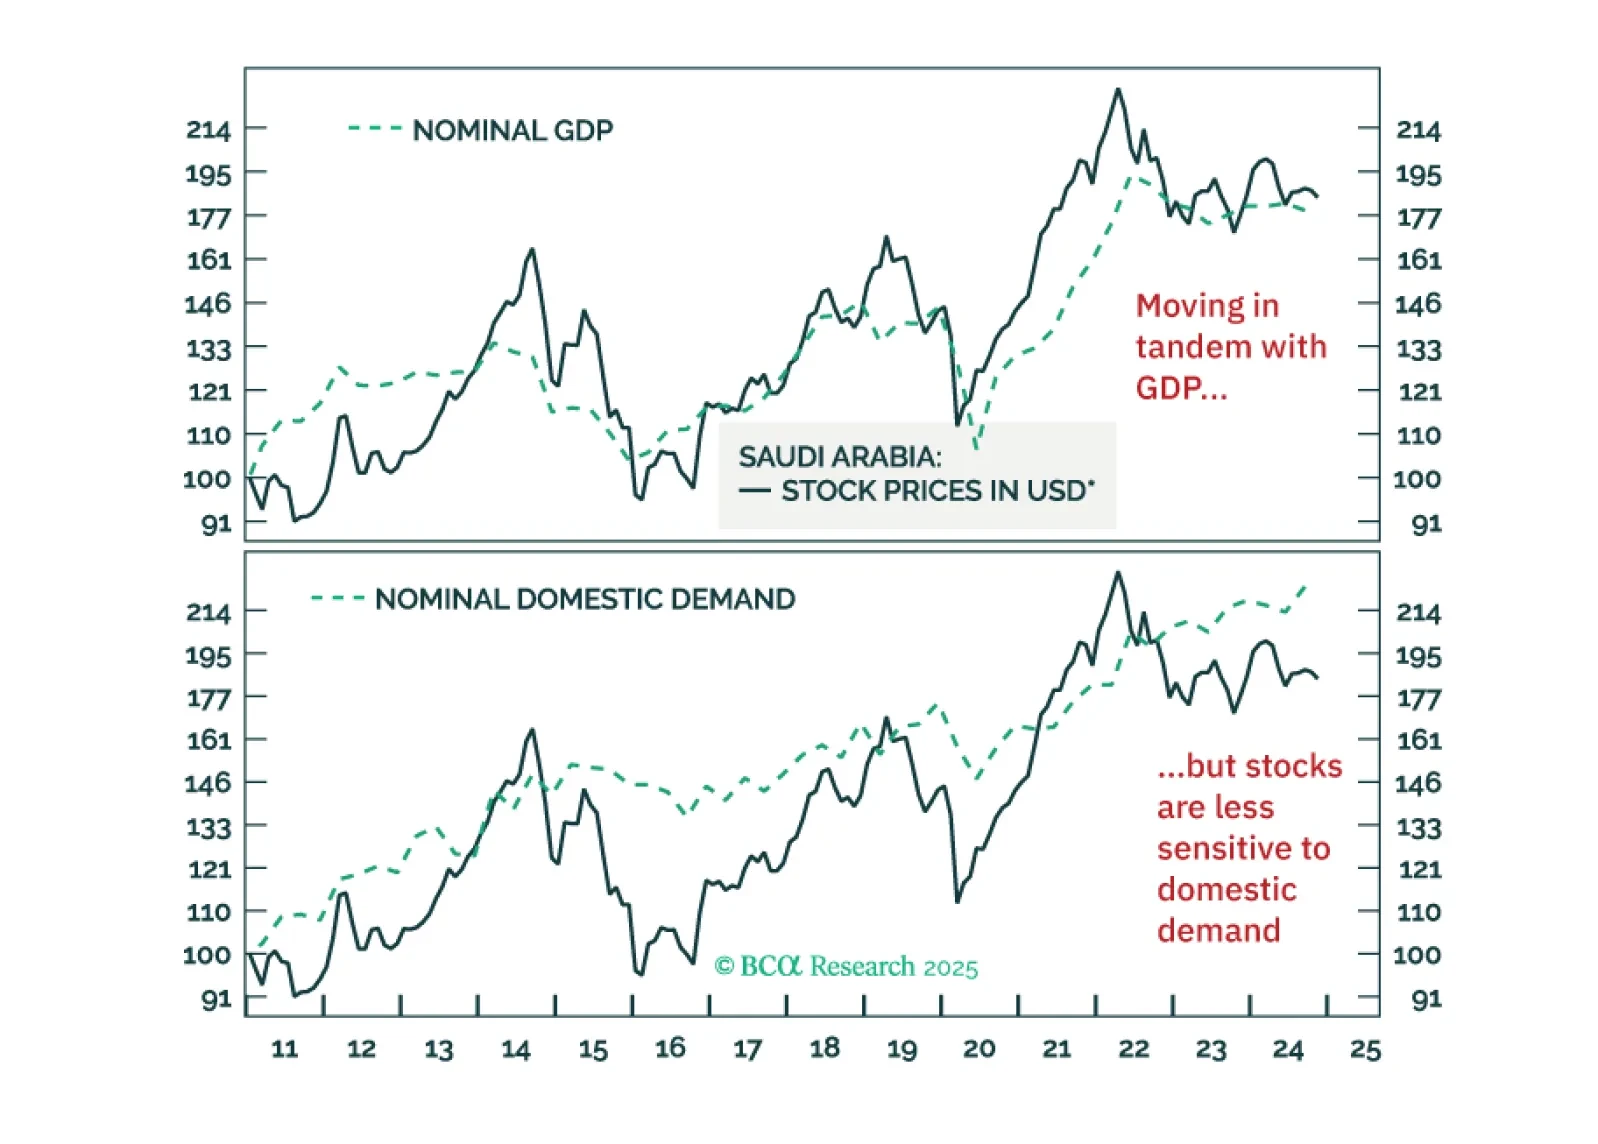
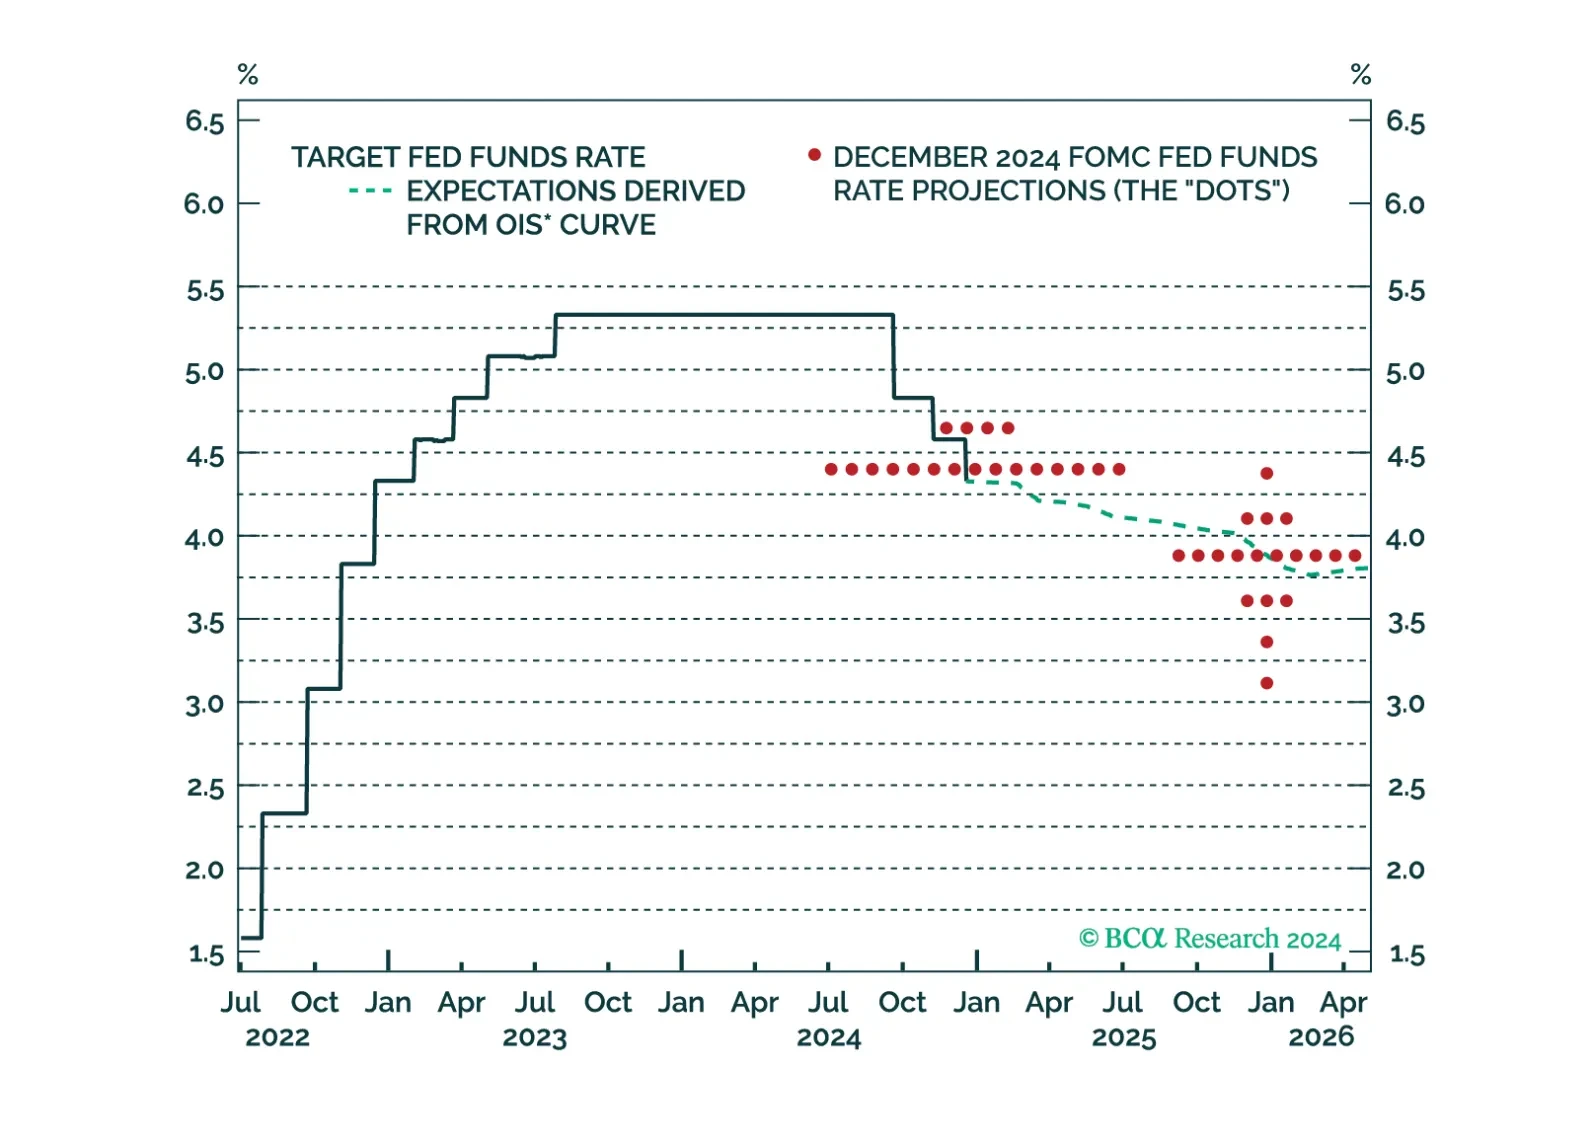
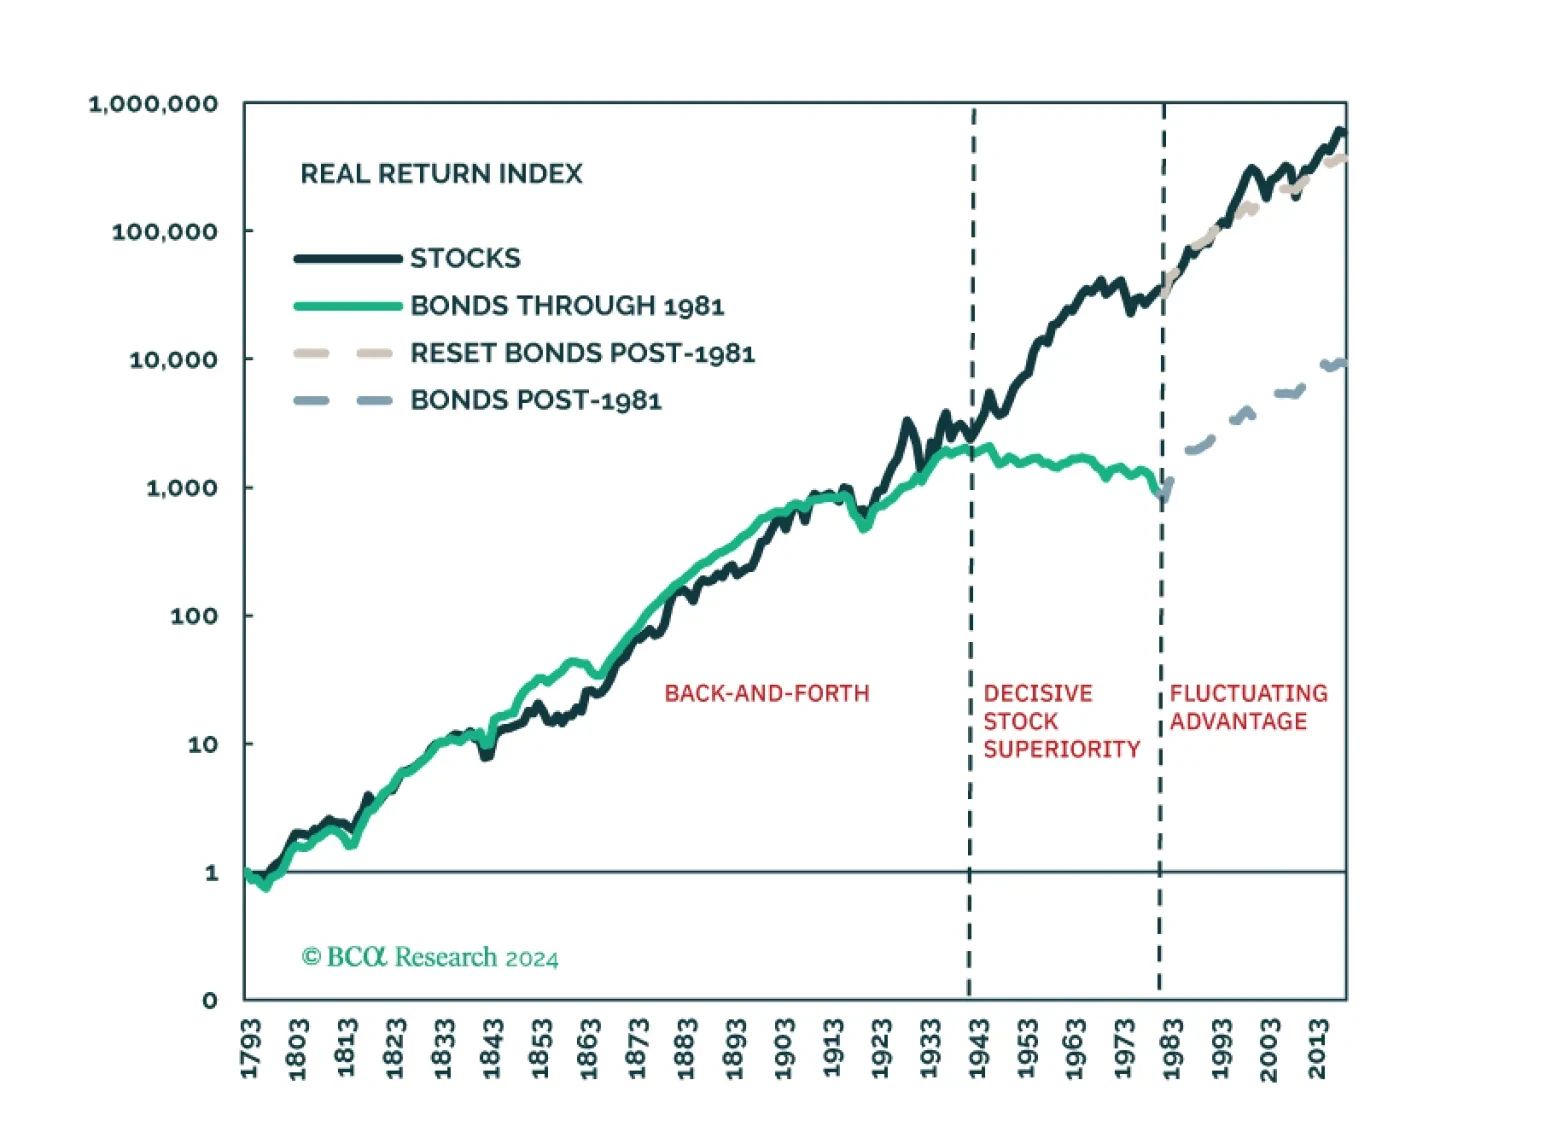
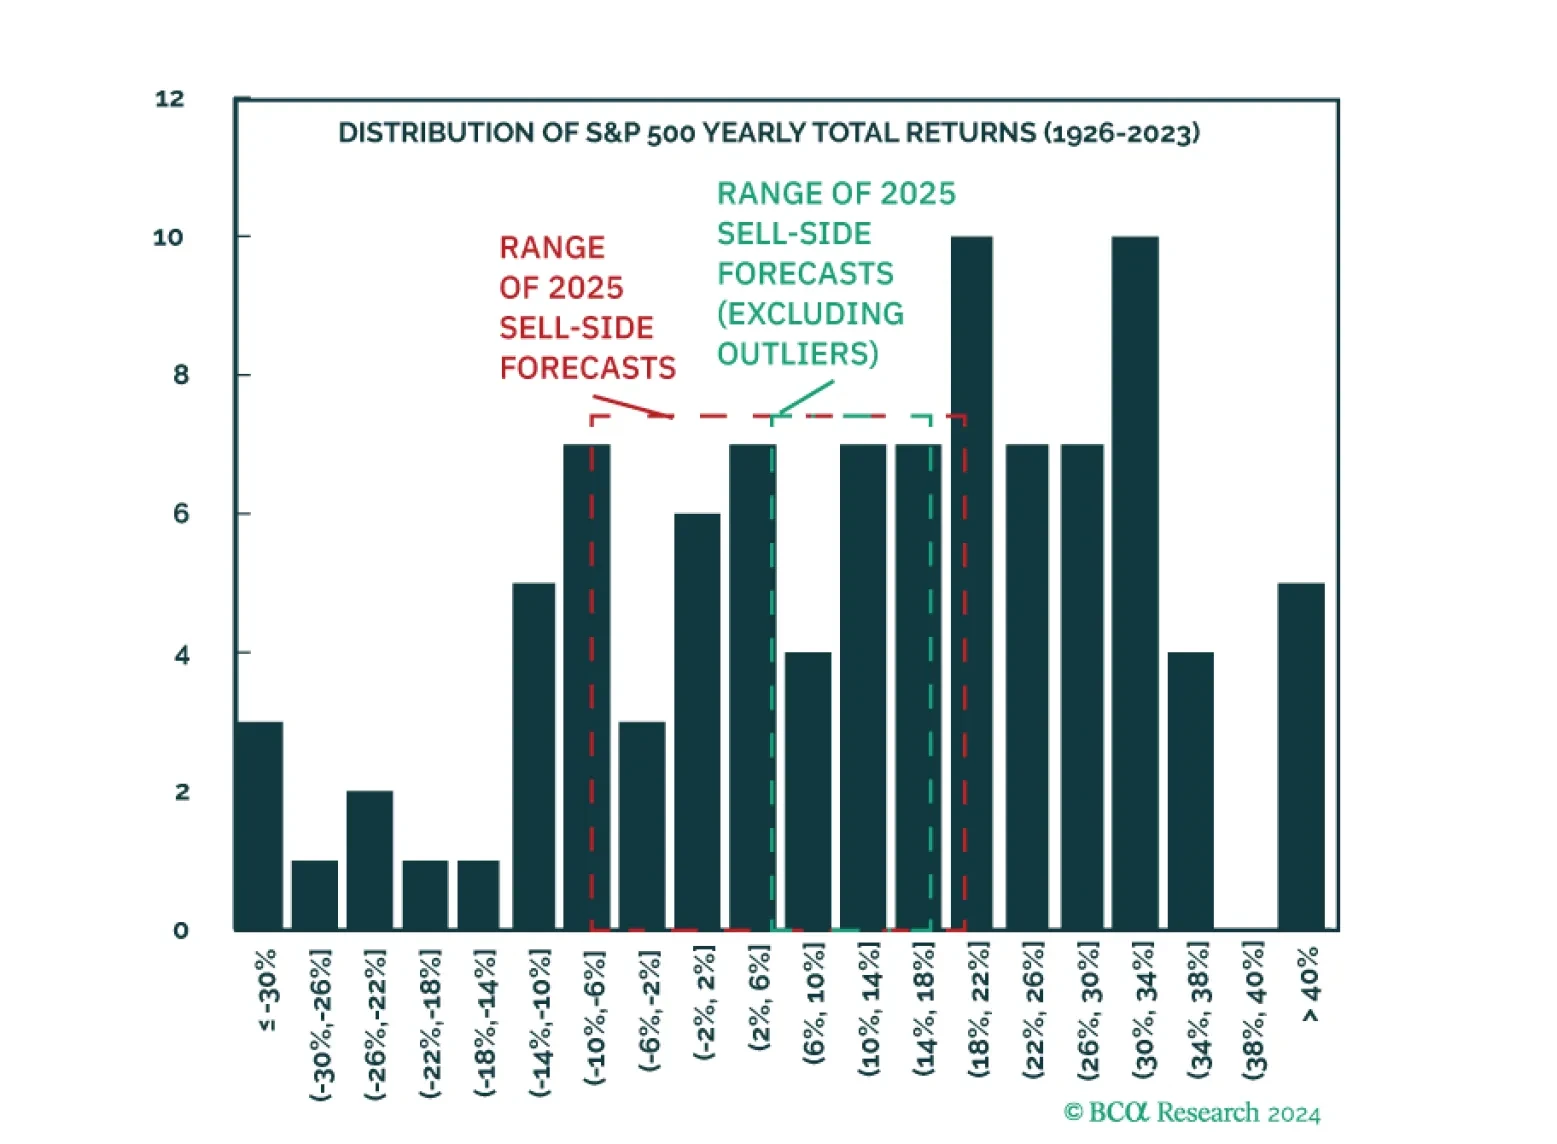
The range of forecast for the S&P 500 is too narrow. While most strategists are predicting an average year for the S&P 500, average returns do not happen often. The S&P is more likely to fall to below 5500 or rise above 7100, than to stay within the range of forecast. As a result, our negative view will either be spectacularly right or spectacularly wrong.

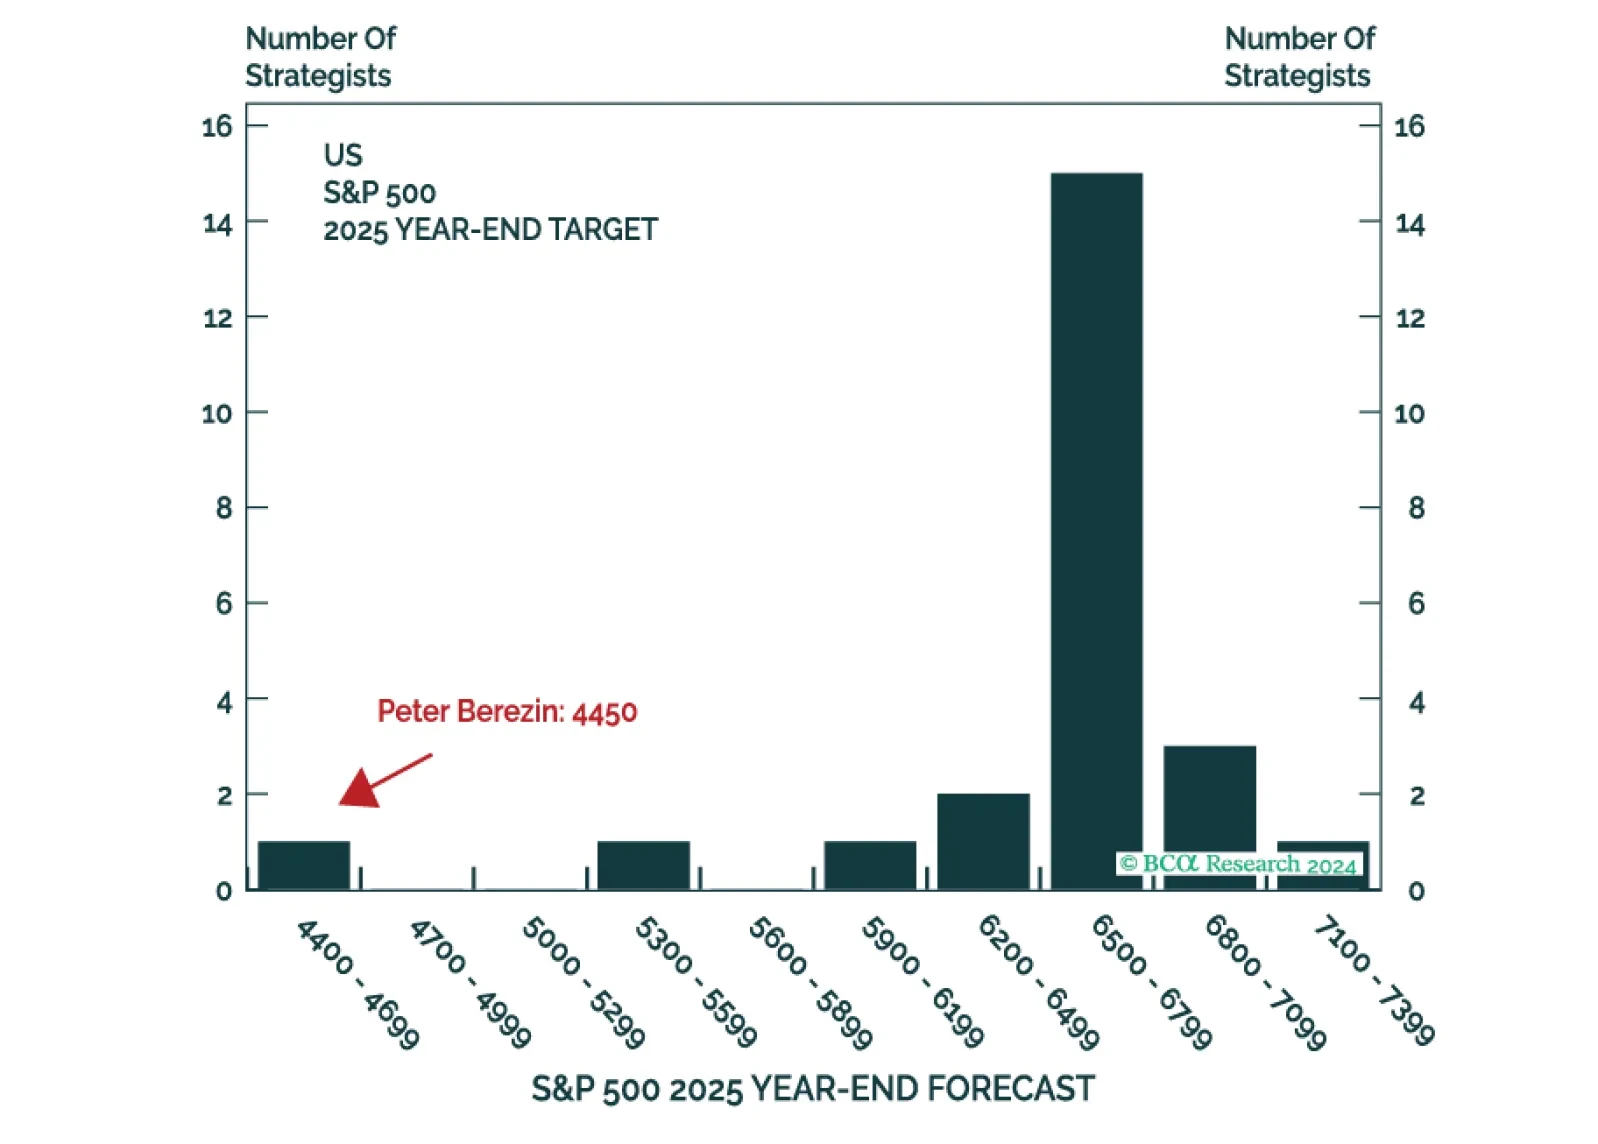
This is the time of the year when strategists are busy sending out their annual outlooks. Here on the Global Investment Strategy team, we decided to go one step further. Rather than pontificating about what could happen in 2025, we decided to harness the power of the multiverse to tell you what did happen (in at least one highly representative timeline). Next week, please join me for a Webcast on Tuesday, December 17 at 10:30 AM EST (3:30 PM GMT, 4:30 PM CET) to discuss the economy and financial markets. And with that, I will sign off for the year. I wish you and your loved ones a very happy and healthy 2025. We will be back in the first week of January with our MacroQuant Model Update.
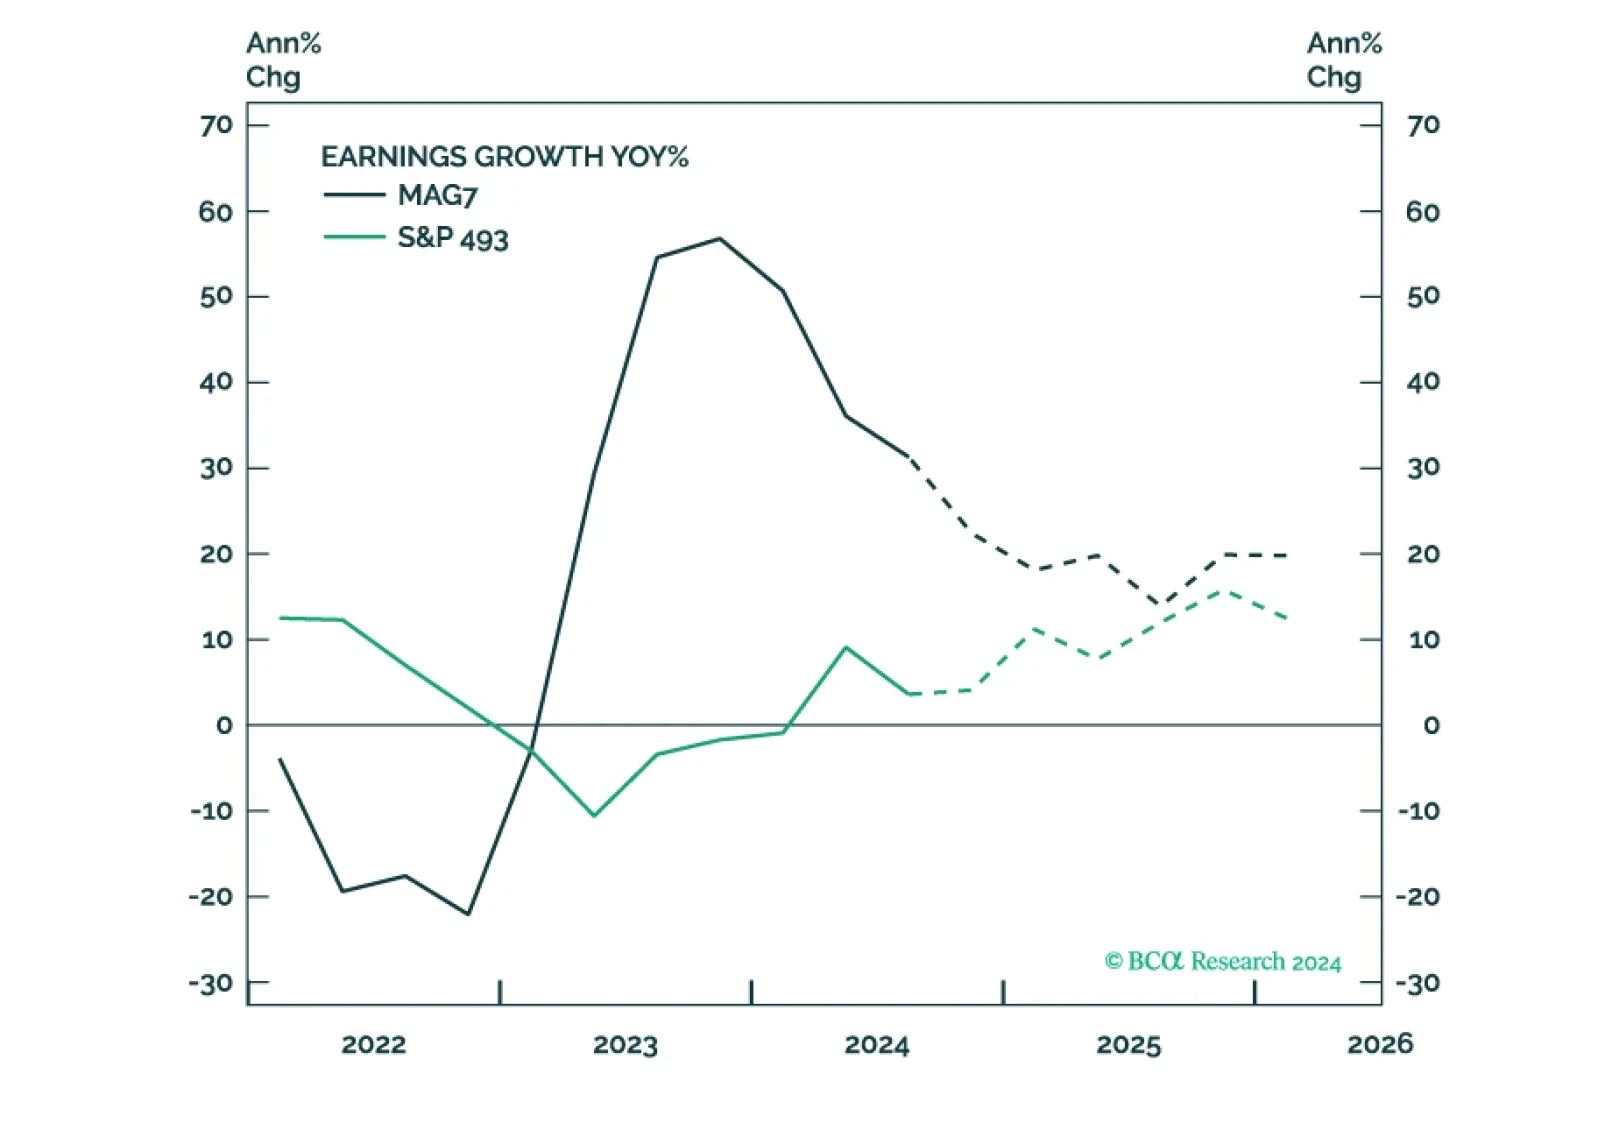
Trump's policies aim to support domestic producers and will be pro-growth and inflationary, at least initially. This environment is supportive of equities. Earnings will likely be strong, but elevated valuations make equities prone to a correction. Earnings growth broadening will translate into performance broadening – the S&P 493, Cyclicals, Value, Small and Mid are likely to outperform.