Latest from BCA Research
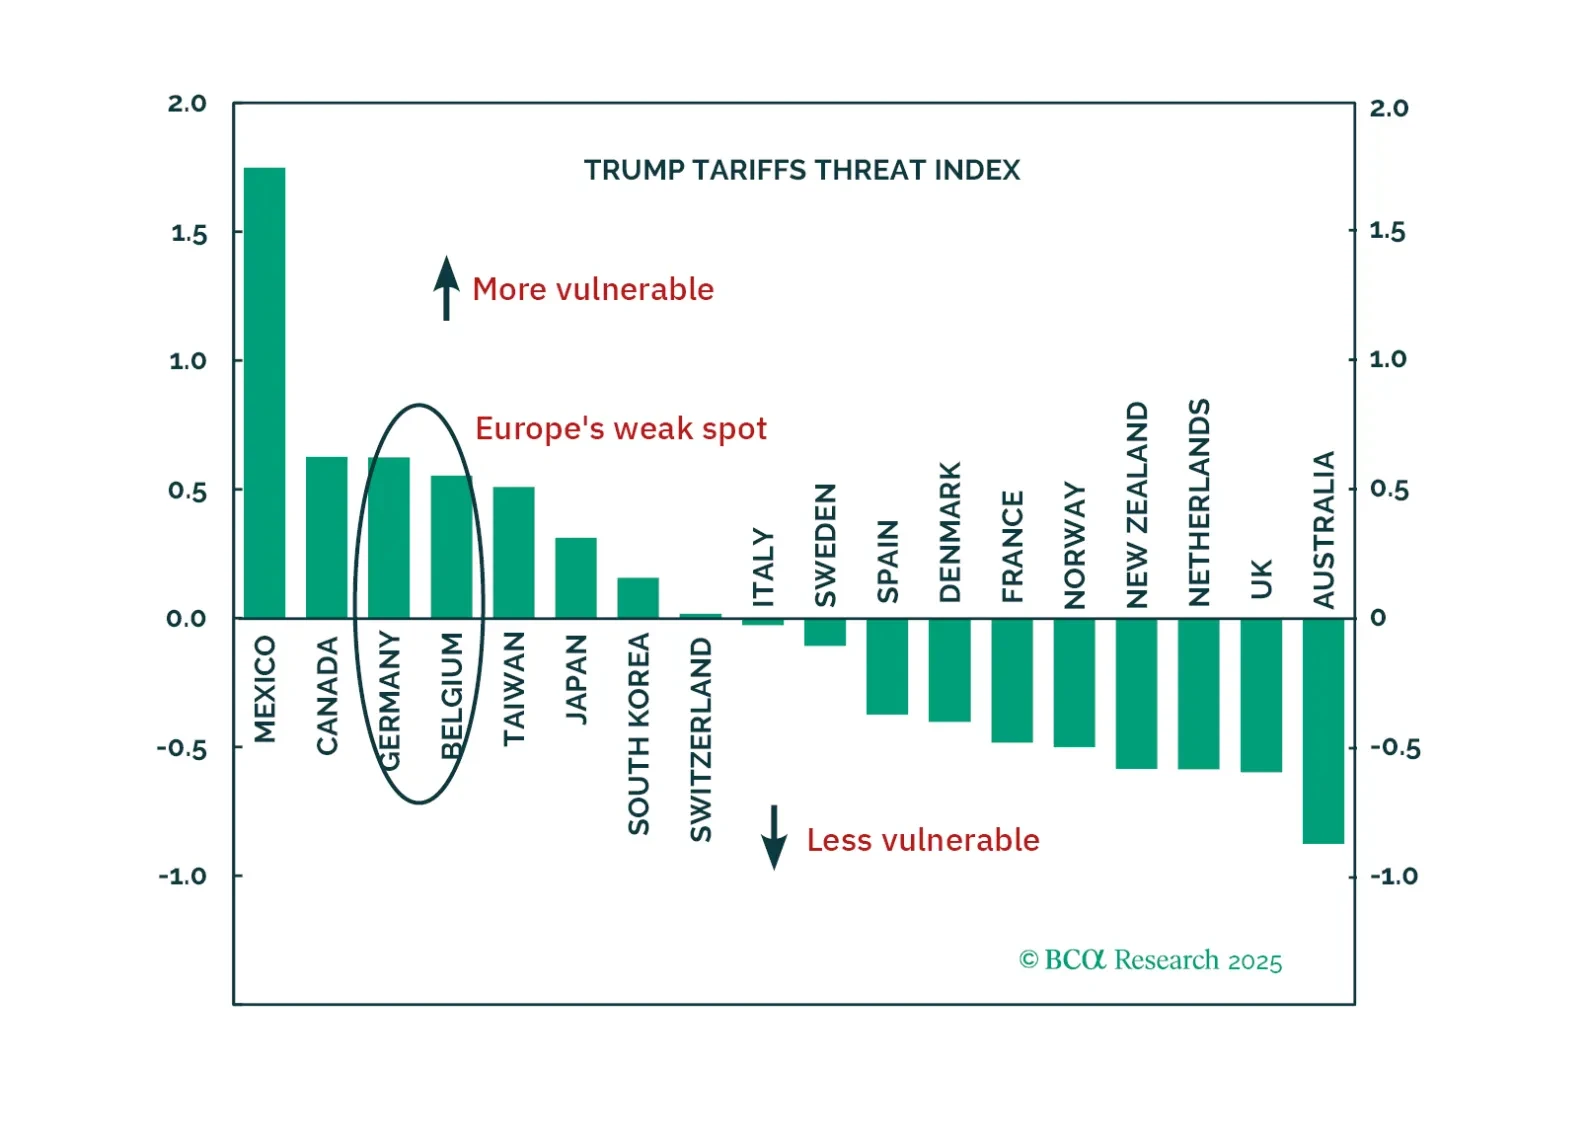
President Trump is about to be inaugurated. Investors often assume all his policies will hurt Europe, but the reality is more nuanced.

This week’s report looks at the US dollar, from the lens of one very cyclical currency – the Australian dollar.
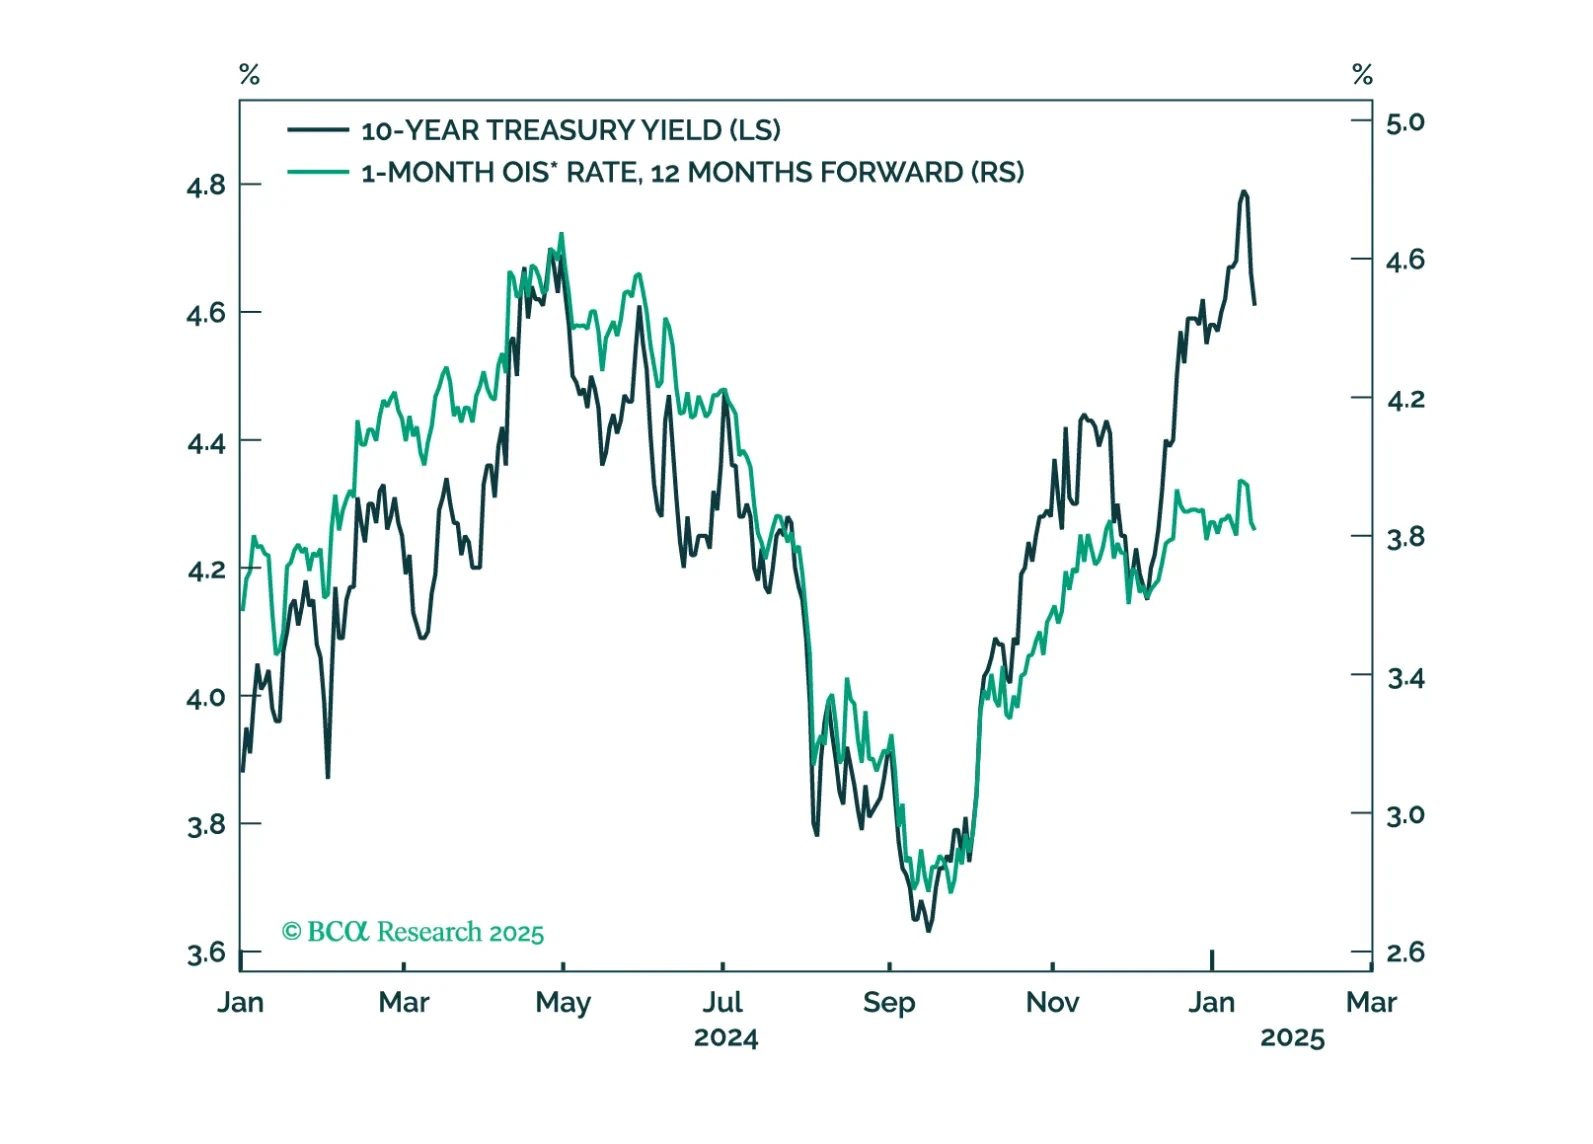
We examine Treasury market valuation and look for indicators that could help us time the next peak in yields. We also update the forecasts from our Treasury yield model.
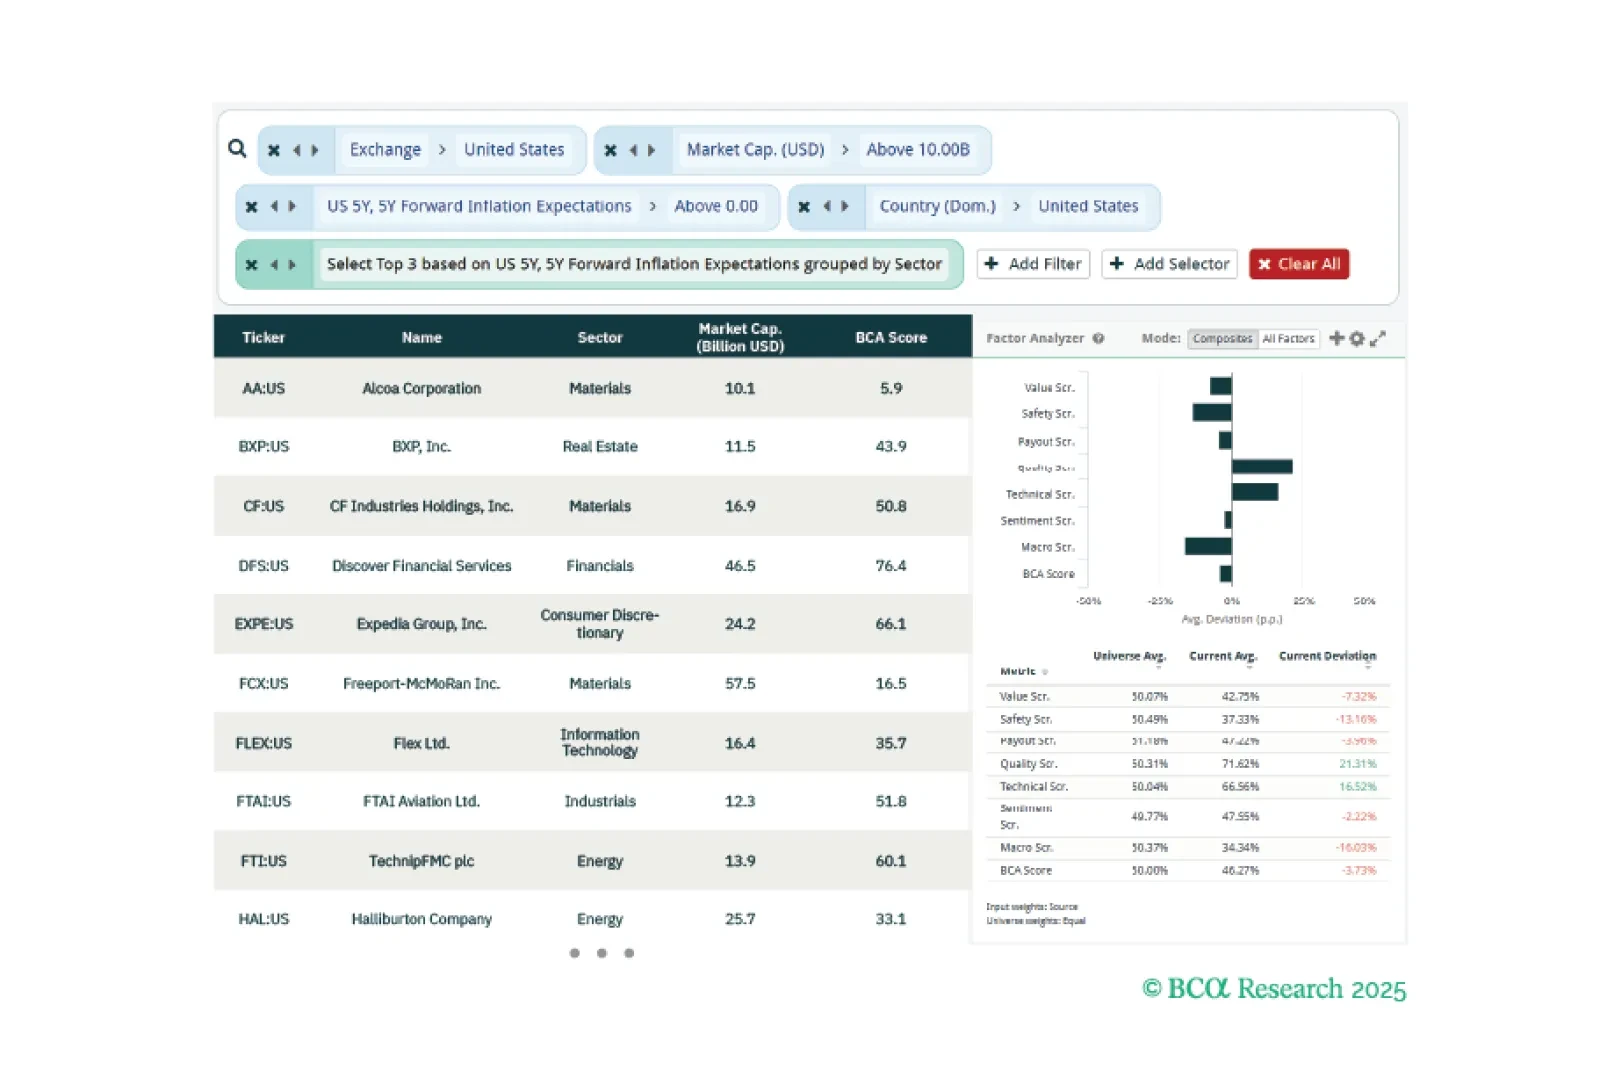
This week, our screeners cover views on Trump 2.0, defensive US equity sectors, and a pullback in Singapore equities. Our first screener aims to hedge longer term inflation risks that Trump 2.0 will likely generate, targeting US equities that are highly correlated with future inflation expectations. Our second screener identifies several defensive sectors that are worth consideration, in case of a tactical pullback in US equities. Lastly, we pick out Singapore stocks that are cheap and high safety, should a pullback occur in the local bourse given weakening macro and technical conditions.

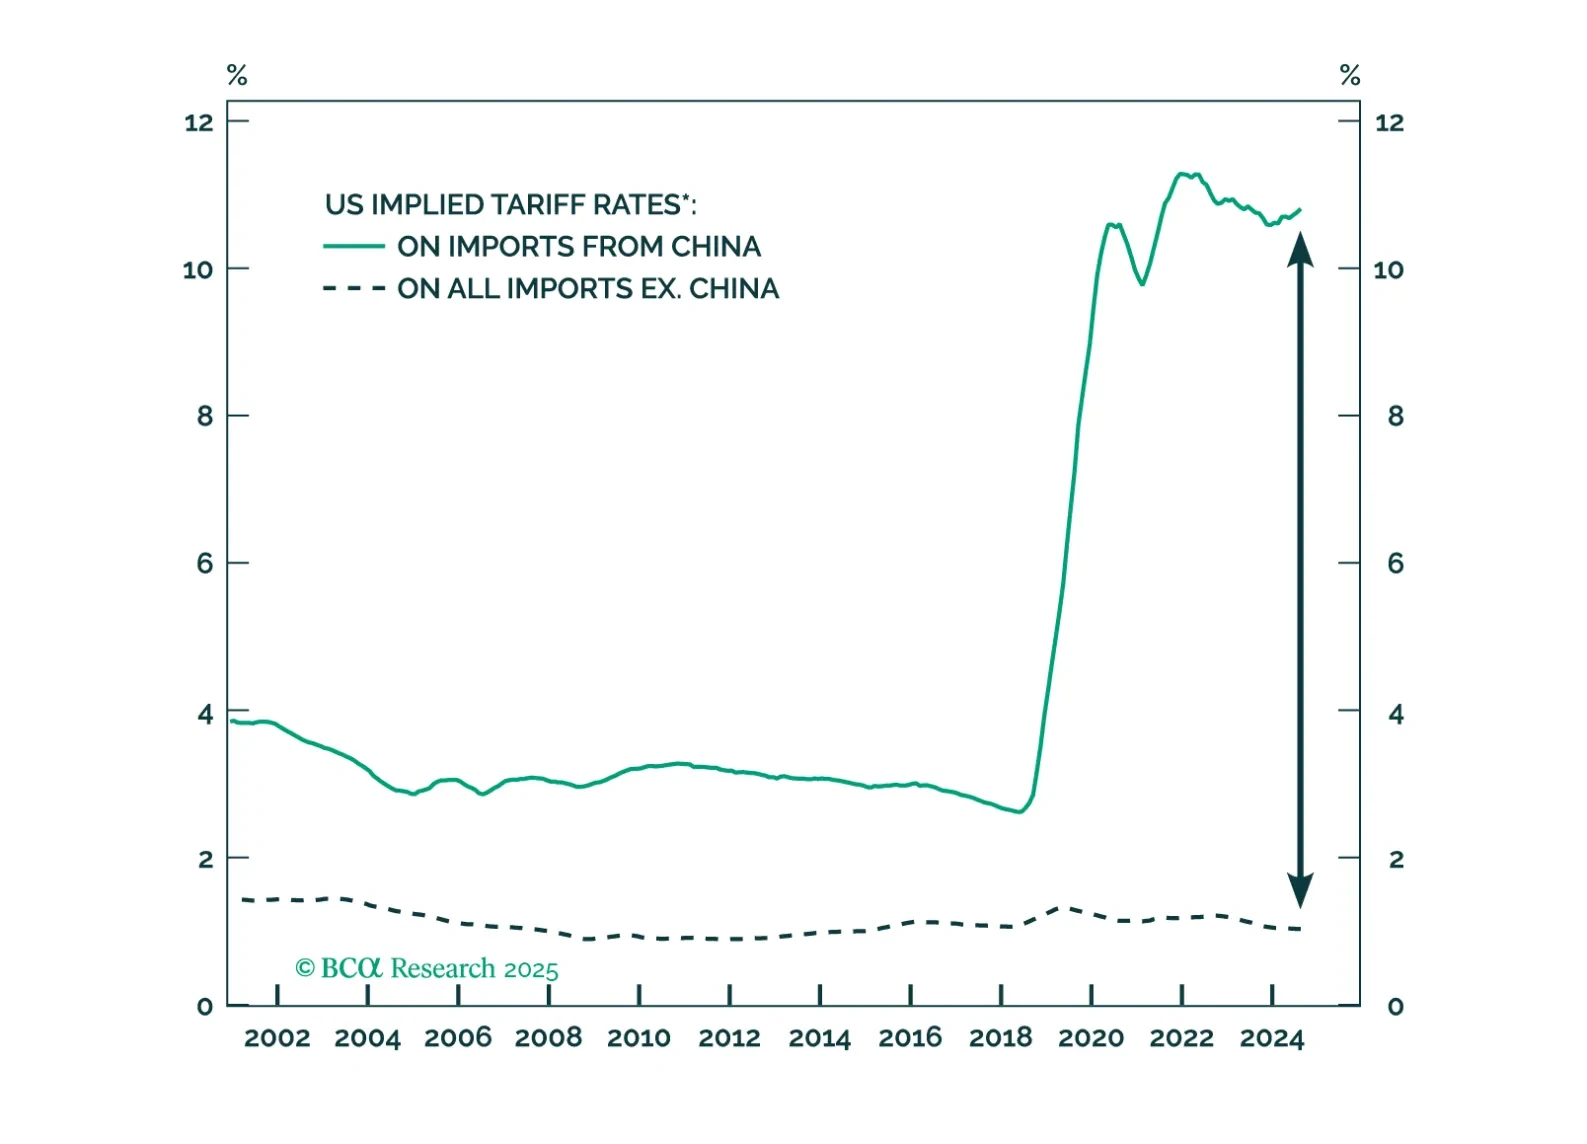
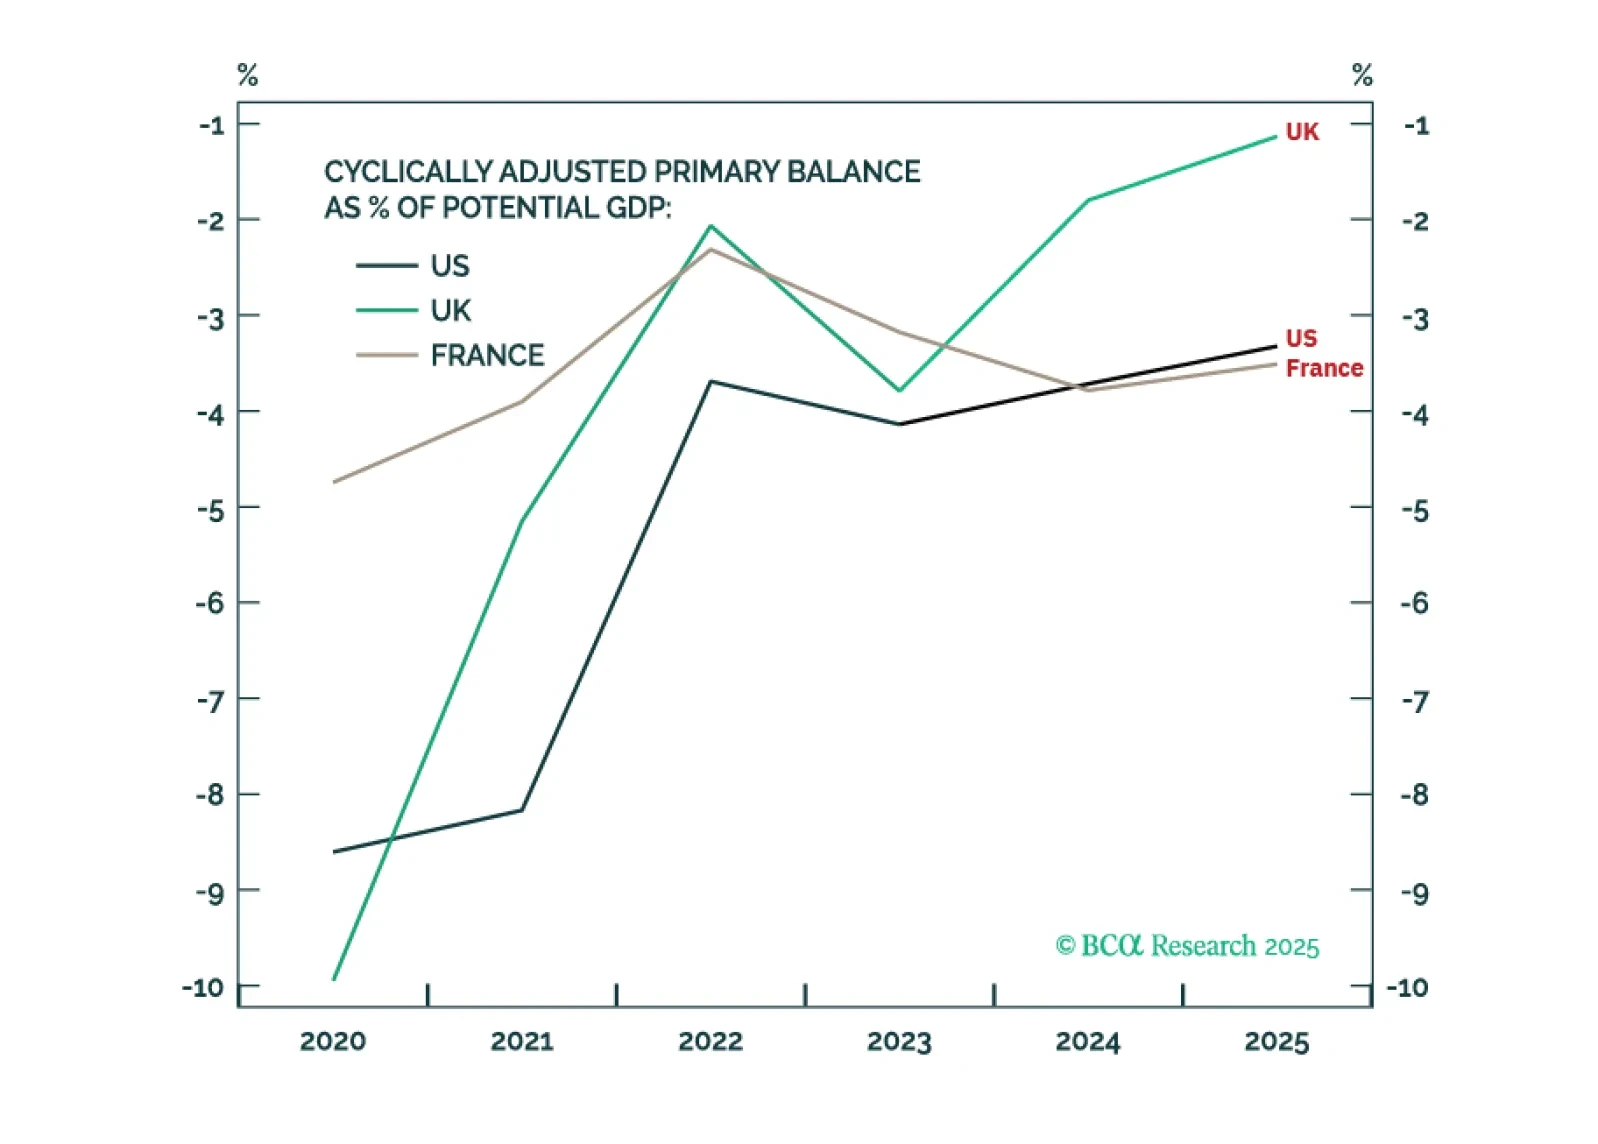
Political instability combined with the maths of debt sustainability is much more concerning in France than in either the UK or the US. Go long UK gilts versus French OATs and go tactically long GBP/USD.

Today, we publish our Quarterly Model Bond Portfolio report. We review the performance of the portfolio in 2024 and discuss how to best position a global fixed income portfolio following the sharp rise in yields during the last months.
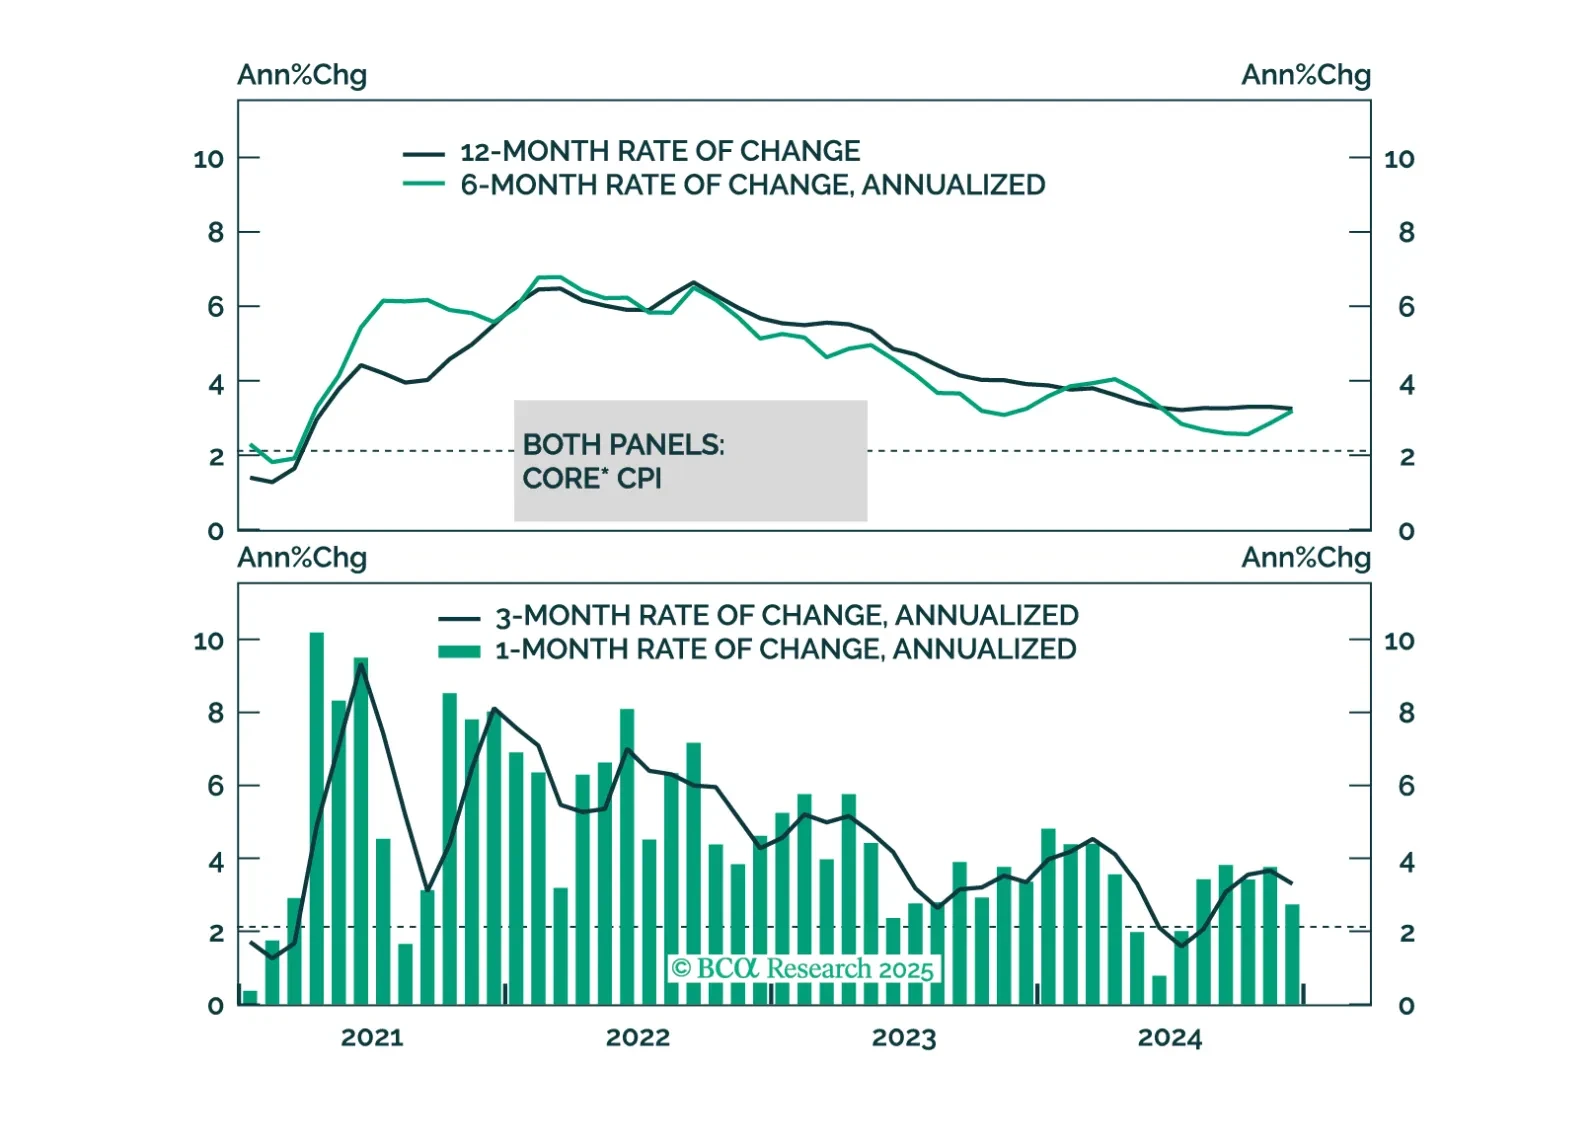
Our thoughts on this morning’s CPI release and some upside risks to inflation that could flare up in the months ahead.

Can Singapore stocks continue the bull run into 2025? What does the city-state’s manufacturing and export outlook foretell? Is the Singapore dollar still competitive? See our analysis and investment recommendations in today’s report.